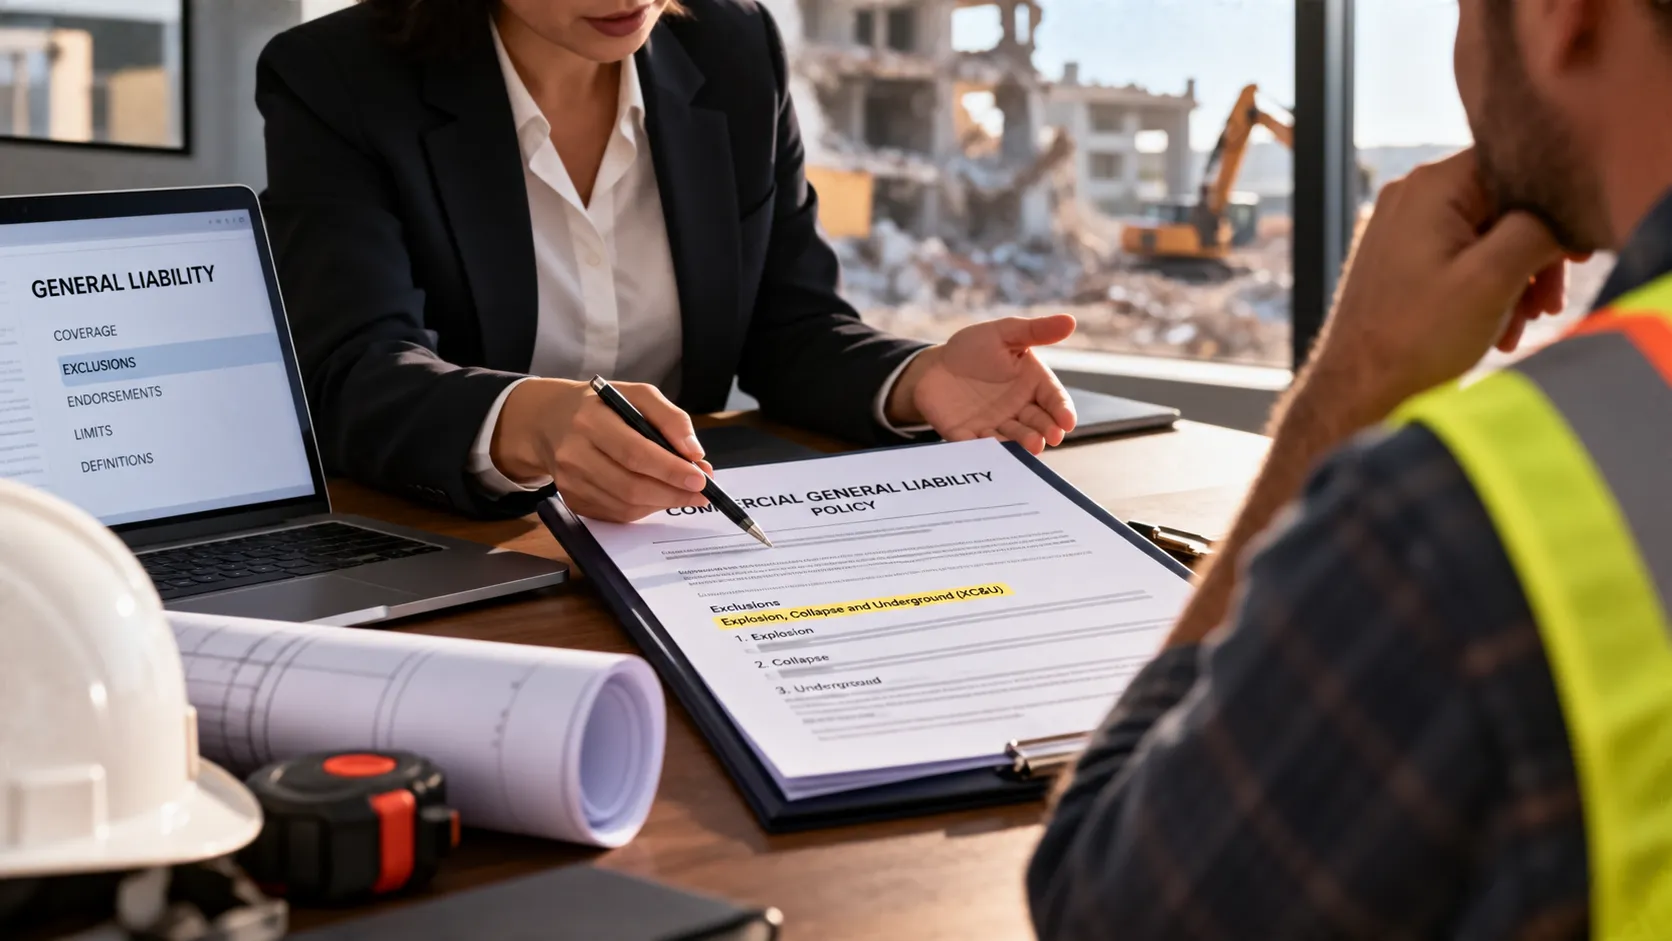
What Insurance Does a Concrete Sawing & Drilling Contractor Need?

What Insurance Does a Concrete Sawing & Drilling Contractor Need?

Concrete sawing and drilling isn’t ordinary construction work.

Your crews may be cutting structural concrete, core drilling through walls and floors, operating powerful saws, working around heavy materials, transporting specialized equipment, or performing precision cuts where a mistake could damage much more than the concrete itself.

Those risks make insurance for concrete sawing and drilling contractors more specialized than many business owners realize.

A basic commercial insurance policy may not address every exposure created by your actual operations.

Depending on the business, a concrete cutting contractor may need to consider:

  • General liability insurance
  • Workers’ compensation insurance
  • Contractors pollution liability
  • Commercial auto insurance
  • Property and equipment coverage
  • Excess liability
  • Surety bonds

The right combination depends on what your company actually does.

A contractor primarily performing slab sawing may have different exposures than a company doing core drilling, wall sawing, wire sawing, selective demolition, grooving and grinding, or other specialty concrete work.

That’s why the first question shouldn’t simply be:

“How much does concrete contractor insurance cost?”

A better place to start is:

“What risks does my concrete sawing and drilling business actually need to insure?”

What You’ll Learn

  • What insurance concrete sawing and drilling contractors may need
  • Why general liability is important for concrete cutting businesses
  • How completed operations coverage can matter
  • When contractors pollution liability should be considered
  • Why workers’ compensation is especially important in this trade
  • How commercial auto insurance may apply
  • How to protect expensive concrete cutting and drilling equipment
  • When excess liability may be appropriate
  • What surety bonds do
  • What insurance underwriters may want to know about your concrete cutting business
  • Why subcontracting, experience, loss history, and operations can affect insurability
  • What to prepare before requesting a concrete contractor insurance quote

Why Is Concrete Sawing and Drilling Insurance So Specialized?

Concrete sawing and drilling combines several different types of risk.

There’s the obvious risk to employees operating powerful equipment.

But there’s also potential damage to the property you’re working on.

A core drill isn’t being used in an empty field.

You may be cutting or drilling through an existing structure containing:

  • Electrical systems
  • Plumbing
  • Gas lines
  • Reinforcing steel
  • Post-tension systems
  • Communication lines
  • Other utilities or structural components

Then there’s the equipment itself.

Professional concrete saws, drilling equipment, generators, vacuums, trailers, vehicles, and related tools can represent a significant investment.

And depending on the work being performed, there may also be environmental or pollution exposures.

That’s why insurance for a concrete sawing contractor often involves more than one policy.
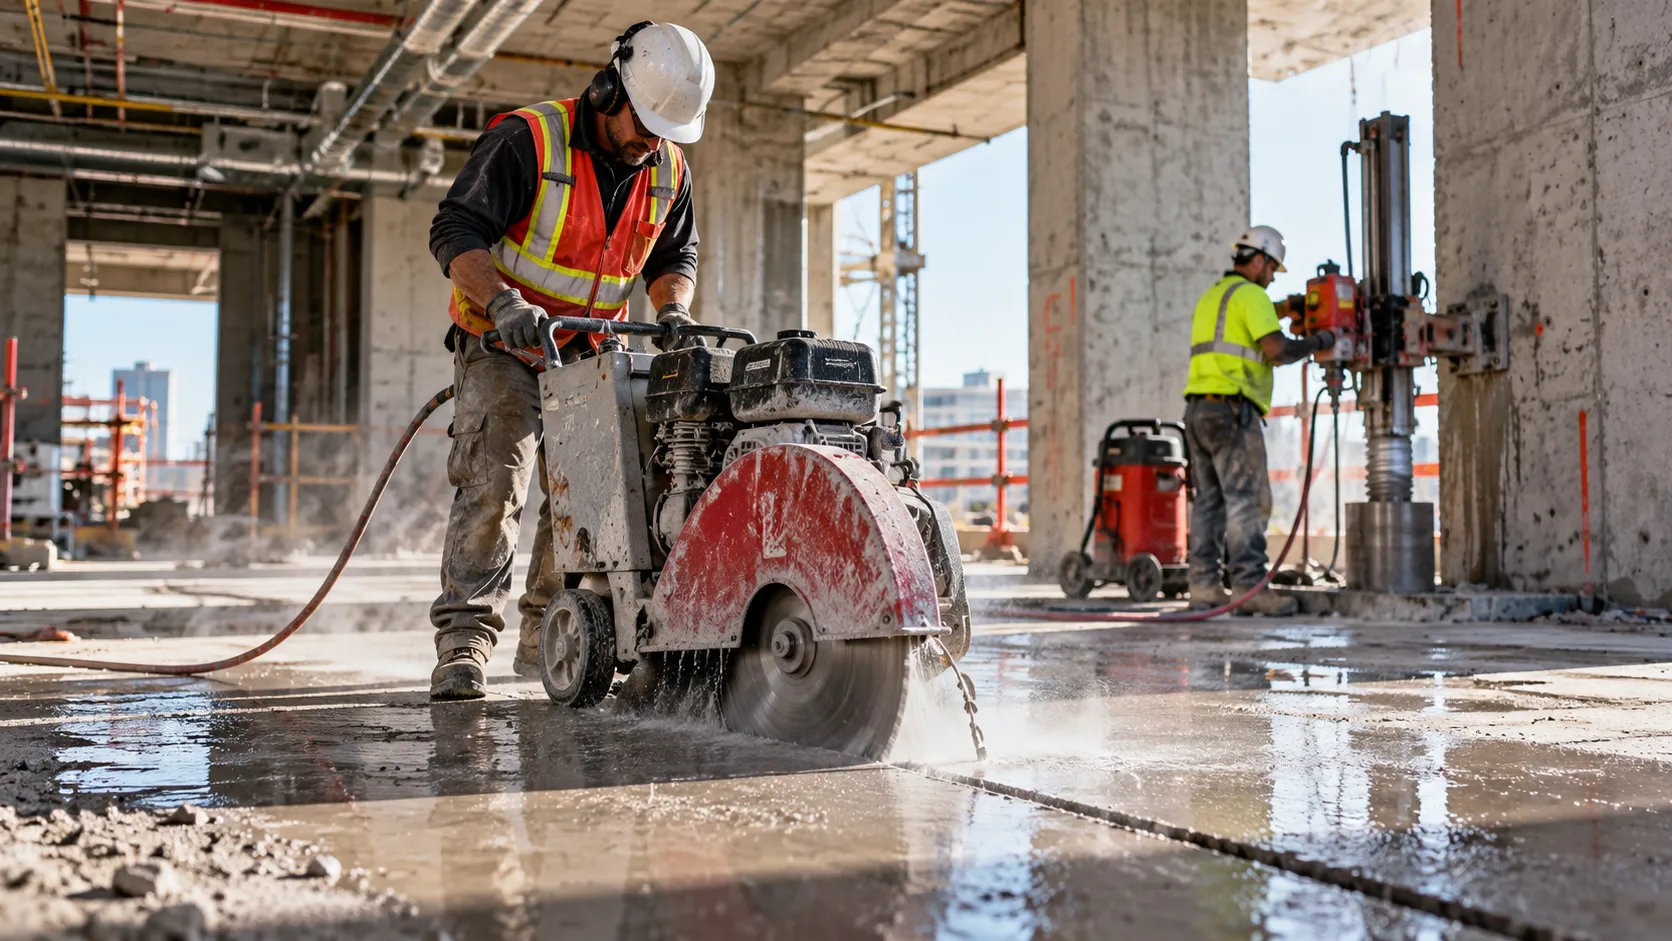
Concrete sawing and drilling contractors wearing safety equipment operate a walk-behind concrete saw and wall-mounted core drilling rig inside a commercial construction site with exposed structural concrete, pipes, and active renovation work.

1. General Liability Insurance for Concrete Sawing and Drilling Contractors

Commercial general liability is one of the foundational coverages for many concrete cutting and drilling businesses.

It may respond to certain covered claims involving third-party bodily injury or property damage arising from your operations, subject to the policy’s terms, conditions, limitations, and exclusions.

Consider the environment in which concrete cutting takes place.

Your crew may be working inside:

A commercial building.

A warehouse.

A parking structure.

An industrial facility.

A school.

A hospital.

A construction project.

An occupied property.

You’re performing work that can potentially affect the surrounding structure and other people on the jobsite.

That creates liability exposure.

What Could Go Wrong During Concrete Cutting?

Imagine you’re core drilling through a concrete floor.

The hole needs to be precisely located.

But there’s something inside or beneath that slab that wasn’t anticipated.

Or imagine a wall-sawing operation where surrounding property is accidentally damaged.

Or a third party is injured near the work area.

Those are the types of situations that demonstrate why concrete cutting contractor insurance needs to reflect the actual work being performed.

The exact response of any insurance policy depends on the specific circumstances and policy language.

General Liability Isn’t Just About Accidents During the Job

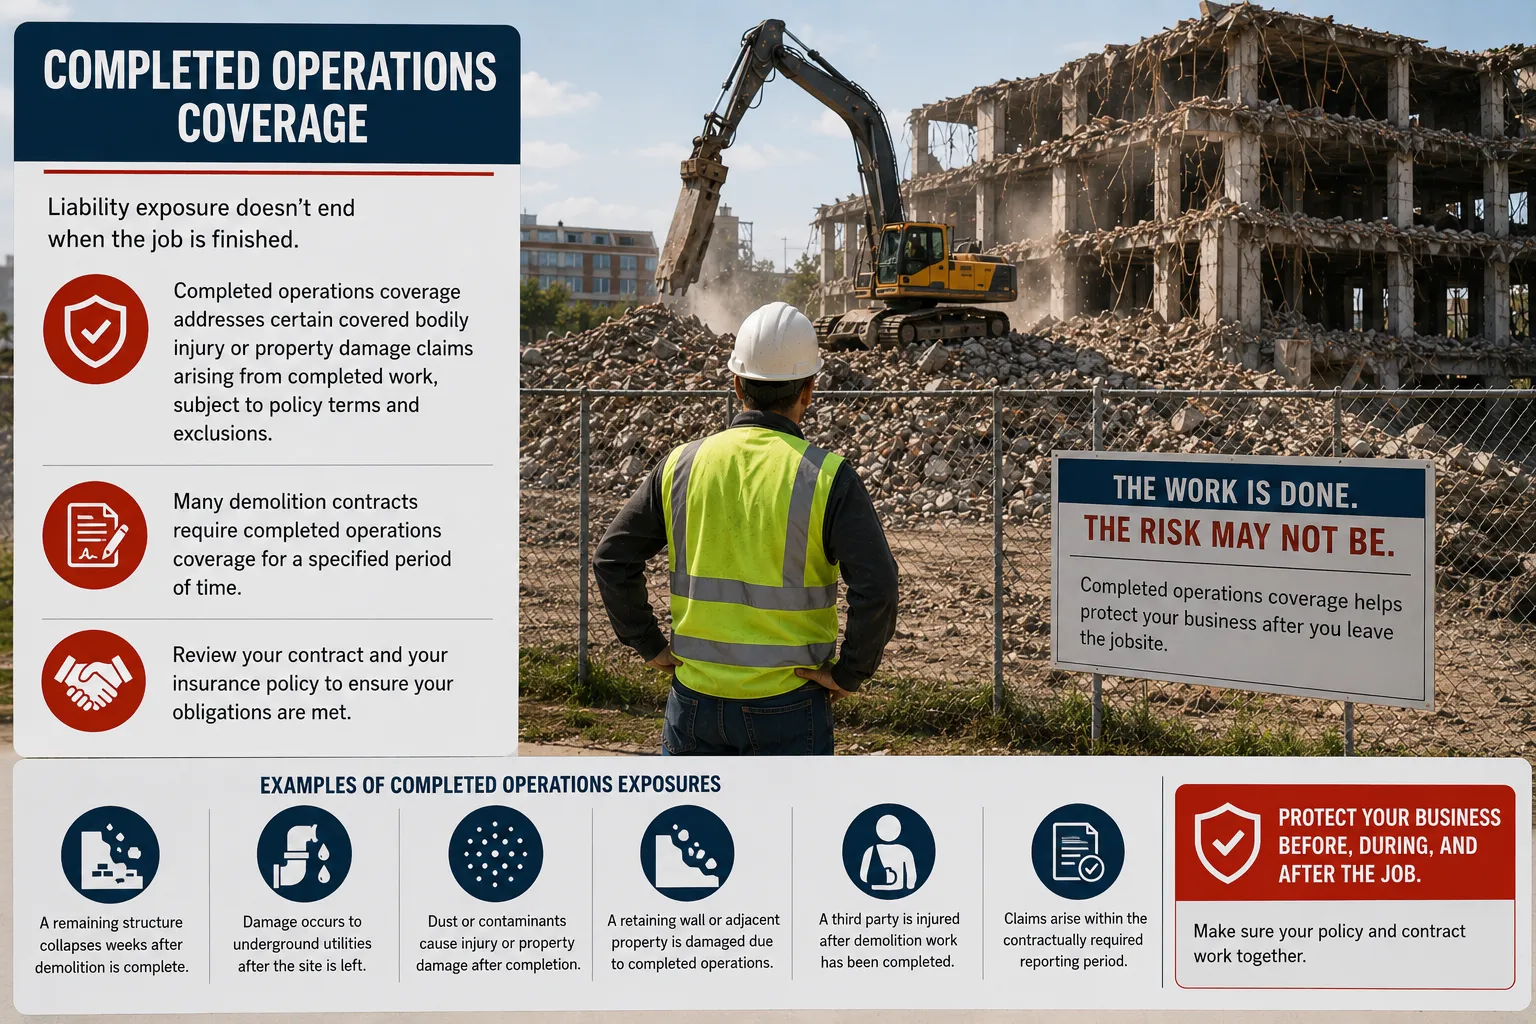
Concrete sawing contractors should also understand completed operations exposure.

A problem doesn’t always become apparent while your crew is still on the job.

Something associated with completed work could potentially result in a claim later.

That’s why contractors should understand how their general liability coverage addresses both ongoing and completed operations.

Contract Requirements Matter Too

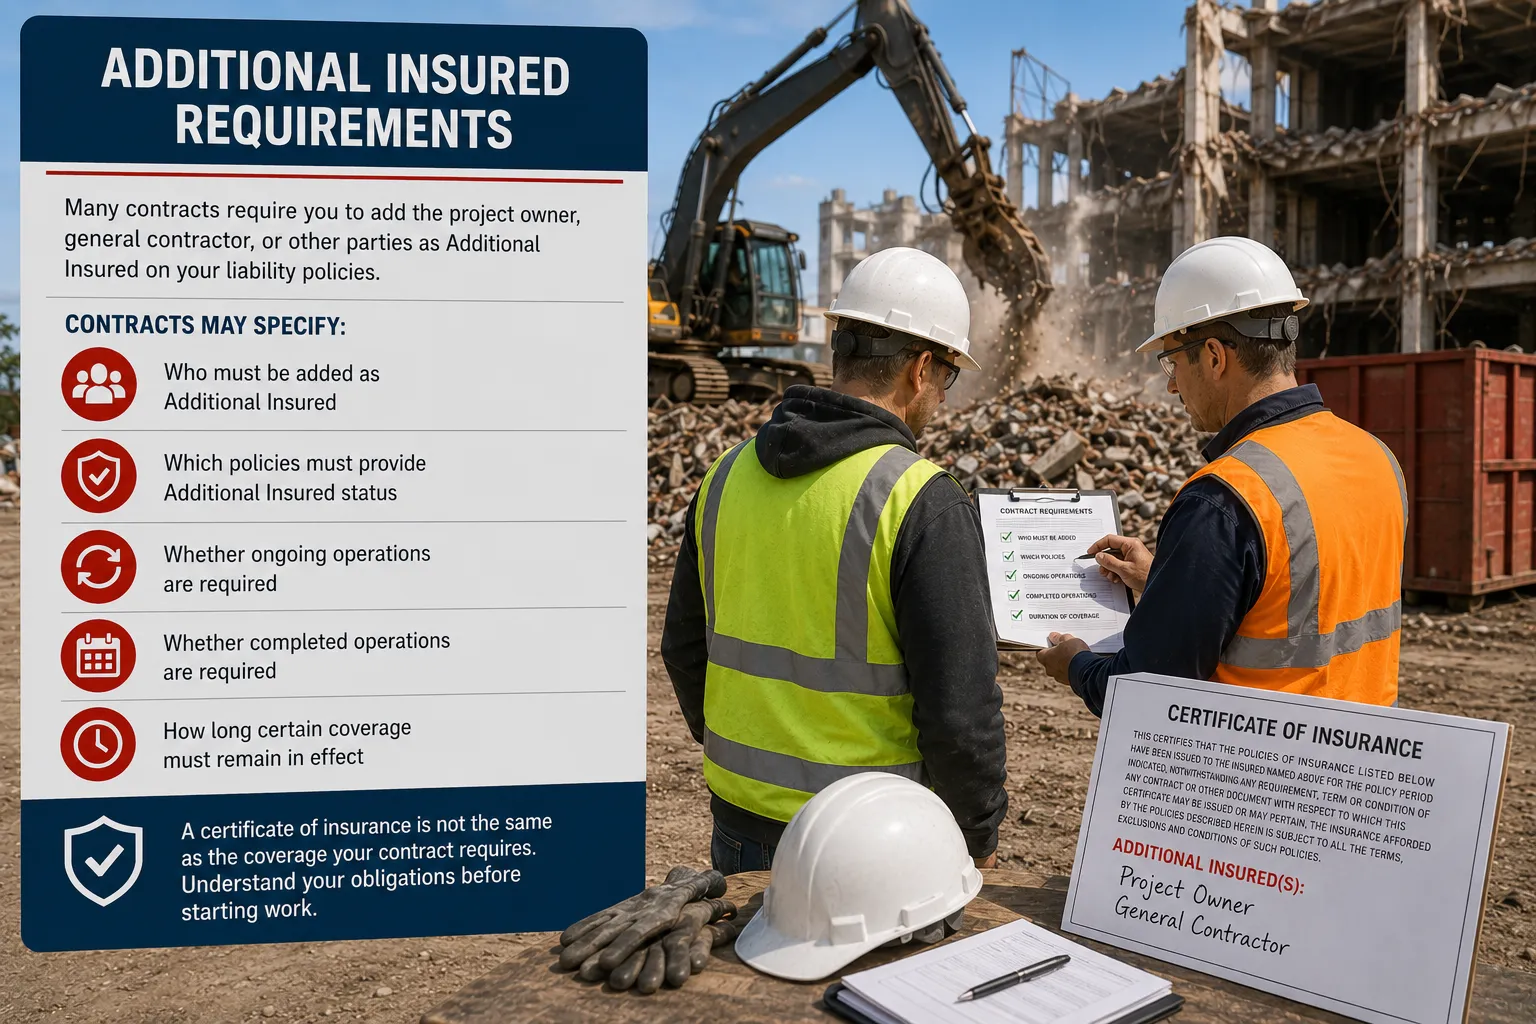
Commercial contractors frequently encounter insurance requirements written into their contracts.

Those requirements may include provisions involving:

  • Additional insured status
  • Primary and noncontributory wording
  • Waiver of subrogation
  • Specific liability limits
  • Per-project aggregates
  • Completed operations

Don’t assume that having a certificate of insurance automatically means every contractual insurance requirement has been satisfied.

Your broker or insurance professional should review what the contract requires and compare it with the coverage actually available.

Concrete sawing and drilling contractors wearing safety equipment operate a walk-behind concrete saw and wall-mounted core drilling rig inside a commercial construction site with exposed structural concrete, pipes, and active renovation work.

2. Workers’ Compensation Insurance

Concrete cutting is physical work.

Employees may be operating saws, drills, heavy equipment, generators, vacuums, hoses, and other tools in active construction environments.

Potential workplace exposures can include:

  • Cuts and lacerations
  • Strains
  • Falls
  • Equipment-related injuries
  • Noise
  • Flying debris
  • Heavy lifting
  • Dust exposure
  • Repetitive physical stress

Workers’ compensation is designed to address covered work-related employee injuries and illnesses, subject to applicable laws and policy terms.

Requirements vary by jurisdiction, but contractors with employees should pay particularly close attention to workers’ compensation obligations.

Concrete Dust Deserves Special Attention

Cutting, drilling, grinding, and otherwise disturbing concrete can generate dust.

That makes proper safety procedures important independently of insurance.

Insurance shouldn’t be viewed as a replacement for:

  • Proper equipment
  • Appropriate dust-control procedures
  • Employee training
  • Personal protective equipment
  • Applicable workplace-safety requirements

A strong safety program can protect employees while also presenting the business more favorably to an insurance underwriter.

Your Safety Program Can Affect More Than Safety

When an underwriter evaluates a concrete sawing and drilling contractor, they’re trying to understand risk.

Two companies with the same annual revenue aren’t necessarily the same risk.

One may have:

Documented safety procedures.

Experienced employees.

Good loss history.

Well-maintained equipment.

Strong jobsite controls.

Another may not.

Insurance underwriting can involve much more than simply asking:

“How much revenue do you have?”
Construction worker wearing protective equipment kneels and holds his injured knee at an active concrete-cutting job site, while a coworker operates a concrete saw in the background, highlighting workplace injury risks and the importance of workers’ compensation insurance for concrete sawing and drilling contractors.

3. Contractors Pollution Liability

Pollution insurance may not be the first coverage a concrete contractor thinks about.

But it’s worth discussing.

Concrete sawing, cutting, drilling, grinding, and related operations can involve:

  • Dust
  • Slurry
  • Waste material
  • Fuels
  • Oils
  • Other substances associated with equipment or jobsites

General liability policies may contain pollution exclusions or limitations.

That means a contractor shouldn’t simply assume that every environmental claim would automatically fall under general liability.

What Is Contractors Pollution Liability?

Contractors pollution liability is designed to address certain pollution-related exposures arising from contracting operations, subject to the specific policy.

Depending on the policy and circumstances, coverage may address certain claims involving pollution conditions, cleanup costs, bodily injury, or property damage.

Because policy language varies, contractors should discuss their actual operations with an insurance professional rather than assuming pollution coverage is included elsewhere.

Does Every Concrete Cutting Contractor Need Pollution Insurance?

Not necessarily in exactly the same form.

That’s why underwriting matters.

Consider:

Where do you work?

What materials do you encounter?

How do you manage concrete slurry?

Do you perform work in environmentally sensitive locations?

What contracts are you accepting?

What does your general liability policy exclude?

Your insurance program should be built around the answers.
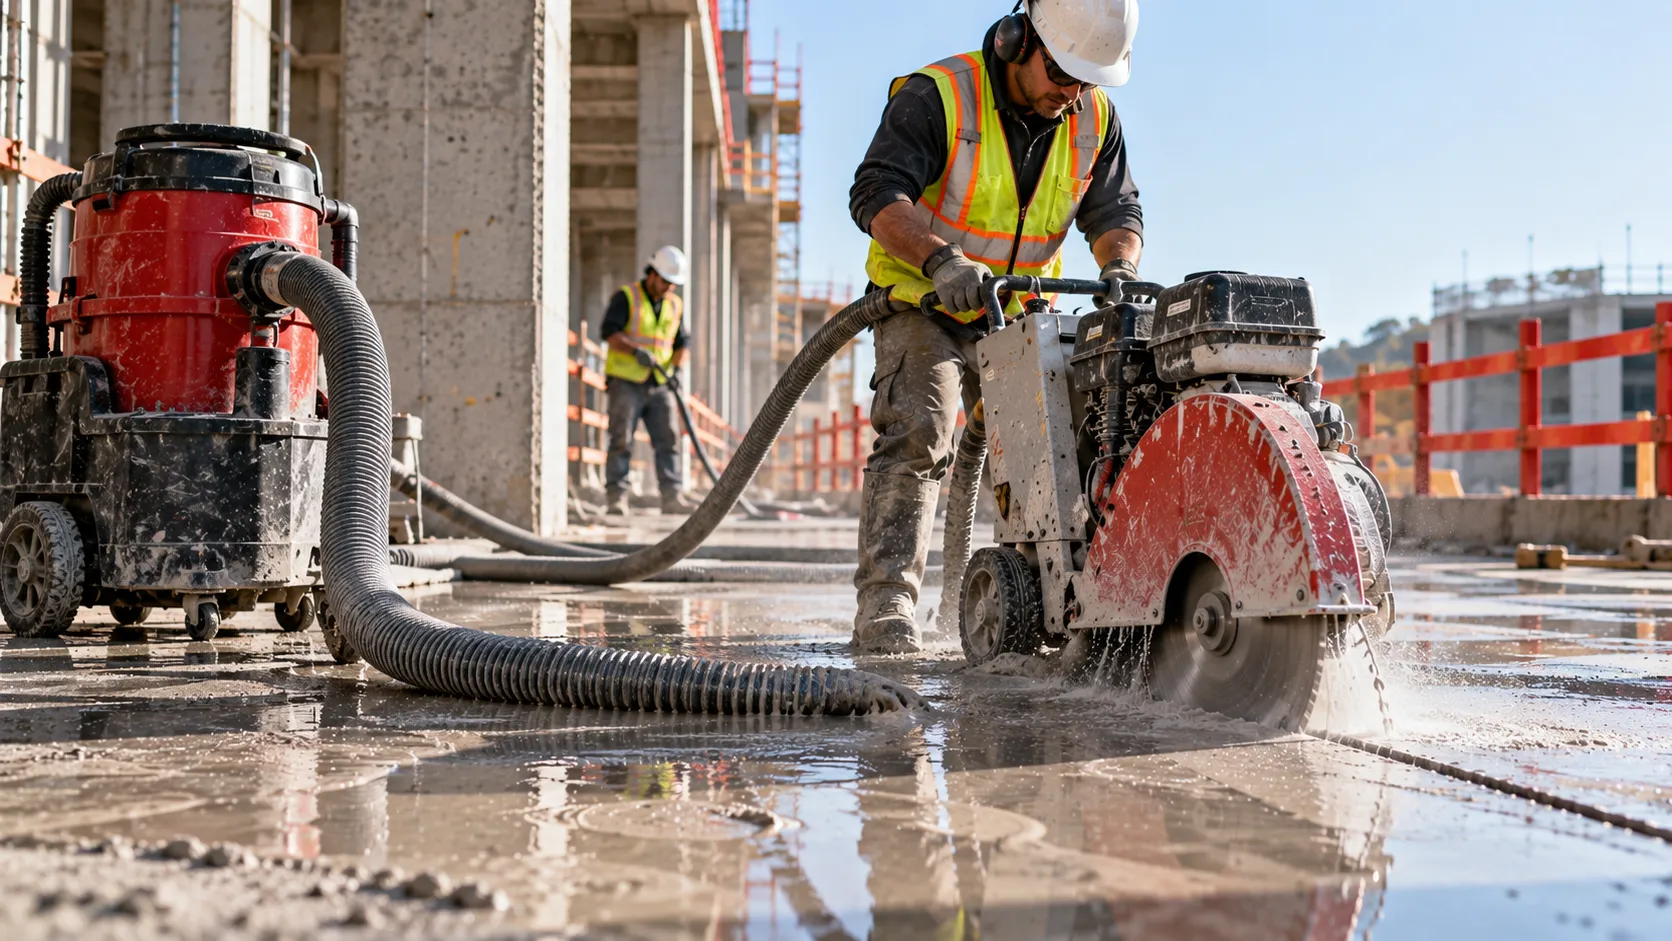
Concrete cutting contractor operating a walk-behind concrete saw on a wet construction site, with an industrial vacuum, collection hoses, and concrete slurry on the floor, illustrating dust control, waste management, and potential pollution exposures relevant to contractors pollution liability insurance.

4. Commercial Auto Insurance

Concrete cutting businesses don’t leave their equipment at the office.

Crews travel.

Equipment travels.

Materials travel.

You may operate:

  • Work trucks
  • Vans
  • Service vehicles
  • Trucks pulling equipment trailers
  • Other company vehicles

Personal auto insurance generally isn’t designed to replace appropriate commercial coverage for business vehicle exposures.

A commercial auto policy may therefore be an important part of a concrete sawing and drilling contractor’s insurance program.

Don’t Forget What’s Being Transported

The truck is one exposure.

The equipment inside or behind it is another.

Suppose a trailer contains specialized cutting or drilling equipment.

What happens if:

The vehicle is involved in an accident?

Equipment is damaged?

Tools are stolen?

A trailer is damaged?

The answer may involve different coverages.

That’s why commercial auto and equipment coverage should be evaluated together rather than assuming one automatically covers everything.
Construction workers secure specialized concrete sawing and drilling equipment on a utility trailer attached to a work truck at an active construction site, illustrating commercial vehicle, trailer, and transported equipment risks for concrete cutting contractors.

5. Property and Equipment Coverage

Concrete sawing and drilling requires specialized equipment.

Depending on the contractor, that could include:

  • Slab saws
  • Wall saws
  • Wire saws
  • Core drills
  • Hand saws
  • Grinding equipment
  • Generators
  • Vacuums
  • Ground-penetrating radar equipment
  • Trailers
  • Other specialized tools

Replacing this equipment can be expensive.

And unlike equipment permanently located inside a building, contractor equipment frequently moves between jobsites.

Does General Liability Cover Your Concrete Saw?

Generally speaking, liability insurance and property/equipment insurance serve different purposes.

General liability primarily addresses certain claims made against your business.

Equipment coverage addresses covered loss or damage involving your own insured property, depending on the policy.

This distinction is important.

A contractor can have substantial general liability limits and still have inadequate protection for expensive tools and equipment.

Inland Marine and Contractor Equipment Coverage

Contractors may use inland marine or contractor equipment coverage to insure eligible tools and equipment that move between locations.

The details matter.

Contractors should understand:

  • Which equipment is scheduled
  • Coverage limits
  • Deductibles
  • Valuation
  • Theft provisions
  • Transit coverage
  • Rental equipment
  • Equipment temporarily located at jobsites

Don’t wait until after a loss to discover how your equipment was insured.
A concrete sawing contractor inspects specialized drilling equipment, concrete saws, and industrial vacuums at a commercial construction site, illustrating the value of protecting expensive contractor equipment and evaluating insurance coverage for large-scale projects.

6. Excess Liability Insurance

Some contractors need liability limits beyond the underlying policies.

That’s where excess liability may come into the conversation.

A general contractor, property owner, municipality, or other customer may require higher limits as a condition of the contract.

The size and complexity of your projects can also affect the amount of liability protection your company wants to consider.

Bigger Jobs Can Mean Bigger Exposure

Consider the difference between cutting a small slab at a relatively simple jobsite and performing specialty concrete work on a major commercial or industrial project.

The potential consequences of an accident can be dramatically different.

Insurance limits should be evaluated in the context of:

  • Project size
  • Contract requirements
  • Type of work
  • Jobsite
  • Potential severity of a loss
  • Underlying coverage

Excess liability can provide additional limits above certain underlying policies, subject to its own terms and conditions.
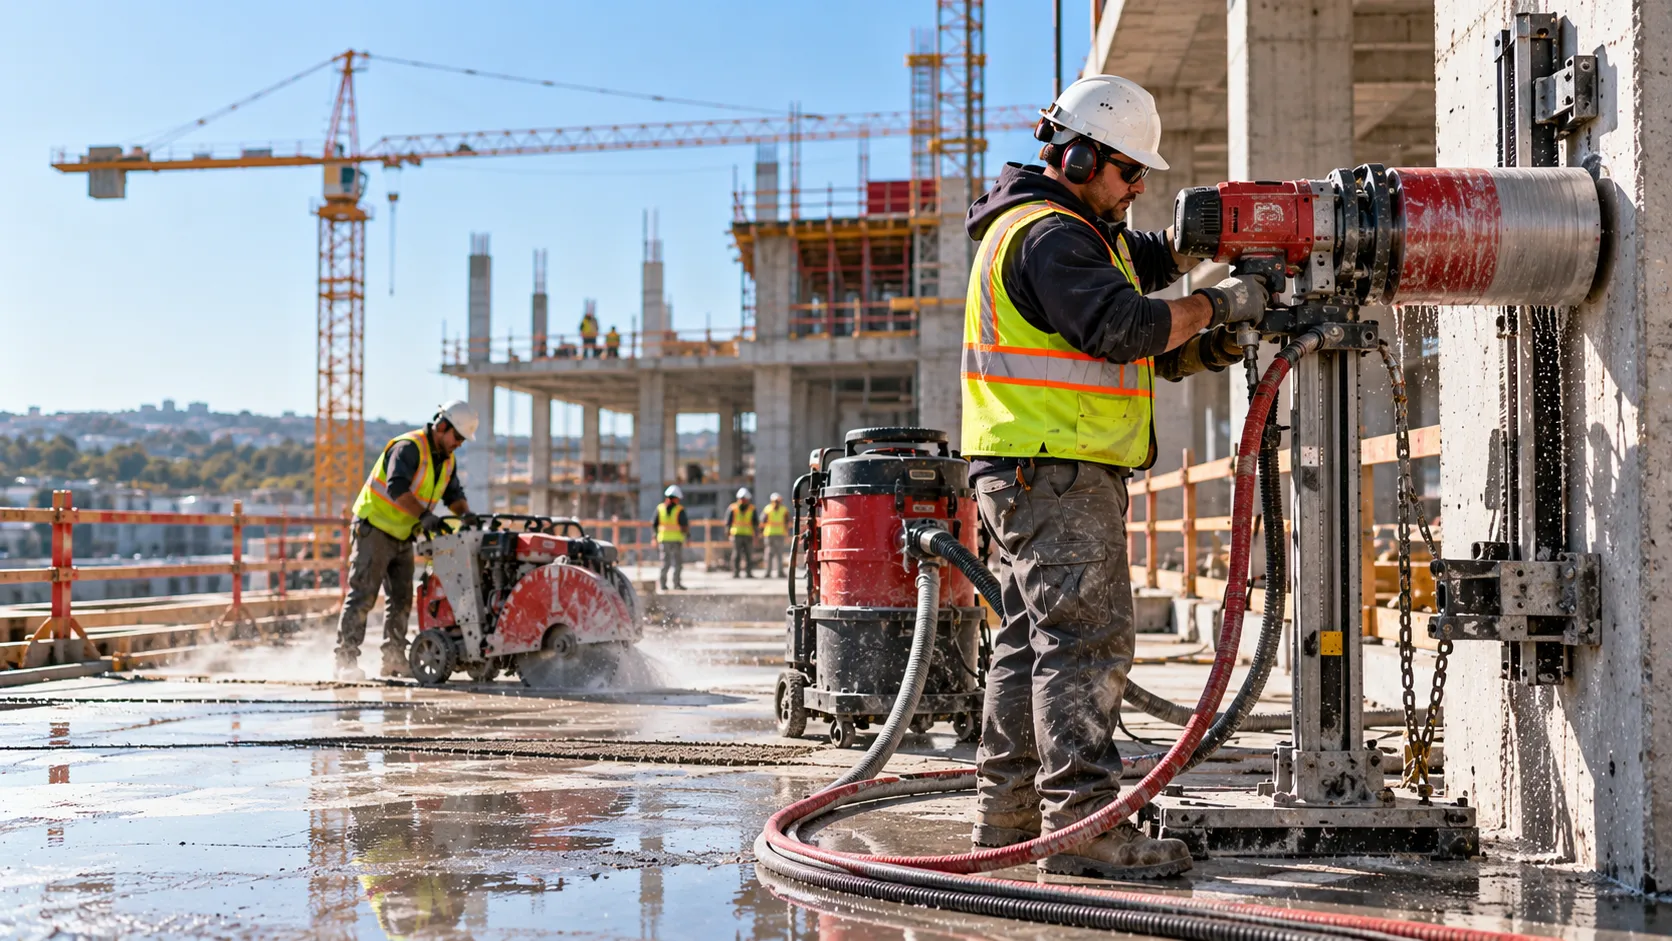
Concrete sawing and drilling contractors operate specialized equipment on a large commercial construction project, with a worker using a wall-mounted core drilling rig in the foreground and another cutting a concrete slab in the background, illustrating the higher liability exposures associated with complex construction projects.

7. Surety Bonds

Insurance and surety bonds aren’t the same thing.

But concrete sawing and drilling contractors may encounter bonding requirements, particularly on certain commercial or public projects.

Depending on the project, a contractor might encounter requirements for:

  • Bid bonds
  • Performance bonds
  • Payment bonds
  • Other contract bonds

A surety bond generally involves a guarantee associated with an obligation rather than traditional insurance protecting the contractor from ordinary business losses.

If you’re bidding larger projects, bonding capacity can become an important business consideration.

What Insurance Does a Core Drilling Contractor Need?

Core drilling contractors generally face many of the same insurance considerations as other specialty concrete contractors.

Depending on operations, those may include:

  • General liability
  • Workers’ compensation
  • Commercial auto
  • Equipment coverage
  • Contractors pollution liability
  • Excess liability
  • Surety bonds

But core drilling also demonstrates why the description of operations matters so much.

Where are you drilling?

What are you drilling through?

How large are the cores?

Are you working overhead?

What types of facilities do you enter?

Are you locating utilities before drilling?

Those details can materially affect how an underwriter views the risk.

What Insurance Does a Concrete Cutting Contractor Need?

“Concrete cutting” can describe several different operations.

Apollo General’s concrete contractor underwriting materials identify operations including:

  • Slab sawing
  • Core drilling
  • Wall sawing
  • Hand sawing
  • Wire sawing
  • Sawing and sealing
  • Grooving and grinding
  • Ground-penetrating radar imaging
  • Selective demolition

That’s important because your insurance company needs to understand what you actually do.

Simply writing “concrete contractor” on an application doesn’t necessarily tell the complete story.

Concrete Sawing Insurance Isn’t the Same as General Concrete Contractor Insurance

A contractor pouring driveways and a contractor wire-sawing reinforced concrete aren’t performing the same work.

Even though both businesses work with concrete, their operations can create different exposures.

Specialized underwriting allows the insurer to evaluate the actual trade rather than treating every company that works with concrete as essentially identical.

That’s one reason working with an insurance provider familiar with concrete sawing, cutting, and core drilling can be valuable.
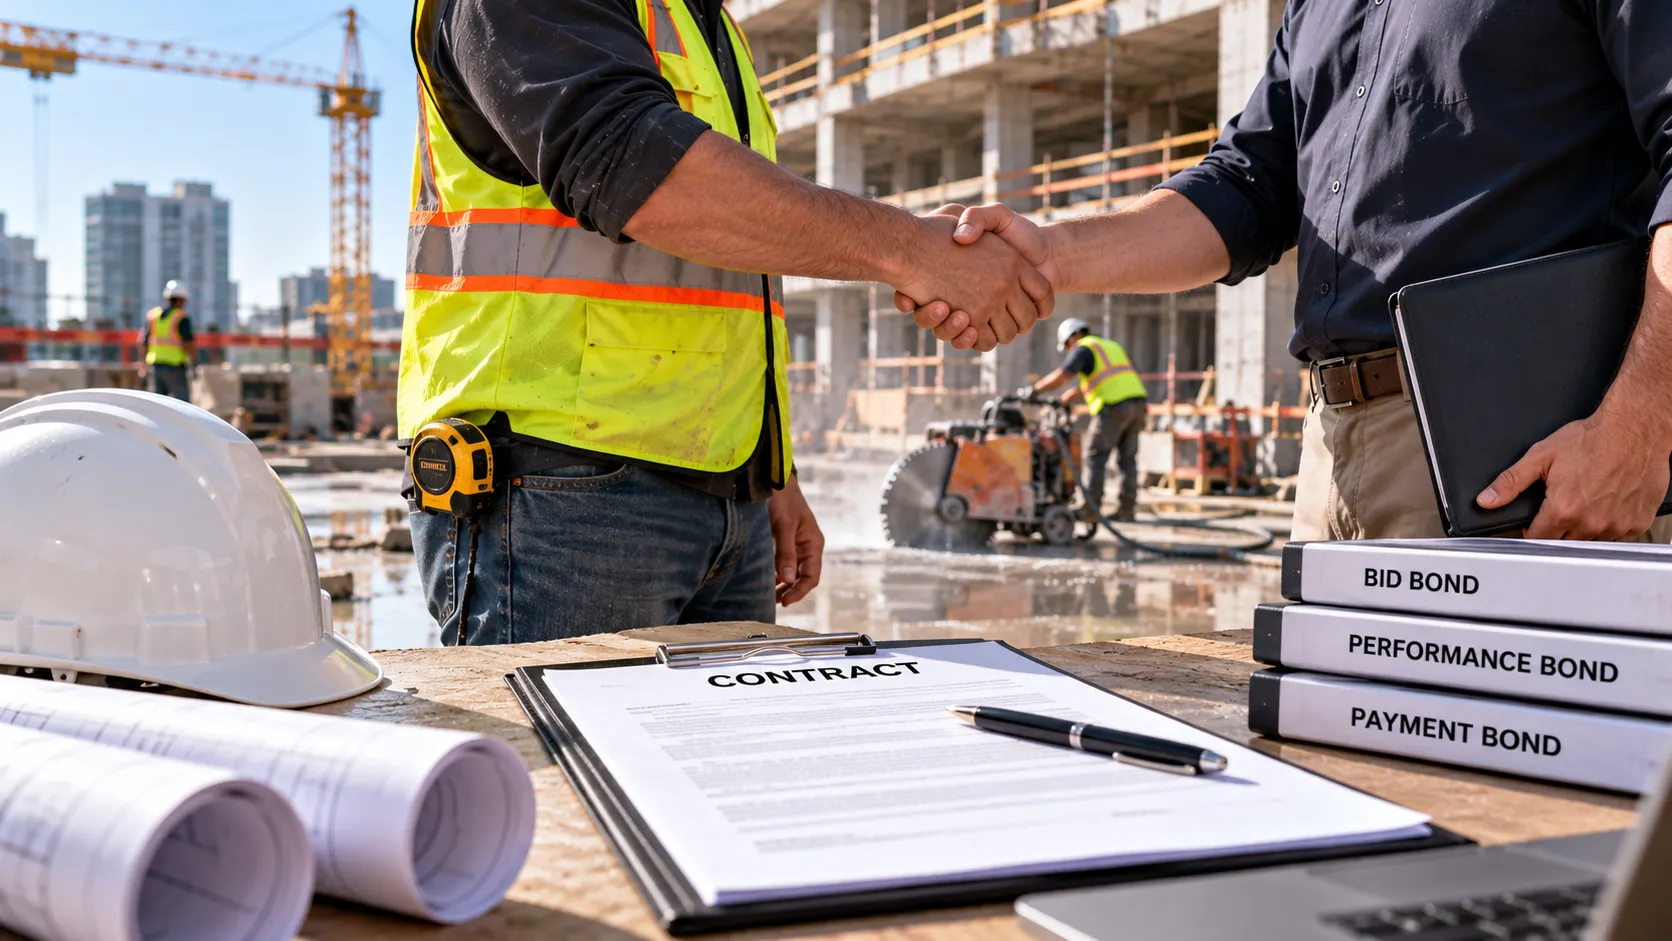
Construction contractor and business professional shake hands over a project contract and construction blueprints at an active commercial jobsite, with bid, performance, and payment bond documents on the table, illustrating surety bond requirements for concrete sawing and drilling contractors pursuing larger projects.

What Do Insurance Underwriters Want to Know About a Concrete Sawing Contractor?

Insurance applications can feel like paperwork.

But there’s a reason underwriters ask so many questions.

They’re trying to understand the business they’re being asked to insure.

For concrete sawing and drilling contractors, relevant information can include:

Years in Business

Experience matters.

An established company with experienced leadership may be evaluated differently from a contractor entering the trade for the first time.

Annual Sales

Revenue helps the underwriter understand the size of the operation.

Payroll

Payroll can help indicate the size of the workforce and amount of work being performed.

Types of Concrete Work

How much of the business involves:

Slab sawing?

Core drilling?

Wall sawing?

Wire sawing?

Hand sawing?

Grinding?

Selective demolition?

Other operations?

Geographic Area

Where does the contractor perform work?

Types of Projects

Residential?

Commercial?

Industrial?

Public works?

Other specialty environments?

Subcontracting

How much work is subcontracted?

What work is subcontracted?

What insurance requirements are imposed on subcontractors?

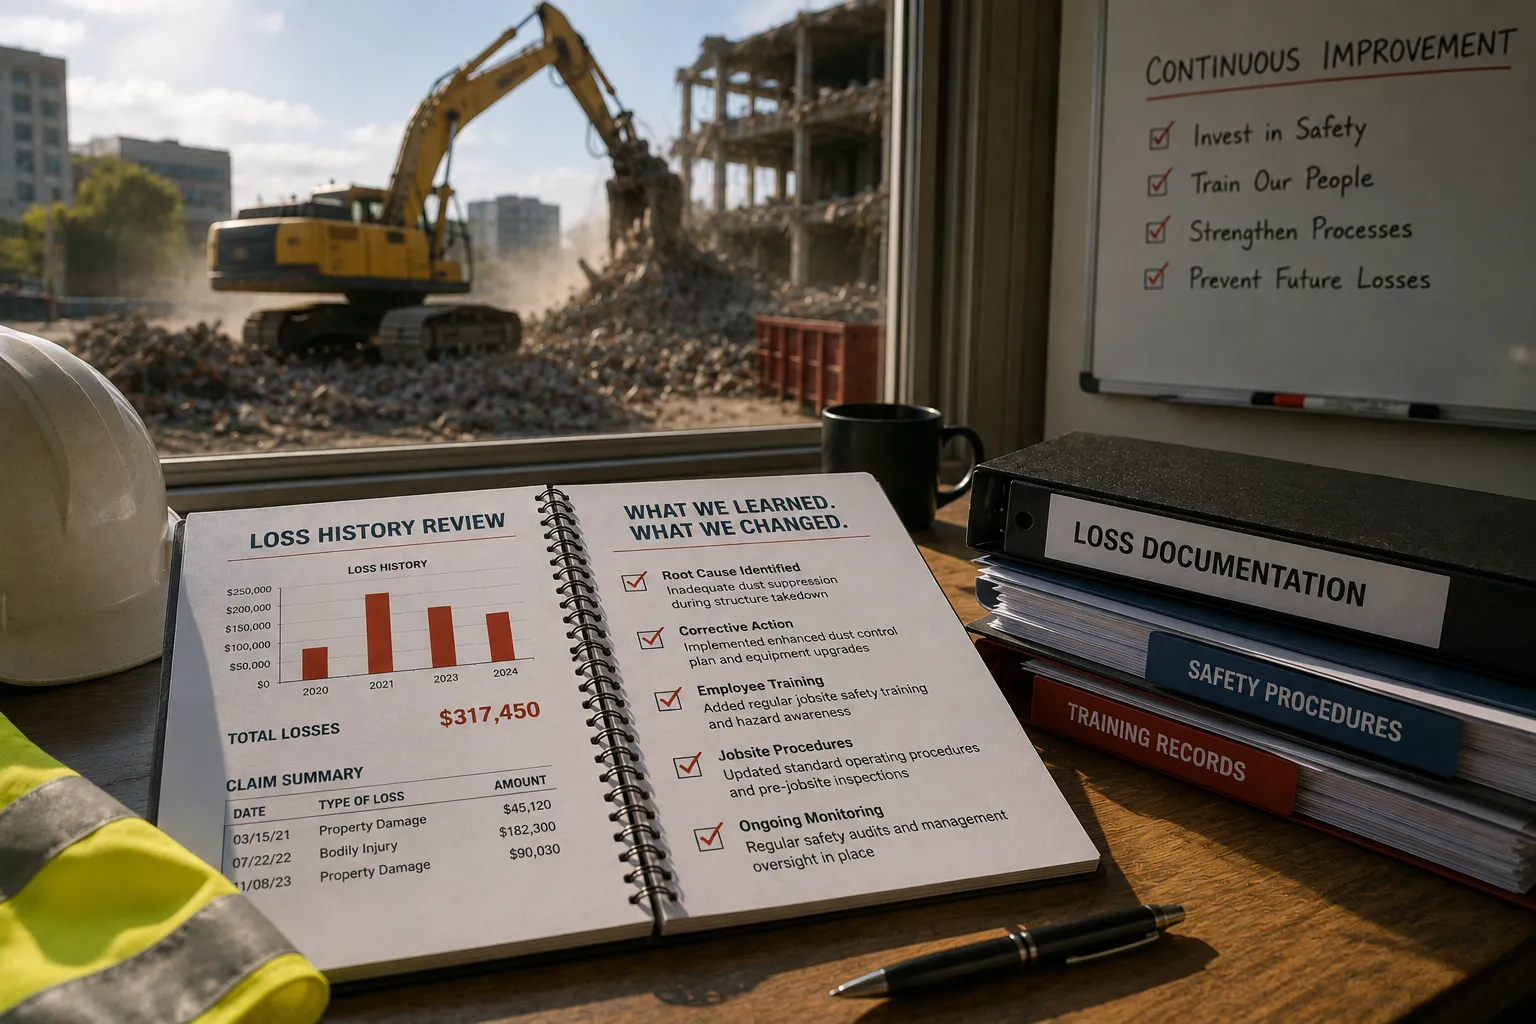
Loss History

Previous claims can be an important underwriting consideration.

The frequency, severity, cause, and corrective action associated with previous losses may all matter.
Concrete sawing contractor and project supervisor review construction blueprints and job details at an active commercial construction site, with concrete-cutting equipment, work vehicles, and crew members in the background, illustrating the business operations, project types, and safety practices insurance underwriters evaluate.

Your Operations Can Affect Eligibility

Not every insurance program is designed for every contractor.

Certain operations may fall outside a carrier’s underwriting appetite.

For example, Apollo General’s current concrete sawing and drilling program identifies several types of operations or circumstances that are ineligible under that particular program.

That doesn’t necessarily mean a contractor is “uninsurable.”

It means that particular program may not be designed for that risk.

This distinction matters.

A specialized insurance professional can help determine whether your operations fit a particular program and what alternatives may need to be explored.

Subcontracting Can Matter More Than You Think

Many specialty contractors subcontract at least some work.

But the percentage and type of subcontracted work can affect underwriting.

Why?

Because subcontracting introduces another company into the chain of responsibility.

Underwriters may want to know:

  • How much work you subcontract
  • What type of work is subcontracted
  • How subcontractors are selected
  • Whether written contracts are used
  • What insurance subcontractors are required to maintain
  • Whether certificates are collected
  • Whether appropriate risk-transfer provisions are in place

Apollo’s current concrete sawing and drilling program, for example, has specific eligibility requirements regarding subcontracting.

That’s another reason to discuss your actual business model rather than shopping solely by premium.

Why Does Loss History Matter?

Past claims don’t automatically determine future performance.

But they give underwriters information.

Suppose a company had a substantial loss.

An underwriter may want to know:

What happened?

More importantly:

What changed afterward?

Maybe the company introduced new procedures.

Changed training.

Changed equipment.

Added jobsite verification.

Improved subcontractor controls.

A good explanation can provide considerably more context than simply listing a dollar amount.

What Should You Prepare Before Requesting a Concrete Sawing Insurance Quote?

Being prepared can make the submission process easier.

Apollo General currently asks applicants in its concrete sawing and drilling program for information that includes:

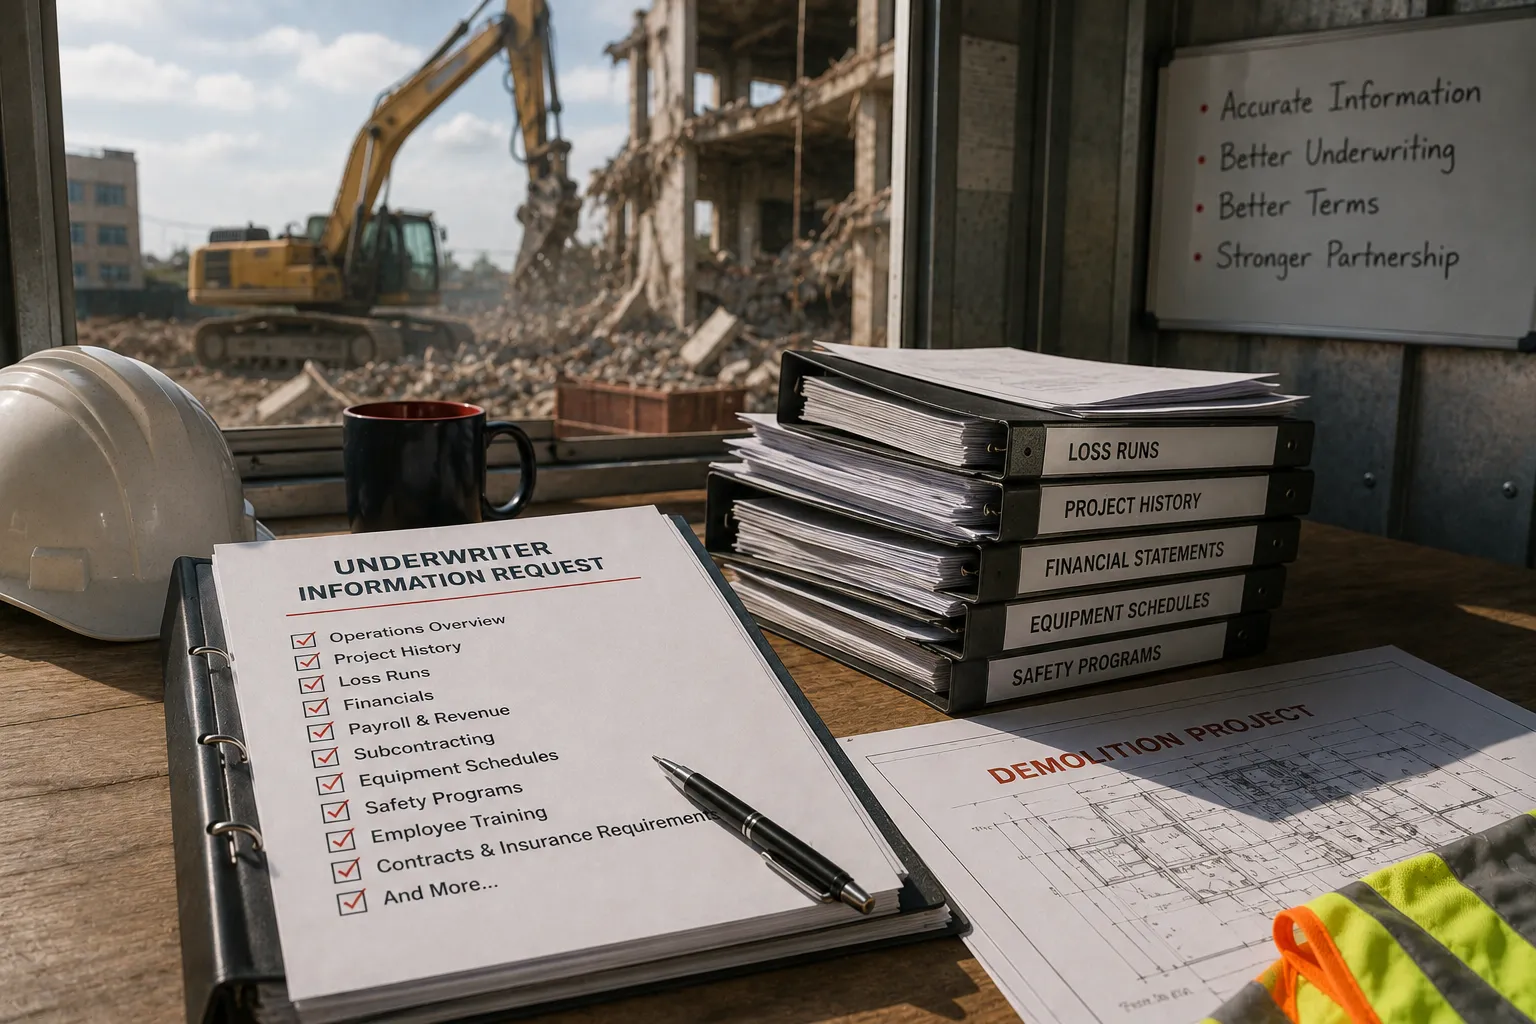
  • Currently valued loss runs
  • Explanations of larger losses
  • A completed supplemental application
  • ACORD applications
  • Subcontractor contracts
  • A detailed description of operations

Additional underwriting information may be requested depending on the business.

The lesson is simple:

The better the underwriter understands your company, the better positioned they are to evaluate the actual risk.
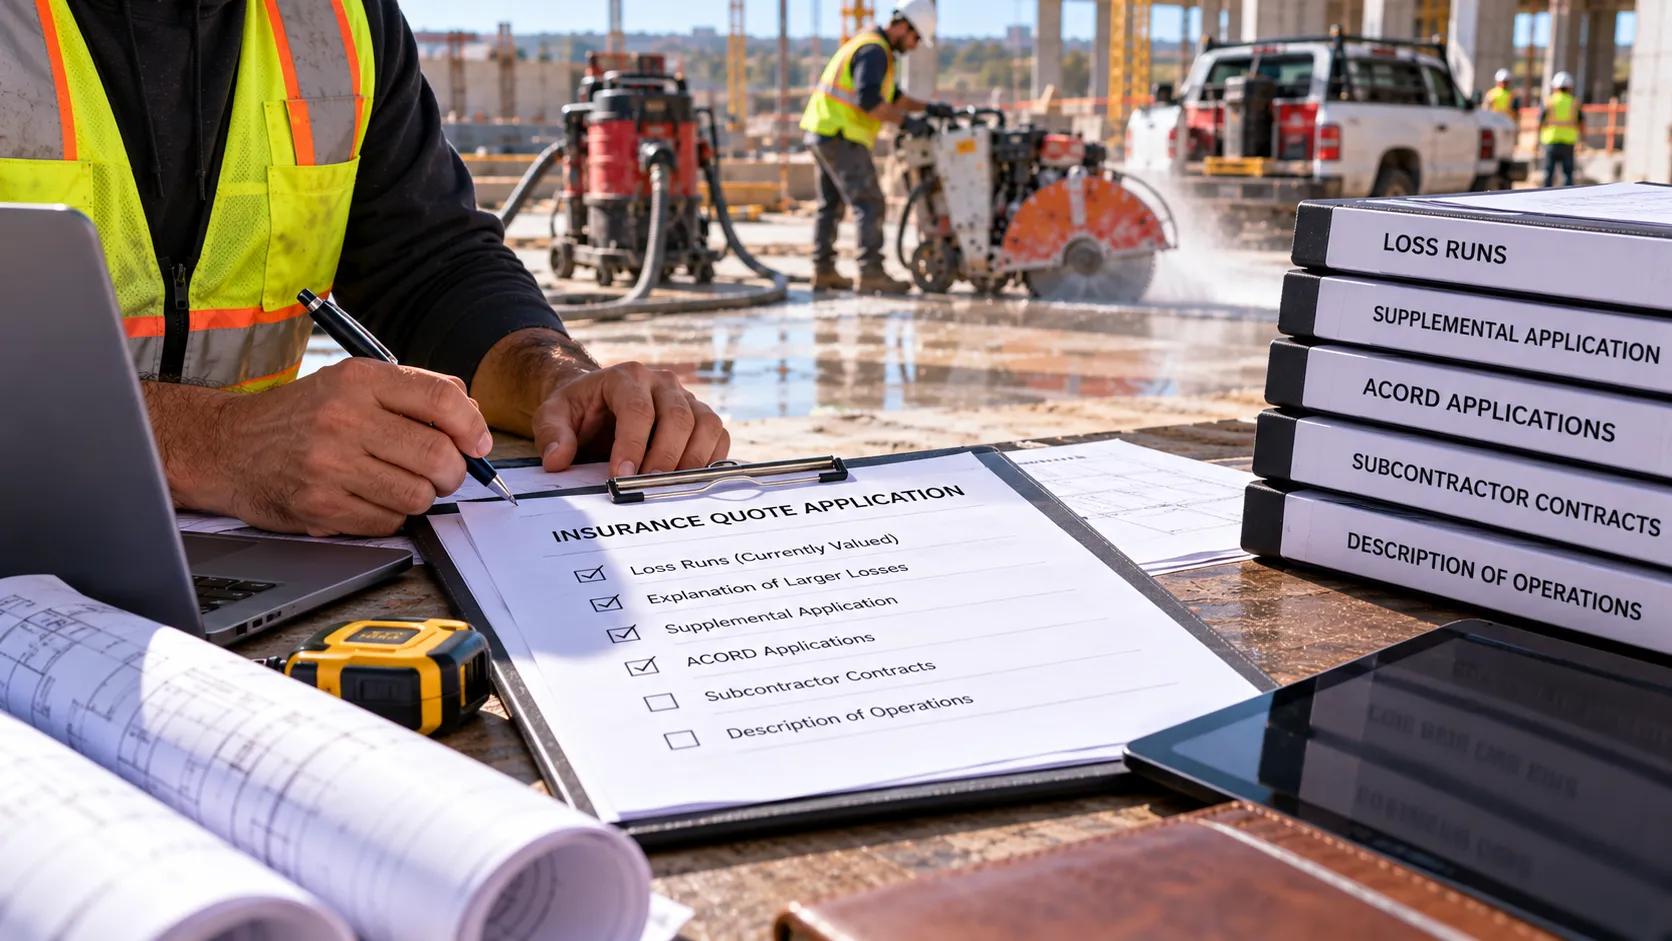
Concrete sawing contractor preparing an insurance quote application at a construction site, reviewing paperwork alongside loss runs, supplemental applications, ACORD forms, subcontractor contracts, and a detailed operations checklist, with concrete-cutting equipment and workers visible in the background.

Describe Your Operations Accurately

This deserves its own section.

Don’t try to make your business sound less complicated than it is.

If you perform:

Core drilling.

Wall sawing.

Wire sawing.

Selective demolition.

Ground-penetrating radar.

Grinding.

Other specialty operations.

Say so.

Insurance is designed around disclosed operations.

An insurance application isn’t the place for vague marketing language.

It’s the place for accuracy.

How Much Does Concrete Sawing and Drilling Contractor Insurance Cost?

There isn’t one responsible price that applies to every concrete cutting contractor.

Premium can depend on factors such as:

  • Annual revenue
  • Payroll
  • Type of work
  • Years in business
  • Geographic territory
  • Loss history
  • Subcontracting
  • Project size
  • Coverage limits
  • Vehicles
  • Equipment
  • Pollution exposure
  • Safety practices
  • Contract requirements

Two companies performing “concrete cutting” could receive very different insurance pricing because their actual operations are different.

Don’t Shop on Premium Alone

Price matters.

Every contractor needs to control expenses.

But the cheapest policy isn’t necessarily the best value.

Consider what happens if a low-cost policy doesn’t fit your operations.

Or doesn’t satisfy a major customer’s contract.

Or excludes an exposure you assumed was covered.

The better question isn’t:

“What’s the cheapest concrete cutting insurance?”

It’s:

“What coverage does my business actually need, and what’s the most competitive way to insure it correctly?”

Why Work With a Specialist in Concrete Sawing and Drilling Insurance?

Specialty trades benefit from insurance professionals who understand the terminology.

You shouldn’t have to spend half the conversation explaining the difference between:

Slab sawing.

Core drilling.

Wall sawing.

Wire sawing.

And ordinary concrete construction.

An insurance professional familiar with the trade can ask better questions about:

  • Operations
  • Contracts
  • Equipment
  • Subcontracting
  • Job types
  • Loss history
  • Pollution exposures
  • Required limits

Better questions lead to a clearer understanding of the risk.
An insurance professional and concrete sawing contractor review project documents and blueprints at an active construction site, with workers operating concrete saws and a wall-mounted core drilling rig in the background, illustrating the value of specialized insurance expertise for concrete cutting and drilling businesses.

Apollo General Insurance and Concrete Sawing & Drilling Contractors

Apollo General Insurance specializes in commercial insurance programs for niche contractor industries, including concrete sawing and drilling.

Apollo’s current Concrete Sawing and Drilling Contractors Insurance program serves qualifying specialty trade contractors engaged in operations including concrete sawing, cutting, breaking, polishing, shaving, trenching, curing, and core drilling.

Depending on the contractor’s needs and eligibility, additional policies may also be available for:

  • Excess liability
  • Contractors pollution liability
  • Commercial automobile liability
  • Property and equipment
  • Surety bonds
  • Workers’ compensation

Coverage availability, eligibility, terms, conditions, exclusions, limits, and pricing depend on the individual risk and applicable policy.

Are You Reviewing Your Concrete Contractor Insurance?

Your business changes.

Maybe you’ve purchased new equipment.

Started doing larger projects.

Added employees.

Expanded into another state.

Started subcontracting more work.

Added wall sawing.

Started performing selective demolition.

Taken on different types of customers.

Your insurance program should be reviewed as your operations evolve.

A policy that fit the business three years ago may not accurately reflect what the company does today.

Conclusion

Concrete sawing and drilling contractors perform highly specialized work.

Their insurance should reflect that.

General liability may form the foundation of a contractor’s insurance program, but it may not be the only coverage worth considering.

Depending on the company, a complete insurance discussion may also include:

Workers’ compensation.

Contractors pollution liability.

Commercial auto.

Equipment coverage.

Excess liability.

Surety bonds.

Most importantly, insurance should be based on what the contractor actually does.

A slab-sawing company isn’t necessarily the same risk as a core drilling company.

A core drilling contractor isn’t necessarily the same as a company performing wall sawing, wire sawing, grinding, selective demolition, or other specialty operations.

That’s why the right insurance conversation begins with the work.

Understand the operation. Identify the exposures. Then build the insurance program around them.

Apollo General Insurance has decades of experience working with specialty contractor industries, including concrete sawing and drilling contractors.

If you’re reviewing your current coverage or preparing for an upcoming renewal, talk with Apollo General about your operations and the insurance options available for your business.
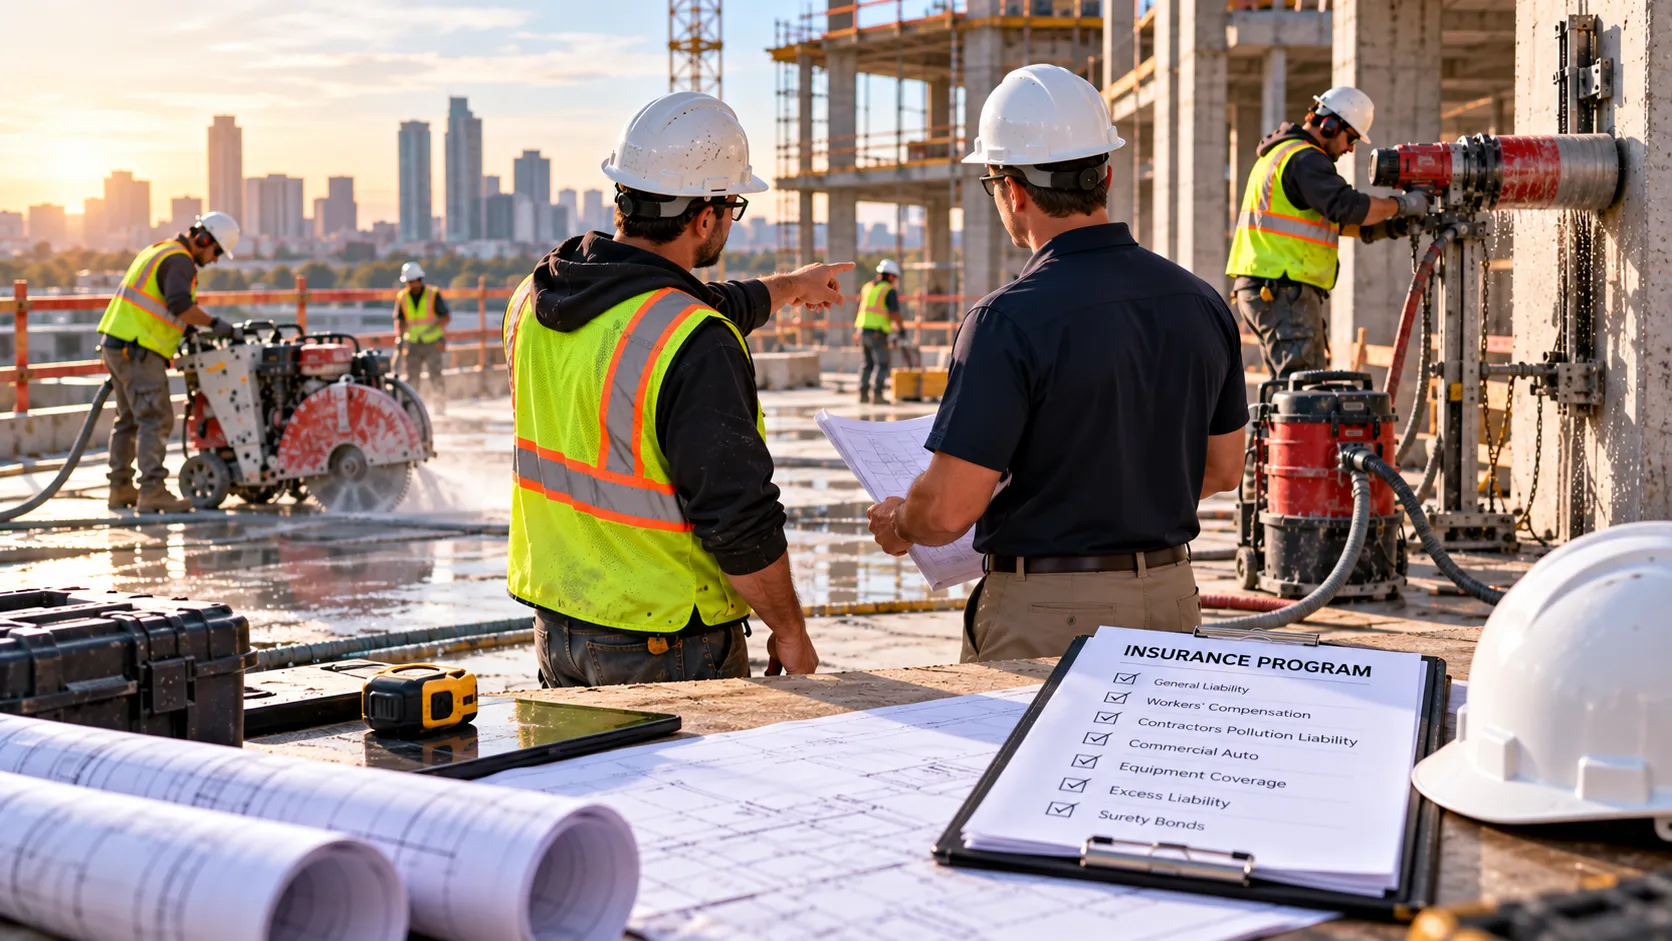
Concrete sawing contractor and insurance professional review project plans and an insurance coverage checklist at a large commercial construction site, while workers operate concrete saws and a wall-mounted core drilling rig in the background, illustrating the importance of tailoring insurance coverage to the specific risks of concrete cutting and drilling operations.

Frequently Asked Questions About Concrete Sawing and Drilling Contractor Insurance

1. What insurance does a concrete sawing and drilling contractor need?

Depending on the business, coverage may include general liability, workers’ compensation, contractors pollution liability, commercial auto, property and equipment coverage, excess liability, and surety bonds.

2. Do concrete cutting contractors need general liability insurance?

General liability is a foundational coverage for many concrete cutting businesses because their operations can create third-party bodily injury and property-damage exposures.

3. What insurance does a core drilling contractor need?

Core drilling contractors may need general liability, workers’ compensation, commercial auto, equipment coverage, pollution liability, excess liability, and bonds depending on their operations and contracts.

4. Does general liability cover concrete cutting equipment?

General liability generally addresses certain liability claims against the business rather than loss or damage to the contractor’s own equipment. Separate property or equipment coverage may be appropriate.

5. What insurance covers concrete saws and core drilling equipment?

Contractors may use property, inland marine, or contractor equipment coverage for eligible tools and mobile equipment, depending on the policy.

6. Do concrete contractors need pollution liability insurance?

Some concrete contractors should consider contractors pollution liability because their operations may involve dust, slurry, fuels, oils, waste, or other potential environmental exposures. General liability policies may contain pollution exclusions or limitations.

7. Does concrete slurry create an insurance exposure?

It can. Contractors should understand how their operations handle slurry and waste and discuss potential pollution exposures with an insurance professional.

8. Do concrete sawing contractors need workers’ compensation?

Workers’ compensation requirements vary by jurisdiction, but businesses with employees may be required to maintain coverage. Concrete sawing also presents significant employee injury and occupational exposures.

9. Do concrete cutting contractors need commercial auto insurance?

Businesses using vehicles for company operations should evaluate appropriate commercial auto coverage rather than assuming personal auto policies will cover business use.

10. What is completed operations coverage for a concrete contractor?

Completed operations generally relates to certain liability claims arising from work after the contractor has completed the job, subject to the policy’s terms and exclusions.

11. What is excess liability insurance for concrete contractors?

Excess liability can provide additional limits over certain underlying liability policies. Contractors may need higher limits because of project exposures or contractual requirements.

12. Do concrete cutting contractors need surety bonds?

Some projects require contractors to provide bid, performance, payment, or other surety bonds. Requirements depend on the project and contract.

13. Does subcontracting affect concrete contractor insurance?

It can. Underwriters may consider the percentage of subcontracted work, the type of work subcontracted, contractual risk transfer, and the insurance maintained by subcontractors.

14. Does loss history affect concrete cutting insurance rates?

Loss history can be an important underwriting factor. Insurers may evaluate the frequency, severity, causes, and circumstances of previous claims.

15. Does experience affect eligibility for concrete sawing insurance?

It can. Some specialty insurance programs have minimum operating-experience requirements or may request information about the experience of owners and key personnel.

16. What information do I need for a concrete cutting contractor insurance quote?

You may be asked for a detailed description of operations, payroll, revenue, loss runs, applications, subcontractor information, geographic territory, job history, and other underwriting information.

17. How much does concrete sawing and drilling insurance cost?

Pricing varies based on the contractor’s operations, revenue, payroll, experience, claims, location, subcontracting, equipment, vehicles, limits, and other underwriting factors.

18. Is concrete sawing insurance different from regular concrete contractor insurance?

It can be. Specialty sawing, cutting, drilling, grinding, and related operations create exposures that may differ from contractors primarily pouring or finishing concrete.

19. Does Apollo General insure concrete sawing and drilling contractors?

Apollo General offers a specialty Concrete Sawing and Drilling Contractors Insurance program for qualifying contractors. Eligibility and available coverage depend on the contractor’s operations and underwriting requirements.

20. How do I get a concrete sawing and drilling contractor insurance quote?

Be prepared to provide detailed information about your operations, experience, payroll, revenue, loss history, subcontracting, equipment, and project types. An insurance professional familiar with concrete sawing and drilling can then evaluate available coverage options.
How Much Does Demolition Contractor Insurance Cost?

How Much Does Demolition Contractor Insurance Cost?

Introduction

“How much does demolition contractor insurance cost?”

It’s one of the first questions a demolition contractor asks when shopping for coverage.

It’s also one of the hardest questions to answer without knowing anything about the company.

A contractor performing residential tear-downs on single-family homes presents a very different risk than a company demolishing large commercial structures.

A $2 million demolition contractor with experienced employees, few subcontractors, strong safety procedures, and a clean loss history may look very different to an underwriter than another $2 million contractor taking larger projects and experiencing repeated claims.

That’s why demolition insurance isn’t typically priced from a simple menu.

The premium is based on the risk.

At Apollo General Insurance Agency, demolition contractors are a specialty class of business. Understanding what actually drives insurance pricing can help contractors prepare better submissions, anticipate costs, and understand why one company may pay significantly more than another.

What You’ll Learn

  • Why there isn’t one standard price for demolition contractor insurance
  • What factors can affect demolition insurance premiums
  • How revenue and payroll influence pricing
  • Why your largest project matters
  • How claims can affect your insurance cost
  • Why subcontracting matters
  • How coverage limits and contract requirements affect premiums
  • What contractors can do to present their business more effectively to underwriters

There Is No Single Average Price for Demolition Insurance

If you search online for contractor insurance costs, you’ll find websites advertising surprisingly low monthly premiums.

Those numbers may be relevant to certain low-risk contracting businesses.

They should not automatically be applied to demolition.

Demolition presents specialized exposures involving structures, heavy equipment, neighboring properties, employees, subcontractors, underground utilities, debris, transportation, and potentially environmental hazards.

Pricing therefore requires an underwriter to understand the actual operation.

The more complex the risk, the more important those details become.

What Insurance Are We Talking About?

Another reason it’s difficult to answer “How much does demolition insurance cost?” is that demolition contractors may need several types of insurance.

An insurance program could potentially include:

  • Commercial General Liability
  • Workers’ Compensation
  • Commercial Auto
  • Contractors Equipment
  • Contractors Pollution Liability
  • Umbrella or Excess Liability
  • Other project-specific or operational coverage

Each is priced differently.

A contractor asking about the cost of General Liability insurance is asking a different question from someone trying to determine the cost of their entire insurance program.

For this article, we’re primarily discussing the factors that can affect the cost of insuring a demolition operation overall.

Two construction professionals wearing hard hats and high-visibility safety vests review demolition plans at an active demolition site, with excavators dismantling a concrete building and rubble in the foreground.

1. Your Annual Revenue

Revenue is one of the basic measurements insurers may use to understand the size of a contracting business.

Generally, a company generating $500,000 per year represents a different level of exposure than one generating $20 million.

More revenue often means:

  • More projects
  • Larger projects
  • More customers
  • More jobsite activity
  • More employees or subcontractors
  • Greater overall exposure

But revenue doesn’t tell the entire story.

Two contractors with exactly the same annual sales can still receive very different insurance pricing.

Why?

Because what generates that revenue matters.

Two demolition contractors review project documents and business figures at a construction site, with an excavator, a partially demolished building, and construction debris in the background.

2. The Type of Demolition You Perform

This can be one of the most important considerations.

“Demolition contractor” can describe very different businesses.

You might specialize in:

  • Residential tear-downs
  • Commercial tear-downs
  • Interior strip-outs
  • Selective demolition
  • Structural demolition
  • Industrial demolition
  • Concrete removal
  • Other specialized demolition operations

The potential severity and complexity of a loss can differ dramatically between these activities.

An interior demolition contractor removing nonstructural materials inside relatively small buildings may be evaluated differently from a company bringing down large structures close to neighboring properties.

The more accurately you describe your work, the more accurately the underwriter can evaluate it.

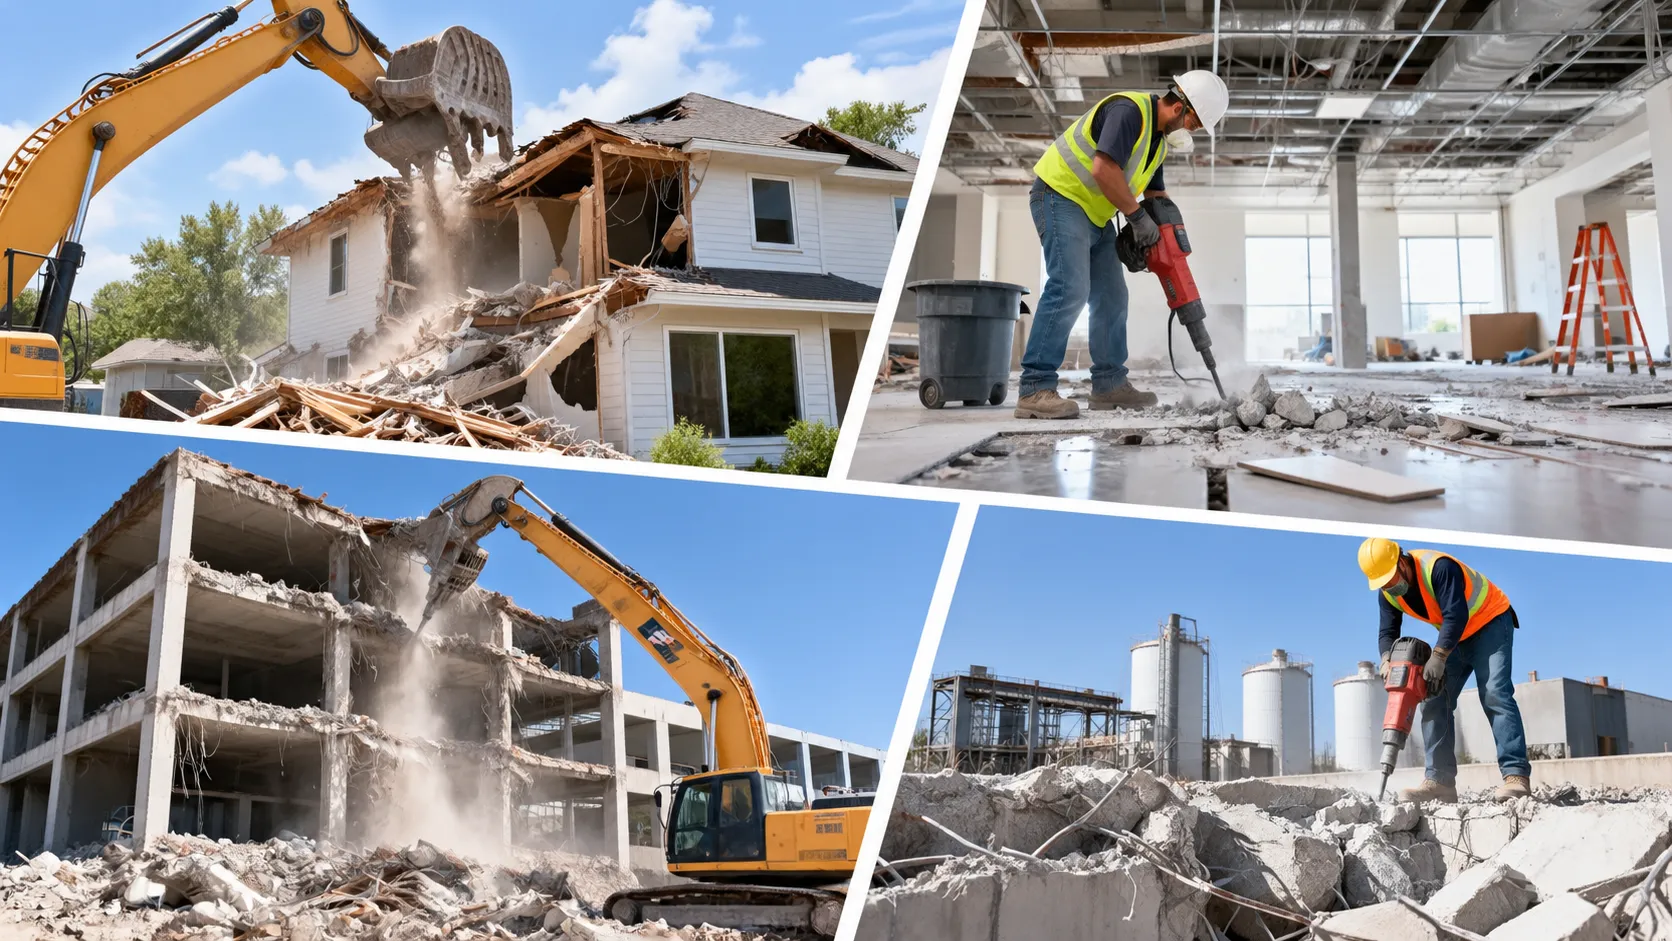
A four-panel collage showing different demolition operations, including residential home teardown, interior commercial demolition, structural demolition of a multistory concrete building, and concrete removal at an industrial site.

3. Your Largest Project

Annual revenue tells the insurer how much work you perform.

Your largest project helps reveal how much exposure might be concentrated in one place.

Consider two companies.

Contractor A

Annual revenue: $5 million

Largest project: $250,000

Contractor B

Annual revenue: $5 million

Largest project: $2.5 million

Their annual sales are identical.

Their risk profiles may not be.

A large project may involve:

  • Larger structures
  • Longer project durations
  • More employees
  • More equipment
  • More subcontractors
  • Higher property values
  • More complex contracts

That’s why underwriters may ask about both the largest project you’ve completed and the largest project you expect to undertake during the policy period.

Two demolition site managers wearing hard hats and high-visibility vests review blueprints while surveying a large multistory concrete building being demolished by excavators, with construction workers and rubble illustrating the scale and complexity of the project.

4. Building Height and Structural Complexity

Taking down a single-story house isn’t the same as demolishing a multistory commercial structure.

Underwriters may want to understand:

  • Maximum building height
  • Number of stories
  • Type of construction
  • Structural characteristics
  • Distance to neighboring buildings
  • Project location
  • Demolition methods

As structures become larger and more complex, the potential consequences of something going wrong may increase.

That can affect both eligibility and price.

Two construction professionals wearing hard hats and high-visibility safety vests inspect a multistory concrete building undergoing demolition, while excavators dismantle the structure amid falling debris, exposed rebar, and surrounding urban buildings.

5. Your Payroll

Payroll can be an important rating factor, particularly for Workers’ Compensation insurance.

Demolition involves employees working around:

  • Heavy equipment
  • Falling debris
  • Tools
  • Elevated areas
  • Uneven surfaces
  • Dust
  • Noise
  • Structural hazards

The number of employees, their job classifications, payroll, experience, and work activities can all influence the insurance picture.

A growing workforce may therefore increase insurance costs even if revenue remains relatively stable.

A demolition supervisor reviews construction plans with four workers wearing hard hats and high-visibility safety vests at an active demolition site, with an excavator, dump truck, and concrete rubble in the background.

6. How Much Work You Subcontract

Subcontracting can significantly affect underwriting.

An insurance company may want to know:

What percentage of your work is performed by subcontractors?

But that’s only the beginning.

It may also ask:

  • What operations are subcontracted?
  • How are subcontractors selected?
  • Are written contracts required?
  • What insurance limits must they carry?
  • Do you obtain certificates of insurance?
  • Are additional insured endorsements required?
  • Do subcontractors ever subcontract their work again?

A demolition contractor with strong subcontractor controls can present a very different risk from one that hires companies informally without consistent insurance requirements.

Five demolition contractors wearing hard hats and high-visibility safety vests review blueprints and discuss project plans at an active demolition site, with excavators, construction debris, and other workers in the background.

7. Your Loss History

Your claims history can have a significant impact on both availability and cost.

Underwriters may review several years of loss runs to understand:

  • Number of claims
  • Types of claims
  • Severity
  • Frequency
  • Whether losses follow a pattern

One large claim doesn’t automatically make a contractor a bad risk.

Likewise, a series of smaller claims shouldn’t automatically be dismissed simply because none was catastrophic.

Underwriters are often looking for patterns.

Repeated incidents involving similar causes may suggest a problem with procedures, training, supervision, equipment, or another aspect of the operation.

What If You’ve Had a Large Claim?

Explain it.

Don’t simply submit a loss run showing a significant claim and hope the underwriter ignores it.

Provide context.

Explain:

What happened?

What caused it?

What did the company learn?

What changed afterward?

Perhaps you changed a procedure.

Added training.

Changed equipment.

Hired a safety manager.

Increased supervision.

Modified subcontractor requirements.

An underwriter cannot give you credit for improvements they don’t know about.

Demolition contractors wearing hard hats and high-visibility safety vests participate in a jobsite safety briefing, reviewing safety procedures, protective equipment requirements, and hazard prevention practices to reduce workplace risks.

8. Your Safety Program

Insurance companies aren’t only interested in what has gone wrong.

They’re interested in what you’re doing to prevent future losses.

A demolition contractor may be asked about:

  • Written safety programs
  • Employee training
  • Toolbox talks
  • Personal protective equipment
  • Jobsite inspections
  • Supervisor responsibilities
  • Incident reporting
  • Equipment procedures
  • OSHA-related practices

A strong safety culture doesn’t guarantee lower premiums.

But weak safety controls can certainly make a demolition risk less attractive.

Demonstrating that safety is integrated into daily operations can help an underwriter better understand the quality of the company.

A demolition site supervisor leads a safety briefing with construction workers, reviewing personal protective equipment, jobsite hazards, and safety checklists beside an active demolition site with an excavator and construction debris in the background.

9. Employee and Management Experience

Experience matters in specialized contracting.

A newer company led by people with decades of demolition experience may present differently from a new company whose management has limited experience in the industry.

Underwriters may want to know:

  • How long the company has operated
  • How long the owners have worked in demolition
  • Experience of key managers
  • Experience of supervisors
  • Employee training
  • Relevant certifications

This becomes particularly important for newer businesses without a long company loss history.

Management résumés can help demonstrate the experience behind the operation.

An experienced demolition supervisor reviews blueprints with three construction workers wearing hard hats and high-visibility safety vests at an active demolition site, demonstrating management experience, team guidance, and technical expertise amid excavators and concrete rubble.

10. Your Equipment

Demolition contractors can own substantial amounts of expensive equipment.

Depending on the company, that might include:

  • Excavators
  • Skid steers
  • Loaders
  • Breakers
  • Crushers
  • Attachments
  • Generators
  • Specialized tools

Contractors Equipment or Inland Marine insurance may be used to protect qualifying equipment against covered losses.

The more equipment you own—and the higher its value—the more it can contribute to the overall cost of your insurance program.

Where equipment is stored, transported, and used may also matter.

A demolition contractor inspects heavy equipment and specialized attachments, including excavator buckets and hydraulic breakers, at an equipment yard with excavators, a generator trailer, and a partially demolished building in the background.

11. Your Commercial Vehicles

Dump trucks, pickups, trailers, service vehicles, and other commercial vehicles add another insurance component.

Commercial Auto pricing can be influenced by factors such as:

  • Number of vehicles
  • Types of vehicles
  • Vehicle values
  • Drivers
  • Driving records
  • Radius of operation
  • Claims history
  • Vehicle use

A demolition contractor with two pickup trucks presents a very different commercial auto exposure from one operating a substantial fleet of heavy vehicles.

A fleet of commercial vehicles, including a heavy-duty dump truck, pickup trucks, service vehicles, and trailers, parked at an active demolition site while two construction workers discuss vehicle operations, with excavators and a partially demolished building in the background.

12. Pollution Exposure

Demolition can involve environmental concerns that aren’t present in many other contracting operations.

Older buildings may contain materials requiring specialized handling.

Projects can also involve:

  • Dust
  • Debris
  • Fuel
  • Chemicals
  • Existing contamination
  • Other environmental exposures

Depending on the operations, Contractors Pollution Liability may be appropriate or required.

Adding specialized coverage increases the overall cost of the insurance program, but excluding a significant exposure simply to reduce premium can create a much more expensive problem later.

Demolition workers wearing protective coveralls, respirators, and safety vests handle construction debris and suppress dust with water at an environmental cleanup site, with chemical storage containers, an excavator, and a partially demolished concrete building in the background.

13. XC&U Exposure

Demolition contractors should understand how their liability policy addresses:

Explosion

Collapse

Underground

These exposures are commonly referred to as XC&U.

Collapse is particularly relevant to demolition, while underground work can create exposures involving utilities and other buried property.

A project’s insurance requirements may specify how these exposures must be addressed.

Policies and underwriting appetites vary, so contractors should review their actual operations and contract requirements rather than assuming every General Liability policy handles XC&U the same way.

Two demolition site inspectors wearing hard hats and high-visibility safety vests review construction plans beside an open trench containing exposed underground utility pipes, while excavators dismantle a multistory concrete building in the background, illustrating structural collapse and underground utility exposures.

14. Your Coverage Limits

Higher insurance limits generally mean more potential exposure for the insurer.

A contractor purchasing $1 million in liability coverage is asking the insurance market for a different level of protection than one needing substantially higher limits.

Demolition contracts may require:

  • Specific General Liability limits
  • Commercial Auto limits
  • Umbrella or Excess Liability
  • Pollution Liability
  • Other project-specific limits

Larger projects may come with larger insurance requirements.

That can increase the contractor’s insurance cost.

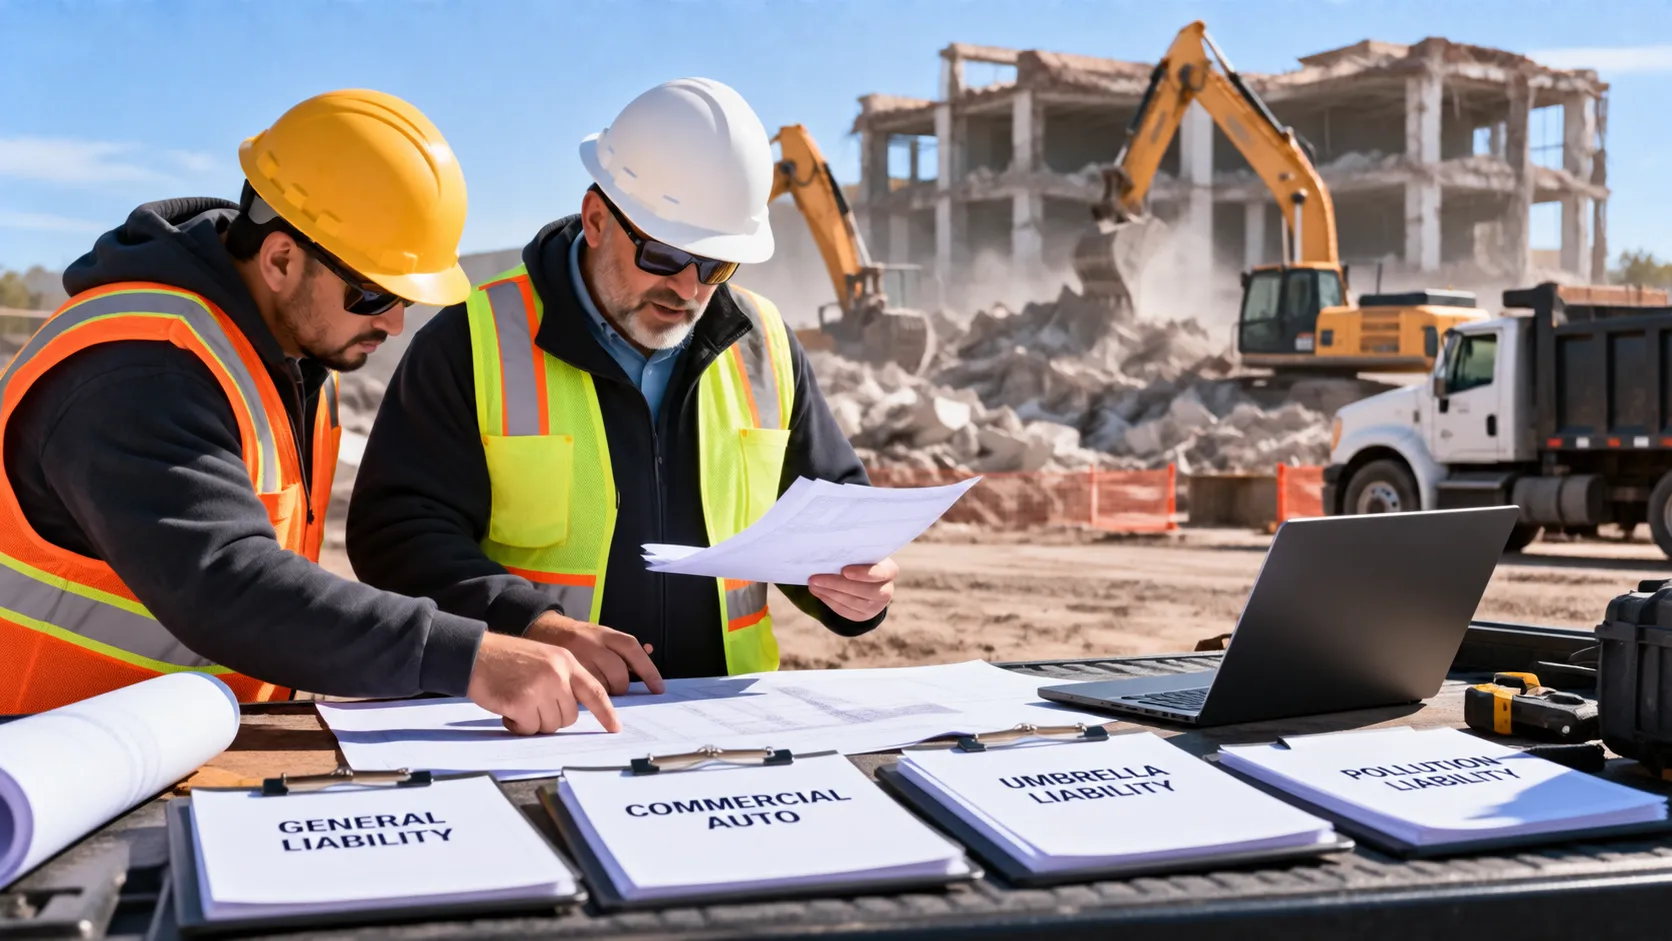
Two demolition contractors wearing hard hats and high-visibility safety vests review project plans and insurance documents at a jobsite table, with paperwork for general liability, commercial auto, umbrella liability, and pollution liability coverage, while excavators, a dump truck, and a partially demolished building appear in the background.

15. Contract Requirements

Sometimes the contractor isn’t choosing additional insurance.

The customer is requiring it.

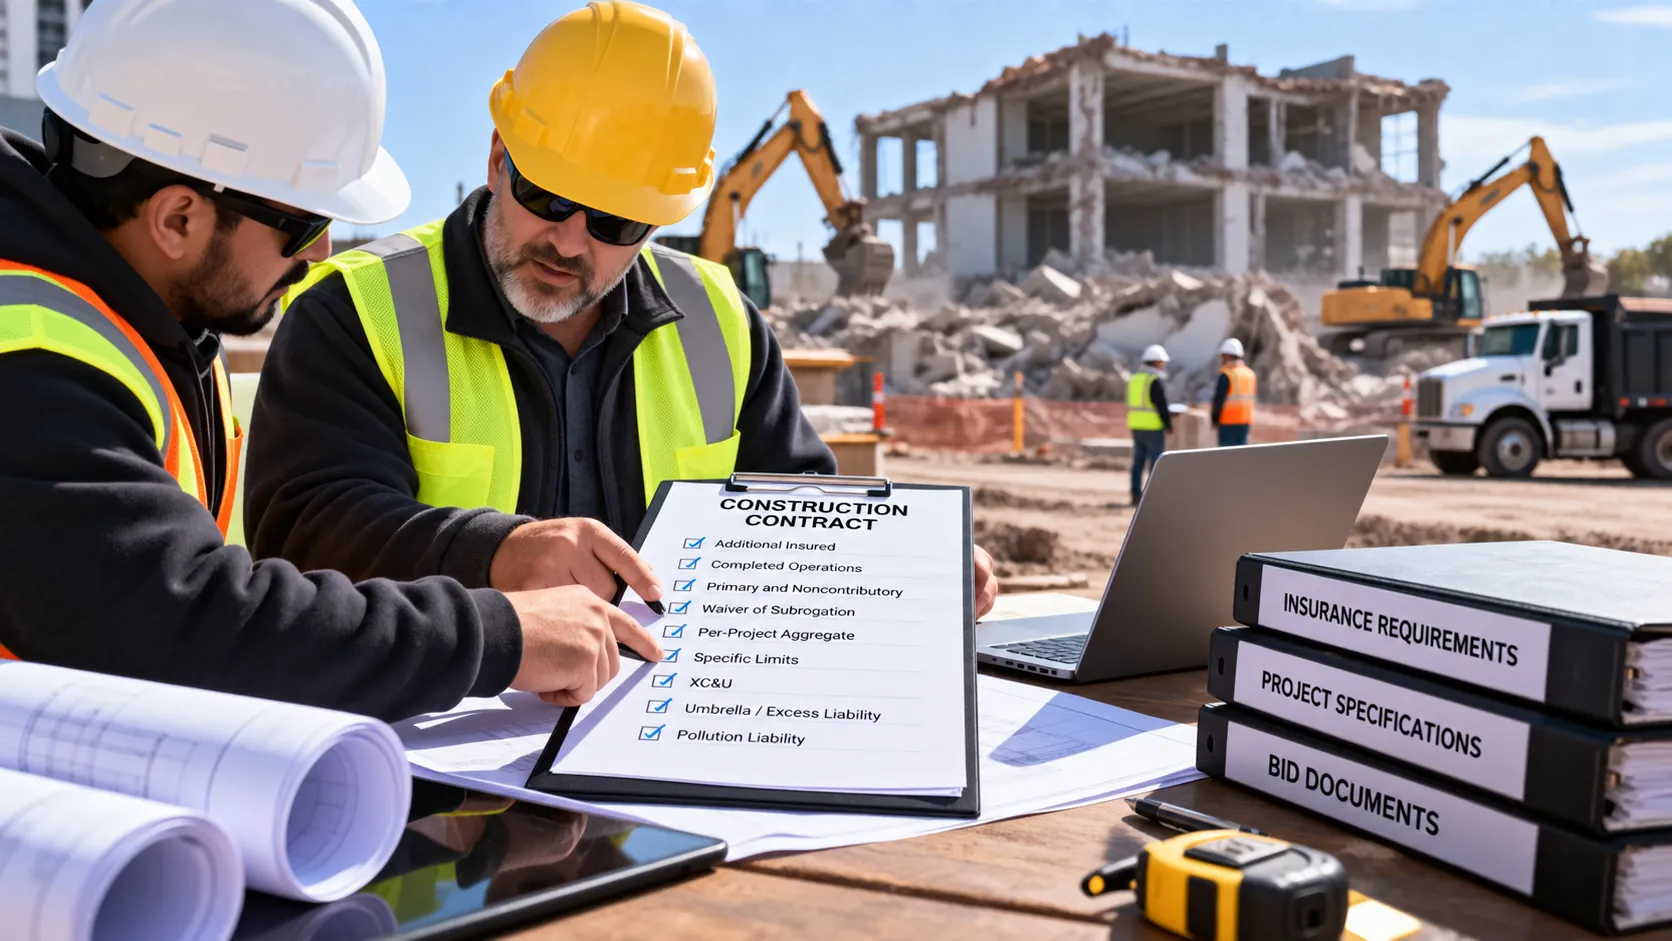
A construction contract may require provisions involving:

  • Additional Insured status
  • Completed Operations
  • Primary and Noncontributory wording
  • Waiver of Subrogation
  • Per-Project Aggregate
  • Specific limits
  • XC&U
  • Umbrella or Excess Liability
  • Pollution Liability

Those requirements can affect which insurance markets are available and what the final program costs.

This is why insurance requirements should be reviewed before bidding the job.

Don’t Discover the Insurance Cost After You Win the Project

Imagine bidding a large demolition project with a 10% profit margin.

You win.

Then you send the contract to your insurance broker.

The project requires insurance your current program doesn’t provide.

Obtaining it adds a significant unexpected cost.

That cost comes directly out of the project’s profitability unless you accounted for it in the bid.

Insurance isn’t just an administrative requirement.

It can be a project cost.

Treat it like one.

Two demolition contractors wearing hard hats and high-visibility safety vests review a construction contract and insurance requirements checklist at an on-site table, with project specifications, bid documents, blueprints, and a laptop, while excavators and a partially demolished concrete building are visible in the background.

16. Where You Work

Geography can affect insurance pricing too.

Demolition contractors may work:

  • Locally
  • Throughout a state
  • Across several states
  • Nationwide

Different jurisdictions can present different legal environments, Workers’ Compensation systems, contractual requirements, and underwriting concerns.

Tell the underwriter where you actually perform work and where you expect to operate during the policy period.

Two demolition contractors wearing hard hats and high-visibility safety vests review a map of the United States marked with project locations, with an active demolition site, excavators, dump trucks, a bridge, and a city skyline in the background, illustrating how a contractor's geographic operating area can affect insurance underwriting.

17. Your Financial Condition

For larger or more complex demolition accounts, underwriters may request financial statements.

Why would an insurance company care about your finances?

Because financial stability can say something about the overall health of the operation.

An underwriter may want to understand whether the company has sufficient financial resources to:

  • Maintain equipment
  • Hire qualified employees
  • Manage projects
  • Invest in safety
  • Absorb deductibles
  • Operate consistently

Financial strength isn’t the only consideration, but it can be part of the overall underwriting picture.

Two demolition company managers wearing hard hats and high-visibility safety vests review financial statements, business charts, and project documents at a jobsite table, with an excavator, dump truck, construction workers, and a partially demolished concrete building in the background.

Why Two Demolition Contractors Can Receive Very Different Quotes

Let’s compare two hypothetical companies.

Demolition Company A

  • $3 million annual revenue
  • Primarily residential tear-downs
  • Maximum project of $250,000
  • Experienced management
  • Minimal subcontracting
  • Clean recent loss history
  • Documented safety program

Demolition Company B

  • $3 million annual revenue
  • Large commercial structural demolition
  • Maximum project of $1.5 million
  • Significant subcontracting
  • Multiple recent losses
  • Limited safety documentation

Same revenue.

Completely different insurance profile.

That’s why asking another demolition contractor:

“What do you pay for insurance?”

may not tell you very much.

Their business isn’t your business.

What Is a Minimum Premium?

Specialty insurance programs may have a minimum premium.

That means the insurance carrier has established a minimum amount it is willing to charge for providing coverage within that program, even when a smaller account’s rating exposure might otherwise produce a lower calculated premium.

Minimum premiums vary by program, carrier, coverage, and underwriting circumstances.

This can be particularly relevant to smaller demolition contractors comparing specialty insurance with more general contractor programs.

Can You Lower the Cost of Demolition Contractor Insurance?

There is no magic checklist guaranteed to reduce your premium.

But there are things you can do to present a stronger risk.

Provide Complete Information

Incomplete applications create uncertainty.

Give underwriters the information they need.

Explain Your Claims

Don’t leave significant losses unexplained.

Show what happened and what changed.

Maintain Strong Safety Procedures

Document what you’re actually doing.

Manage Subcontractors

Use consistent contracts and insurance requirements.

Maintain Your Equipment

Document maintenance and inspection procedures where appropriate.

Review Projects Before Bidding

Understand whether a new project introduces insurance requirements outside your existing program.

Build a Long-Term Insurance Strategy

Don’t wait until renewal week to start thinking about your insurance.

Two demolition contractors wearing hard hats and high-visibility safety vests review insurance documents and a risk management checklist at a jobsite table, with paperwork covering safety procedures, subcontractor management, equipment maintenance, project reviews, and insurance planning, while excavators and a partially demolished building appear in the background.

The Cheapest Demolition Insurance May Not Be the Least Expensive

Price matters.

Every contractor needs to control overhead.

But insurance is one area where simply choosing the lowest premium can create unintended consequences.

Imagine saving money on insurance only to discover:

  • Your largest projects exceed underwriting limitations
  • A contract requires an endorsement you can’t obtain
  • A significant operation wasn’t properly contemplated
  • Your equipment limits are inadequate
  • A project requires higher limits
  • A relevant exclusion creates a coverage concern

A lower premium isn’t a bargain if the policy doesn’t match the business.

How to Prepare for a Demolition Insurance Quote

Before requesting pricing, gather information such as:

  • Annual revenue
  • Payroll
  • Subcontracting costs
  • Description of operations
  • Project history
  • Largest completed project
  • Largest anticipated project
  • Building heights
  • Geographic territory
  • Current insurance
  • Loss runs
  • Claims explanations
  • Equipment schedule
  • Vehicle information
  • Safety programs
  • Management experience
  • Sample contracts

The goal is to give the underwriter a clear picture of the company.

Better information can lead to a more productive underwriting process.

Why Work With a Demolition Insurance Specialist?

Demolition is not a generic contractor class.

A specialty insurance professional understands why the underwriter is asking about:

  • Structural demolition
  • Maximum building height
  • Excavation
  • XC&U
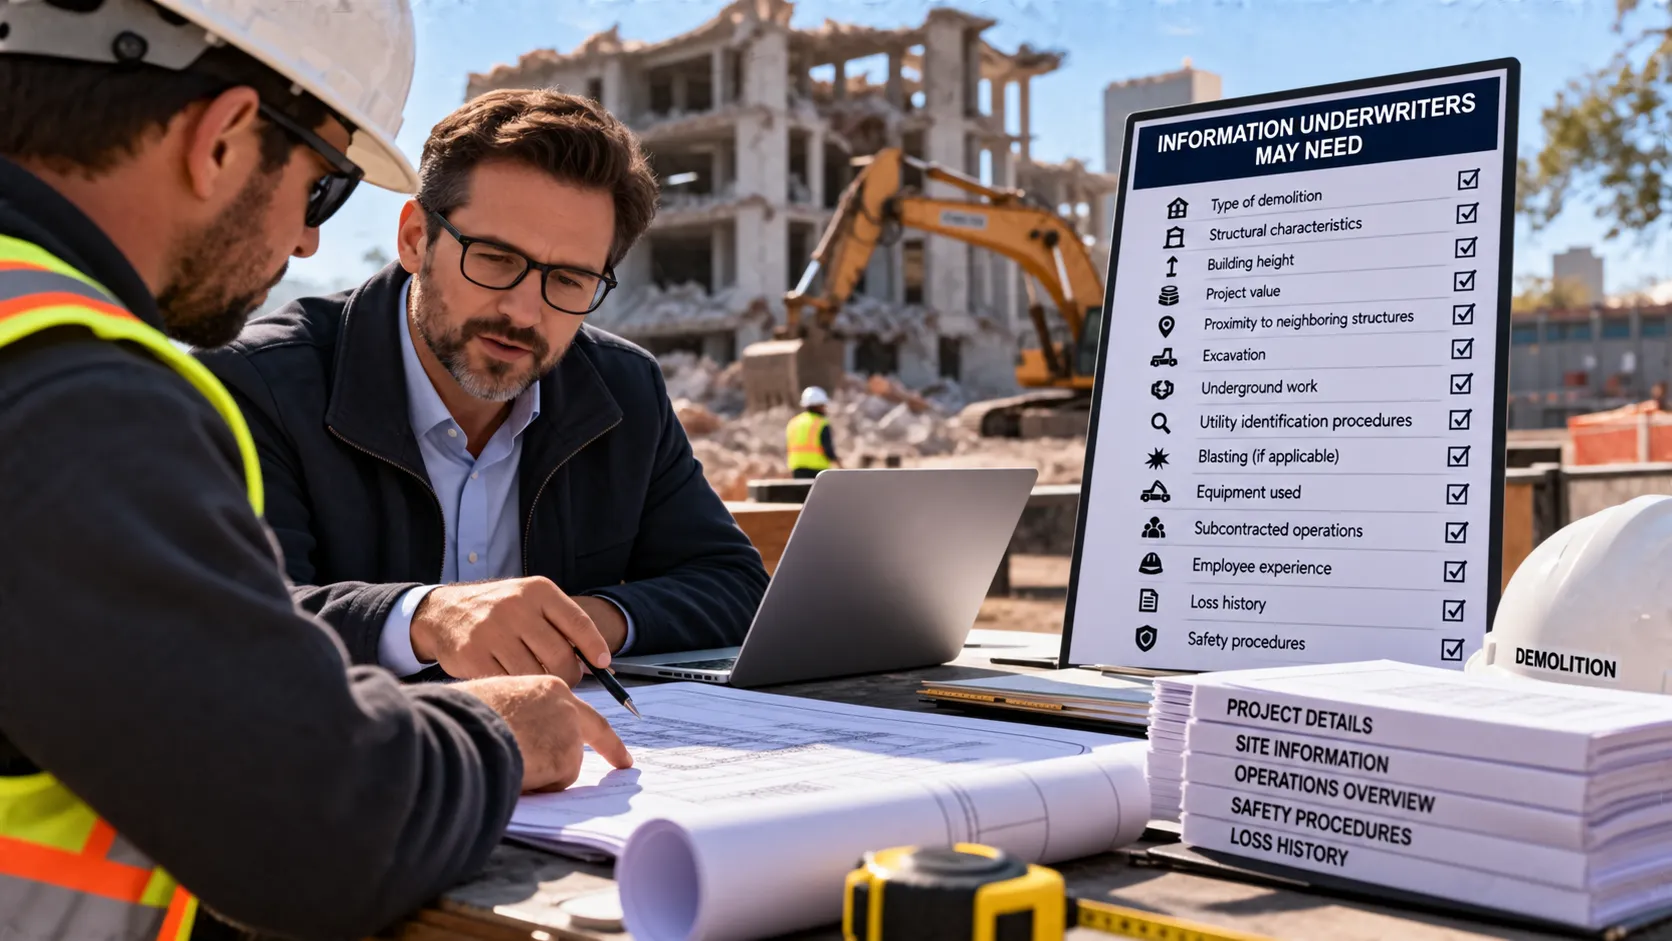
  • Subcontracting
  • Neighboring structures
  • Equipment
  • Pollution
  • Safety procedures
  • Largest projects

That can make an important difference when presenting the account.

Apollo General Insurance Agency has decades of experience in specialty commercial insurance and offers dedicated programs for eligible demolition contractors.

Get a Demolition Contractor Insurance Quote

So how much will your demolition contractor insurance cost?

The answer requires understanding your business.

Apollo General Insurance Agency works with insurance professionals and eligible demolition contractors to evaluate specialized demolition risks, including residential tear-downs, commercial demolition, and interior strip-outs.

The underwriting process considers the actual operations rather than treating every demolition company as identical.

Learn more about Apollo General Insurance Agency’s demolition contractor insurance program.

Conclusion

There isn’t one useful average price for demolition contractor insurance.

The cost depends on the company behind the policy.

Your revenue matters.

Your payroll matters.

Your projects matter.

Your claims matter.

Your employees matter.

Your subcontractors matter.

Your equipment matters.

Your safety procedures matter.

And the contracts you’re trying to win matter.

Instead of asking only:

“How much does demolition insurance cost?”

Ask:

“What does an underwriter need to understand about our company to price our risk accurately?”

That’s a much better place to start.

Three demolition company managers wearing hard hats and high-visibility safety vests review blueprints and a demolition insurance checklist at a jobsite table, with documents covering revenue, payroll, claims history, subcontractors, equipment, safety procedures, and contract requirements, while excavators, dump trucks, and a partially demolished concrete building appear in the background.

Frequently Asked Questions About Demolition Contractor Insurance Costs

1. How much does demolition contractor insurance cost?

There is no single price. Premiums depend on operations, revenue, payroll, project size, claims, subcontracting, equipment, vehicles, coverage limits, geographic territory, and other underwriting factors.

2. Why is demolition insurance more specialized than ordinary contractor insurance?

Demolition can involve structural collapse, heavy equipment, neighboring properties, underground utilities, employees, subcontractors, and other specialized exposures.

3. Does annual revenue affect demolition insurance premiums?

Yes. Revenue may be one of the measurements used to evaluate the size and exposure of the business.

4. Does payroll affect demolition insurance costs?

Yes, particularly for Workers’ Compensation and potentially other coverage depending on the rating structure.

5. Does the size of my largest demolition project matter?

Yes. Underwriters may evaluate your largest completed and anticipated projects to understand potential exposure severity.

6. Does building height affect demolition insurance?

It can. Building height and structural complexity may affect eligibility and underwriting.

7. Does residential demolition cost less to insure than commercial demolition?

Not necessarily. The actual premium depends on the complete risk, although the type and complexity of demolition are important underwriting considerations.

8. Does subcontracting increase demolition insurance costs?

It can affect pricing and eligibility depending on how much work is subcontracted, which operations are subcontracted, and how subcontractors are managed.

9. Will previous claims increase my premium?

They can. Underwriters may consider claim frequency, severity, cause, and corrective actions.

10. Can one large insurance claim make my company uninsurable?

Not necessarily. The circumstances of the loss and steps taken afterward can be important.

11. Does having a safety program reduce demolition insurance premiums?

A strong safety program does not guarantee a lower premium, but safety practices can be an important underwriting consideration.

12. Does demolition equipment need separate insurance?

Contractors Equipment or Inland Marine coverage may be appropriate for qualifying equipment depending on the business and policy.

13. Does Commercial Auto increase the total cost of my insurance program?

Commercial vehicles represent a separate exposure and can add significantly to the total insurance cost depending on the fleet.

14. Do demolition contractors need pollution liability?

Some demolition operations have pollution exposures that may warrant specialized coverage. Requirements depend on the work and contracts involved.

15. Does XC&U coverage affect insurance cost?

Coverage addressing explosion, collapse, and underground exposures can affect underwriting, eligibility, and pricing depending on the operation and policy.

16. Do higher liability limits cost more?

Generally, purchasing higher limits can increase premium, although pricing depends on the insurance program.

17. Can a project’s insurance requirements increase my costs?

Yes. Additional limits, endorsements, pollution coverage, umbrella coverage, or other requirements may increase insurance costs.

18. What is a minimum premium?

A minimum premium is the lowest premium an insurer or program is willing to charge for providing a particular coverage, regardless of whether exposure-based calculations would otherwise produce a lower amount.

19. What information do I need to get a demolition insurance quote?

Be prepared to provide detailed information about revenue, payroll, operations, projects, subcontractors, claims, safety, equipment, vehicles, management experience, and current insurance.

20. Does Apollo General Insurance Agency offer demolition contractor insurance?

Yes. Apollo General Insurance Agency offers specialty insurance programs for eligible demolition contractors, including certain residential tear-down, commercial demolition, and interior strip-out operations.

What Is XC&U Coverage—and Why Does It Matter for Demolition Contractors

What Is XC&U Coverage—and Why Does It Matter for Demolition Contractors?

Introduction

Demolition contractors encounter insurance terminology that most business owners will never need to understand.

One of those terms is XC&U.

You may see it on an insurance application.

It may appear in a construction contract.

A general contractor may ask whether your policy includes it.

Or your insurance broker may mention an XC&U exclusion while reviewing your general liability coverage.

But what does XC&U actually mean?

XC&U stands for Explosion, Collapse, and Underground.

Those three categories represent liability exposures that can be particularly important for contractors performing demolition, excavation, structural work, and other operations capable of affecting surrounding property.

For a demolition contractor, simply having a Commercial General Liability policy isn’t enough information.

You need to understand whether that policy contains exclusions or limitations that could affect the work you’re actually performing.

Here’s what demolition contractors should know.

What You’ll Learn

  • What XC&U means
  • What the “X,” “C,” and “U” represent
  • Why these exposures matter in demolition
  • How an XC&U exclusion can affect a contractor
  • Why contracts may require XC&U coverage
  • What to review before bidding a demolition project
  • Why your actual operations matter when obtaining insurance

What You'll Learn XC&U

What Does XC&U Stand For?

XC&U refers to three categories of contracting exposures:

X — Explosion

C — Collapse

U — Underground

Historically, insurers have treated these exposures carefully because a single incident can potentially result in significant property damage or bodily injury.

That makes them particularly relevant to construction and demolition.

Let’s look at each one separately.

X: Explosion

The “X” in XC&U refers to explosion hazards.

When people hear “explosion” in demolition, they often immediately think about imploding a large building with explosives.

That is certainly an obvious example.

But insurance language can be more complicated than the everyday meaning of a word.

The exact definition of an explosion hazard and how it applies depends on the insurance policy.

For contractors whose operations involve blasting or other explosive hazards, this can become a significant underwriting issue.

Does Every Demolition Insurance Policy Cover Blasting?

No.

Blasting can fall outside the underwriting appetite of some demolition insurance programs.

A carrier willing to insure mechanical demolition may not necessarily be willing to insure explosive demolition.

That’s an important distinction.

If your company performs blasting—or plans to subcontract it—disclose that operation clearly during the insurance application process.

Never assume that because your policy covers “demolition,” every method of demolition is automatically included.

C: Collapse

The “C” stands for collapse.

This is where XC&U becomes especially relevant to demolition contractors.

Demolition involves intentionally dismantling structures.

Depending on the project, that could involve:

  • Walls
  • Floors
  • Roofs
  • Structural components
  • Entire buildings

The intended demolition itself is one thing.

The liability concern is what happens when structural movement causes unintended damage or injury.

Imagine This Scenario

Your company is demolishing one building located close to another structure.

During the work, a portion of the structure falls differently than expected and damages the neighboring property.

The loss could be substantial.

Now imagine discovering after the incident that your liability policy contains an exclusion relevant to the collapse exposure created by your operations.

That’s why demolition contractors need to understand their policies before the work begins, not after a claim occurs.

Collapse Exposure Isn’t Limited to Complete Building Demolition

Interior demolition can create structural concerns too.

So can renovation work.

Removing walls, cutting structural components, excavating near foundations, or performing other operations that affect structural stability can potentially create collapse exposures.

The actual work matters.

An underwriter needs an accurate description of your operations to evaluate the risk properly.

U: Underground

The “U” in XC&U refers to underground hazards.

This can involve damage to underground property arising from certain contracting operations, depending on applicable policy definitions and language.

Think about what’s underneath a jobsite.

Potential underground infrastructure can include:

  • Water lines
  • Sewer lines
  • Gas lines
  • Electrical service
  • Telecommunications
  • Fiber-optic cables
  • Drainage systems
  • Other buried utilities

Damaging one can become expensive quickly.

What Does XC&U Stand For?

The Utility Line You Didn’t Know Was There

Imagine your demolition project includes removing foundations or performing excavation.

Your operator begins working in an area believed to be clear.

Then the equipment strikes an underground utility.

Now the project may involve:

  • Utility repair
  • Project delays
  • Property damage
  • Business interruption
  • Emergency response
  • Potential third-party claims

The circumstances surrounding the incident and the policy language determine how insurance may respond.

The important point is that demolition work doesn’t stop at ground level.

Underground exposure needs to be considered too.

The Utility Line You Didn't Know Was There

Why Is XC&U Particularly Important for Demolition Contractors?

Consider the three exposures together:

Explosion

Demolition operations may sometimes involve explosive hazards.

Collapse

Demolition inherently involves removing or destabilizing structural components.

Underground

Demolition may include foundations, excavation, utility exposure, or other below-grade work.

Now compare that with an office-based business.

The difference in risk is obvious.

That’s why demolition contractor insurance often requires specialized underwriting.

Why Is XC&U Particularly Important for Demolition Contractors?

Is XC&U a Separate Insurance Policy?

Not necessarily.

When contractors discuss “XC&U coverage,” they’re often talking about whether their Commercial General Liability insurance excludes or addresses these particular hazards.

The terminology can be confusing because people sometimes refer casually to “having XC&U.”

The more precise question is:

“How does my liability policy address explosion, collapse, and underground hazards for the operations I perform?”

That answer depends on the actual policy.

Is XC&U a Separate Insurance Policy?

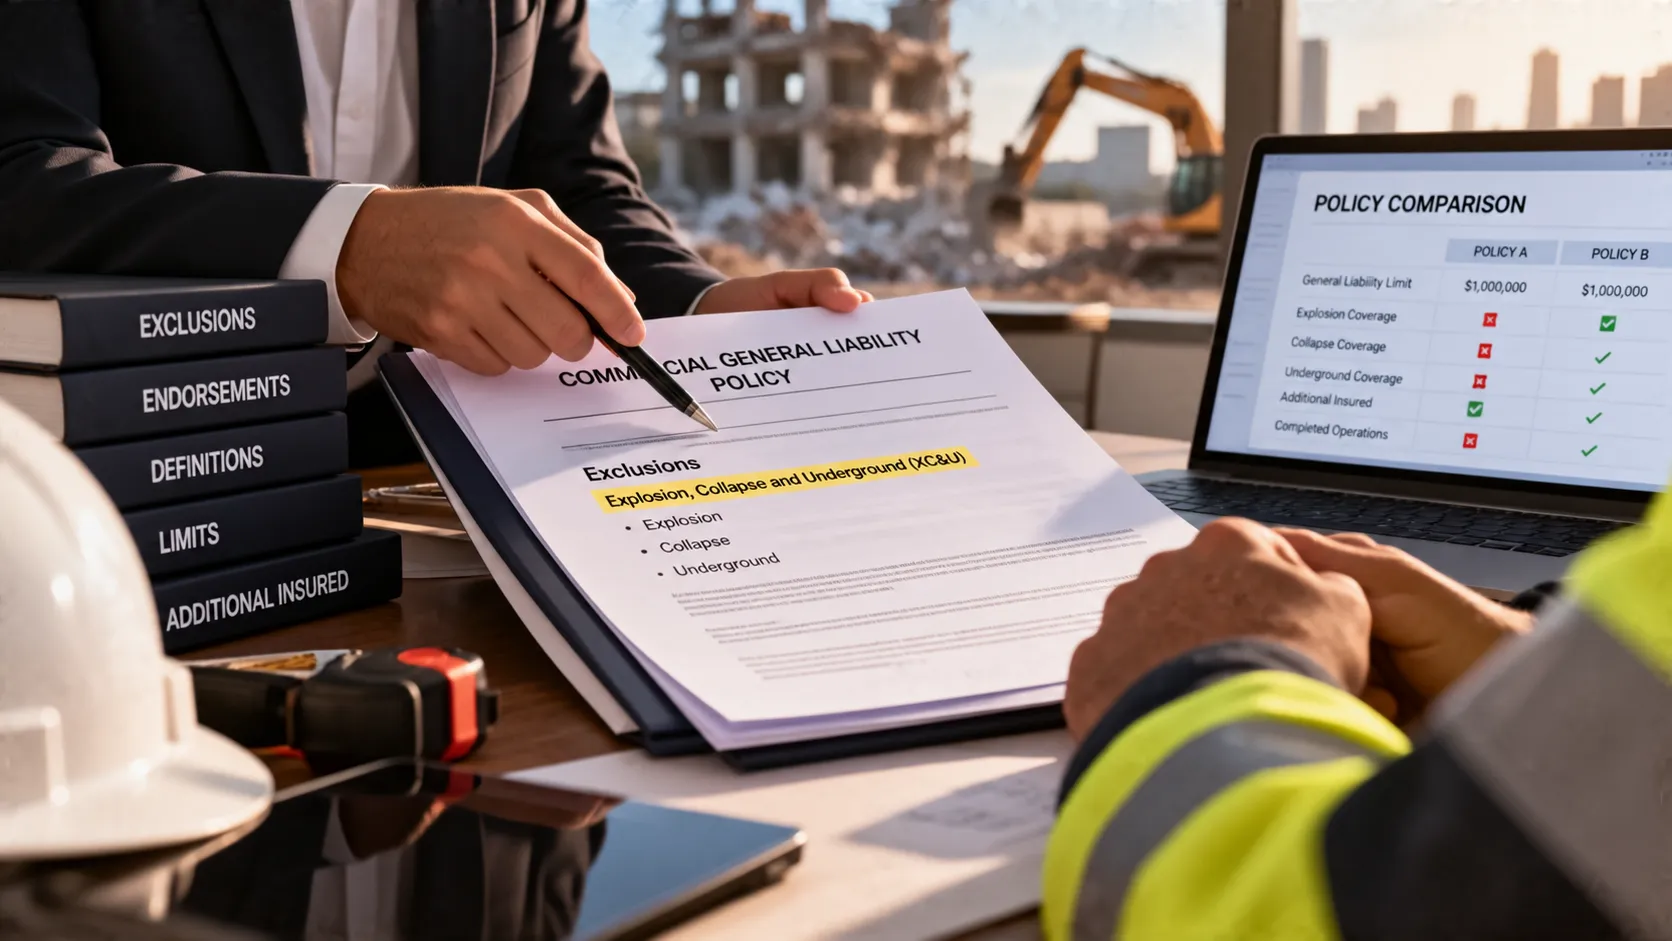
What Is an XC&U Exclusion?

An exclusion identifies circumstances or exposures the insurance policy does not cover.

Depending on the policy, exclusions relating to explosion, collapse, or underground property damage may restrict coverage for certain claims arising from those operations.

For a demolition contractor, that can create an obvious concern.

You could potentially have a general liability policy while having limitations involving some of the activities central to your business.

That’s why the existence of a policy alone doesn’t tell the entire story.

“I Have General Liability” Isn’t Enough

This is one of the most important insurance lessons for contractors.

Two businesses can each carry:

$1 million in Commercial General Liability insurance

and have very different protection.

Why?

Because policies can differ in:

  • Exclusions
  • Endorsements
  • Definitions
  • Covered operations
  • Limits
  • Aggregates
  • Additional insured provisions
  • Completed operations provisions

The number printed on the certificate of insurance doesn’t explain all of that.

For demolition contractors, the details can matter significantly.

What Is an XC&U Exclusion?

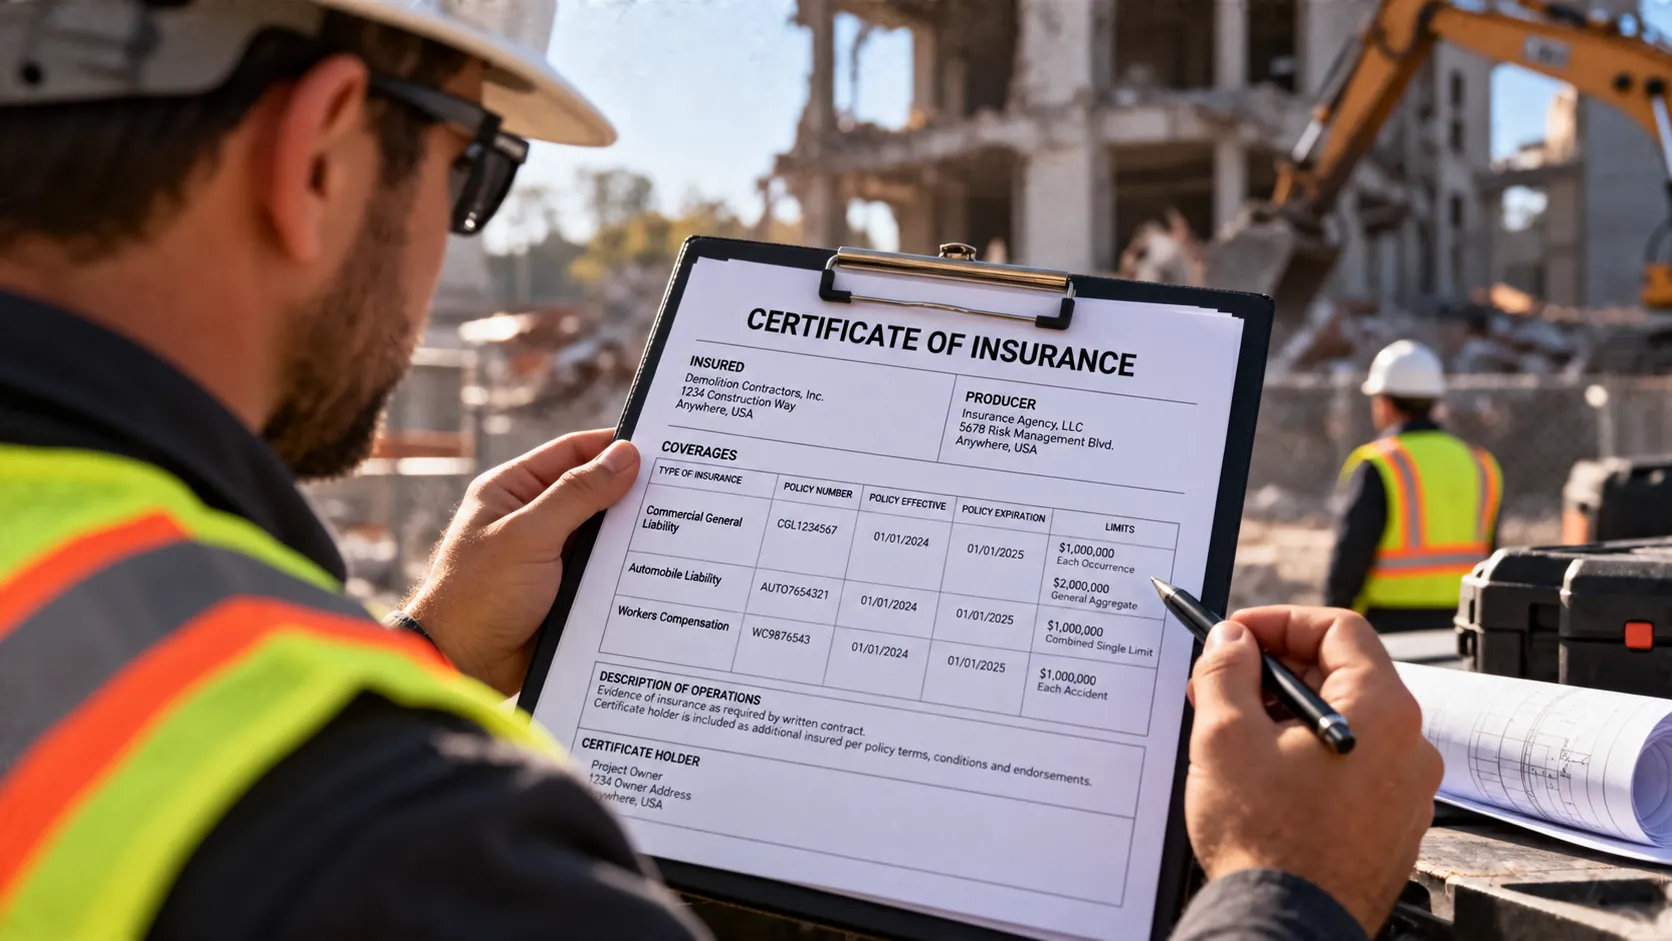
What Does a Certificate of Insurance Tell You?

A Certificate of Insurance can provide useful evidence that certain insurance policies and limits exist at the time the certificate is issued.

But a certificate is not a substitute for reading the actual policy and applicable endorsements.

That’s particularly important when a contract contains specific requirements involving XC&U or other specialized coverage provisions.

Don’t assume a certificate showing General Liability automatically proves every contractual insurance requirement has been satisfied.

What Does a Certificate of Insurance Tell You?

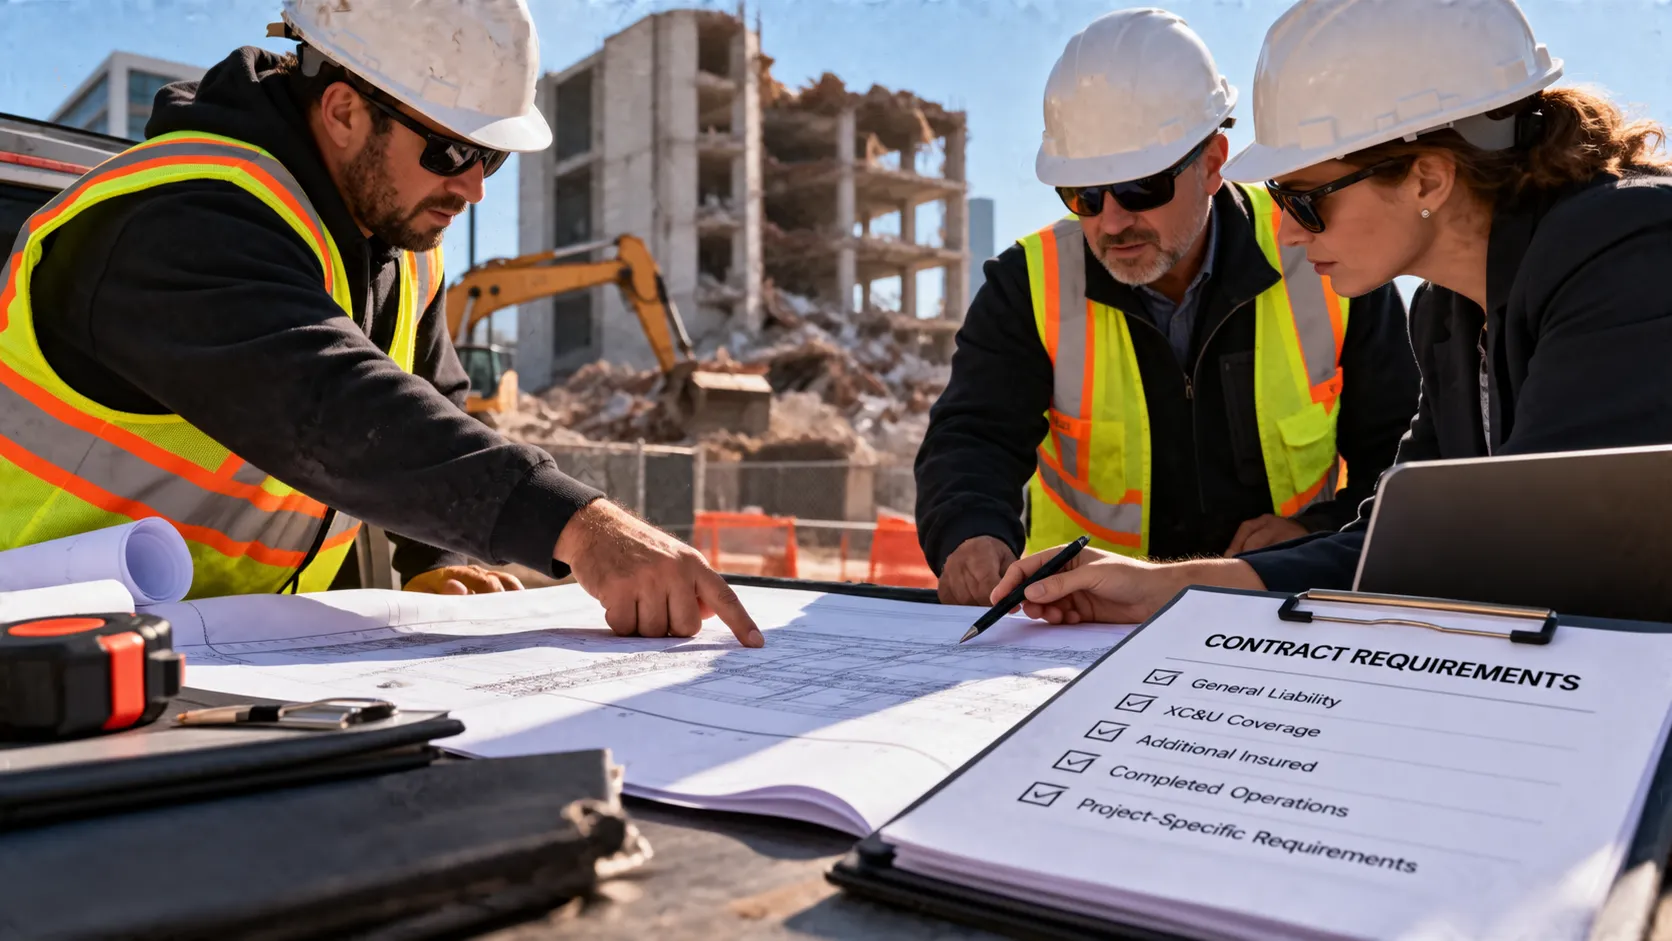
Why General Contractors and Project Owners May Require XC&U

Owners and general contractors want to transfer or manage risk associated with the companies working on their projects.

If you’re performing demolition, they may be concerned about damage caused by:

  • Structural collapse
  • Excavation
  • Underground utilities
  • Adjacent property
  • Other demolition operations

Their contract may therefore specify that your insurance cannot contain certain exclusions relating to these exposures.

This is why insurance should be reviewed before bidding or signing the contract.

Why General Contractors and Project Owners May Require XC&U

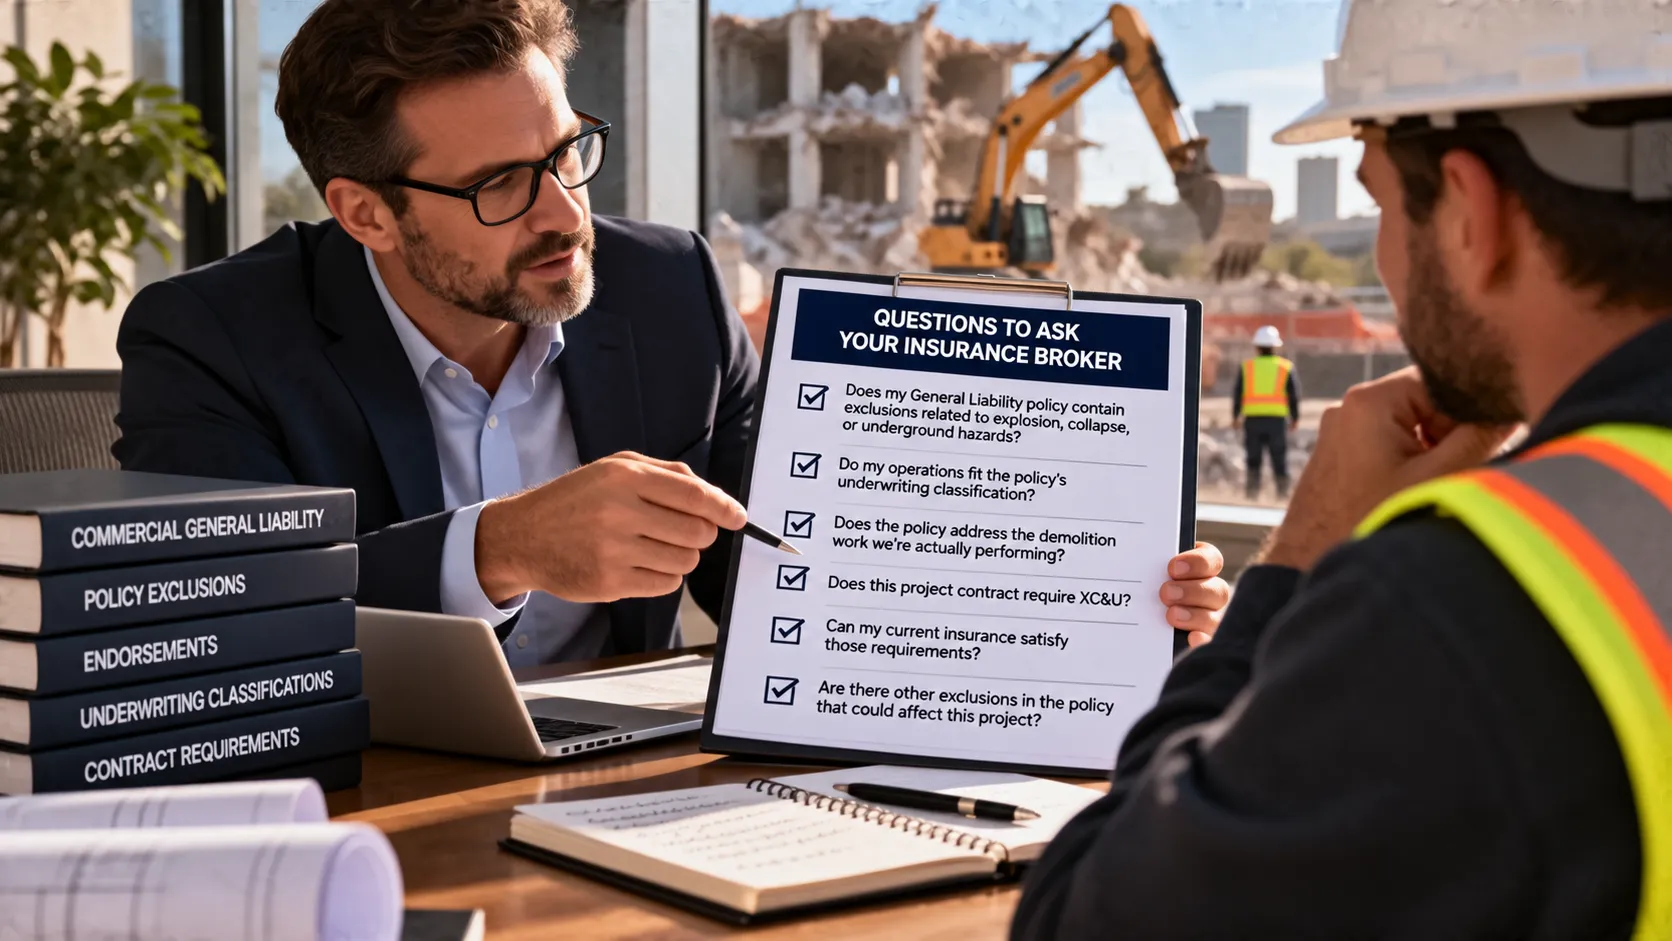
Read the Insurance Requirements Before You Price the Job

Imagine winning a major demolition contract.

Then you send the insurance requirements to your broker.

There’s a problem.

Your current carrier can’t satisfy one of the required provisions.

Now you have several possibilities:

You need different insurance.

You need an endorsement.

The contract needs to change.

The project doesn’t fit your existing insurance program.

Or obtaining the required coverage materially changes your cost.

None of those are conversations you want to have after you’ve already priced the project.

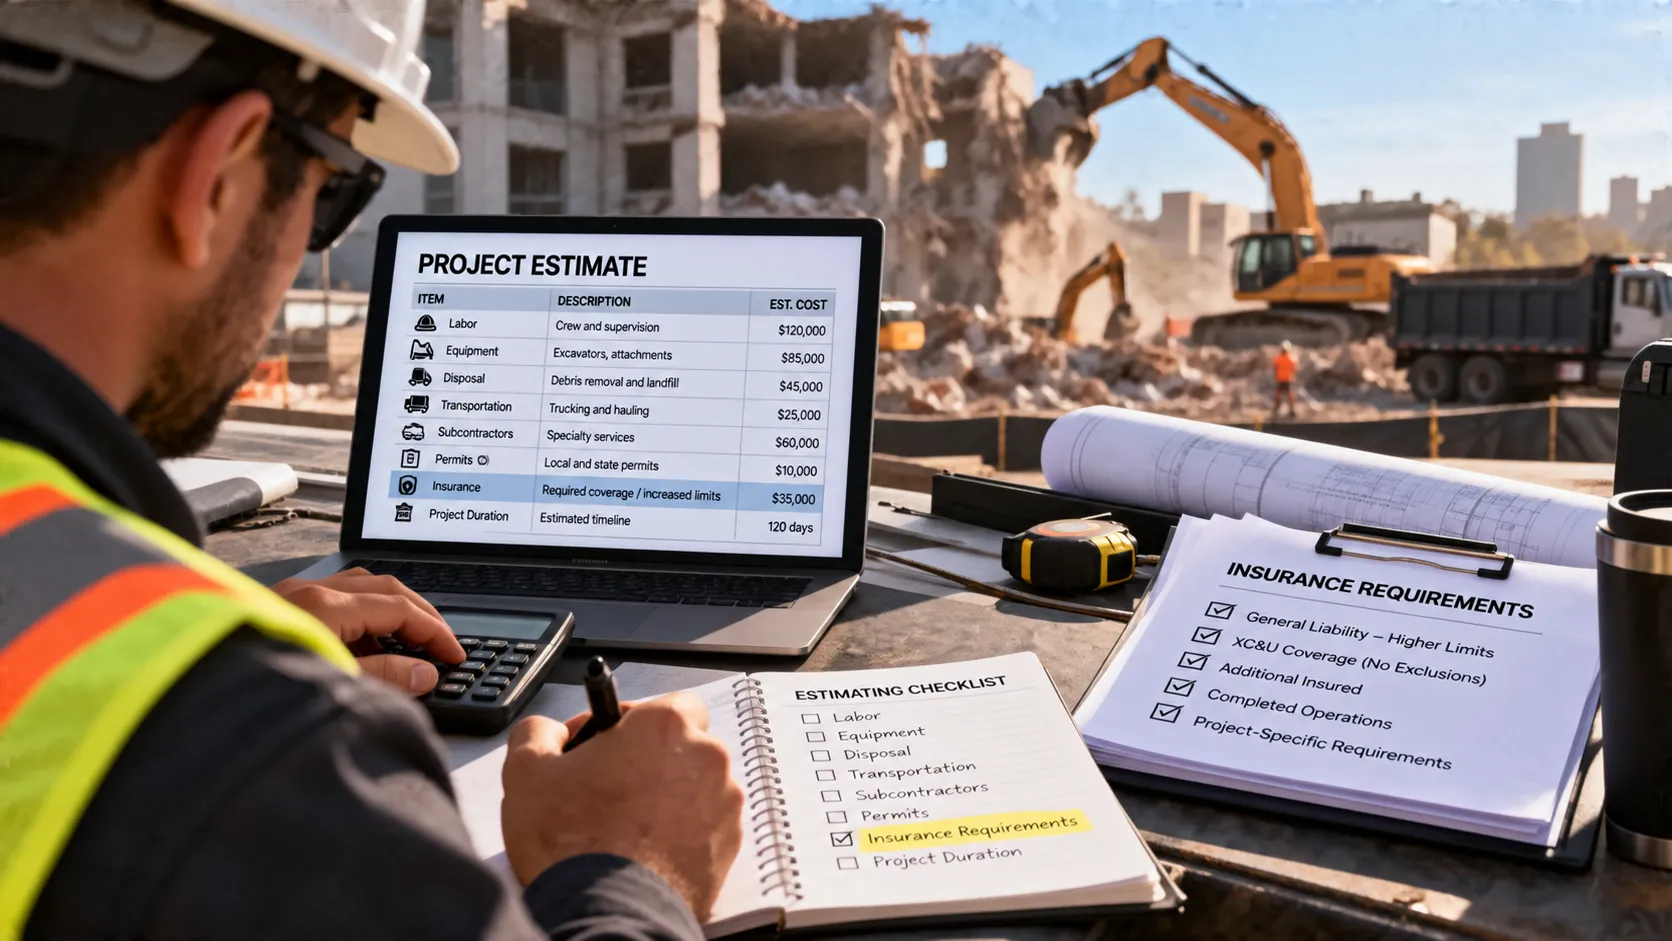
Insurance Requirements Should Be Part of Estimating

Demolition contractors are accustomed to estimating:

  • Labor
  • Equipment
  • Disposal
  • Transportation
  • Subcontractors
  • Permits
  • Project duration

Insurance requirements should be reviewed as part of that same process.

If a project requires substantially higher limits or specialized coverage, satisfying those requirements may affect the economics of the job.

Know that before you submit the bid.

Insurance Requirements Should Be Part of EstimatingDoes XC&U Affect Residential Demolition?
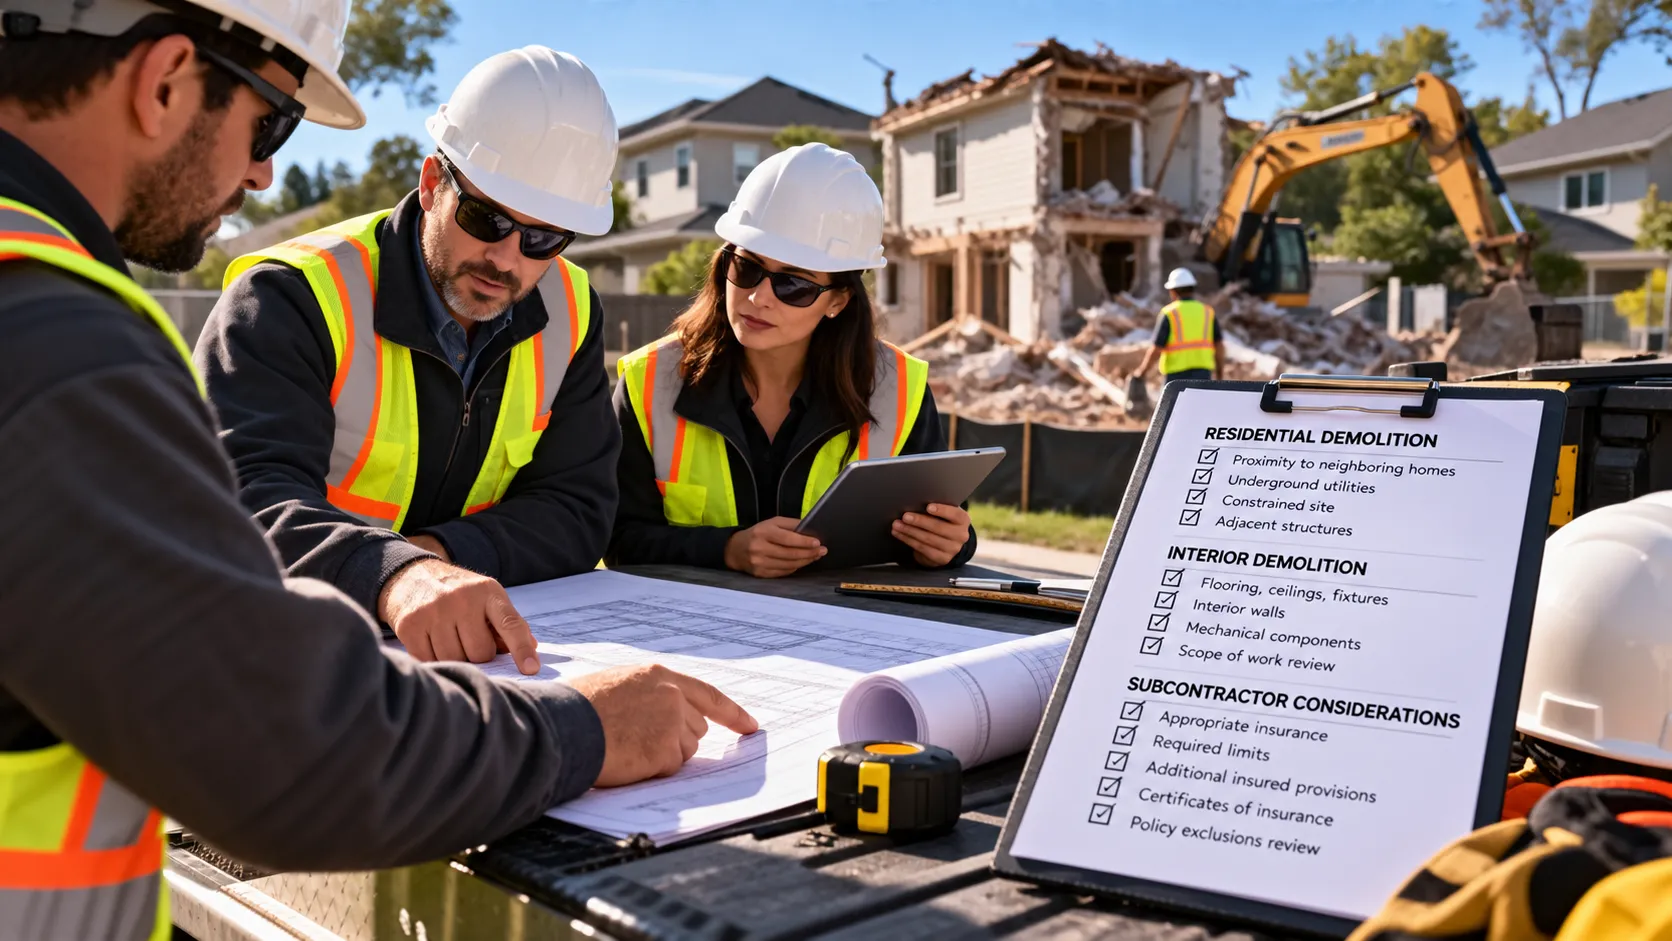
It can.

A single-family residence may seem less complicated than a large commercial building, but the property can still be located:

  • Close to neighboring homes
  • Near underground utilities
  • On a constrained site
  • Near retaining walls
  • Near other structures

The relevant exposure depends on the project and operations, not simply whether the property is residential or commercial.

Does XC&U Affect Residential Demolition?
What About Interior Demolition?
Interior strip-outs can have different exposures than complete structural demolition.

The contractor may be removing:

  • Flooring
  • Ceilings
  • Fixtures
  • Mechanical components
  • Interior walls
  • Other building materials

Whether collapse or other XC&U-related exposures are relevant depends on the scope of work and applicable policy language.

Again, accurate descriptions matter.

What About Subcontractors?

Subcontracting doesn’t necessarily make an exposure disappear.

If your company hires another contractor to perform excavation, blasting, structural work, or another specialized operation, your insurance and contractual responsibilities still deserve careful review.

Questions to consider include:

  • Does the subcontractor carry appropriate insurance?
  • What limits are required?
  • Are written contracts used?
  • Are additional insured provisions required?
  • Are certificates collected?
  • Does the subcontractor’s policy contain relevant exclusions?
  • Does your own policy impose requirements regarding subcontracted work?

Subcontractor risk management should be part of the insurance discussion.

What Should Demolition Contractors Ask Their Insurance Broker?

You don’t need to become an insurance underwriter.

But you should know what questions to ask.

Before beginning a project, consider asking:

Does my General Liability policy contain exclusions related to explosion, collapse, or underground hazards?

Do my operations fit the policy’s underwriting classification?

Does the policy address the demolition work we’re actually performing?

Does this project contract require XC&U?

Can my current insurance satisfy those requirements?

Are there other exclusions in the policy that could affect this project?

Those questions are much more useful than simply asking:

“Am I covered?”

What Should Demolition Contractors Ask Their Insurance Broker?

What Information Does an Underwriter Need?

If XC&U exposures are relevant, the underwriter may want to understand the project and your company’s operations in detail.

Information could include:

  • Type of demolition
  • Structural characteristics
  • Building height
  • Project value
  • Proximity to neighboring structures
  • Excavation
  • Underground work
  • Utility identification procedures
  • Blasting
  • Equipment used
  • Subcontracted operations
  • Employee experience
  • Loss history
  • Safety procedures

The more unusual the project, the more important accurate information becomes.

What Information Does an Underwriter Need?

Never Hide an Operation Because You’re Worried About the Answer

Suppose your company occasionally performs an operation that you know insurance carriers scrutinize.

Leaving it off an application isn’t the solution.

Insurance needs to be based on what the business actually does.

An experienced specialty insurance professional can help determine which markets may be appropriate for those operations.

Accurate disclosure protects both sides of the insurance relationship.

Why Specialized Demolition Insurance Experience Matters

XC&U is a good example of why demolition contractors benefit from insurance professionals who understand demolition.

A generalist may see:

Contractor.

A demolition specialist sees:

What kind of demolition?
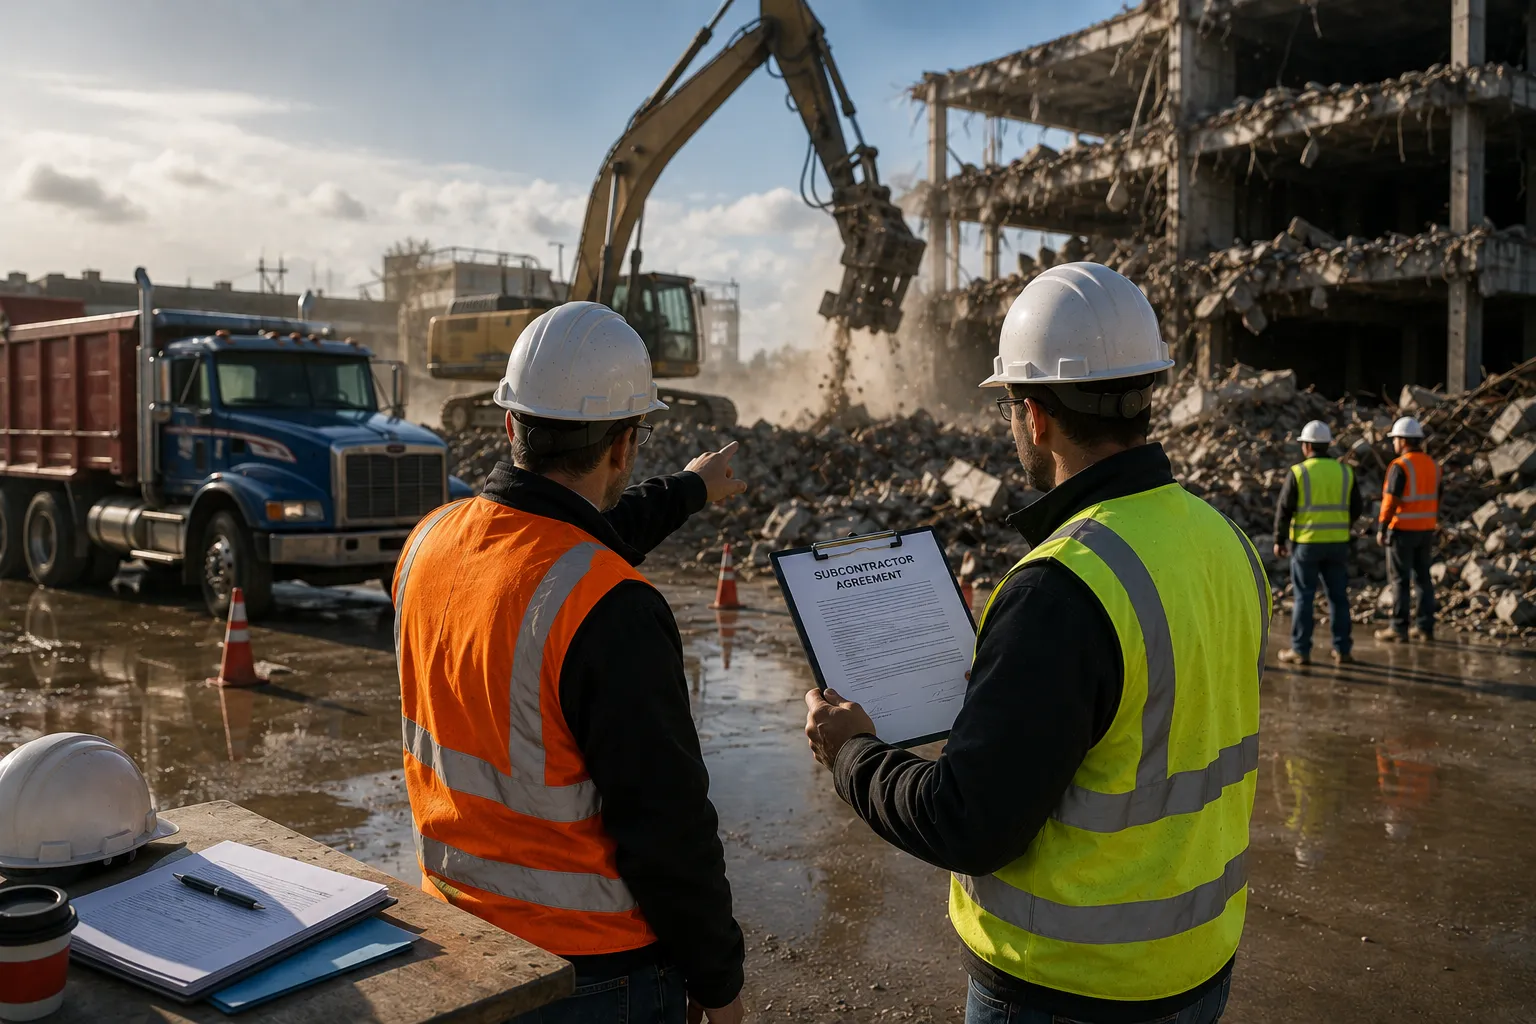
Residential?

Commercial?

Interior strip-out?

Structural?

Excavation?

How tall are the buildings?

How large are the projects?

How much is subcontracted?

What happens below grade?

What does the contract require?

Those questions help determine the actual exposure.

Apollo General Insurance Agency’s Demolition Contractor Program

Apollo General Insurance Agency has decades of experience in specialty commercial insurance and offers dedicated programs for eligible demolition contractors.

Apollo works with operations that can include residential tear-downs, commercial demolition, and interior strip-outs, subject to underwriting requirements.

The program can address important demolition insurance considerations, including XC&U exposures where applicable.

For contractors and insurance brokers dealing with demolition risks, working with a market that understands the class can make the underwriting conversation substantially more productive.

Need Demolition Contractor Insurance With XC&U Considerations?

Don’t wait until after winning a project to discover that your existing insurance can’t meet the contract requirements.

Review the project.

Review the insurance specifications.

Review your actual policy.

Then address questions before work begins.

Insurance professionals and brokers looking for specialty demolition contractor coverage can learn more about Apollo General Insurance Agency’s demolition program through Apollo General Insurance Agency.

Conclusion

XC&U sounds complicated.

The concept itself isn’t.

X: Explosion

C: Collapse

U: Underground

For many businesses, these aren’t major everyday concerns.

For demolition contractors, they can be directly connected to the work being performed.

That’s why simply knowing you have General Liability insurance isn’t enough.

Understand your operations.

Understand your contract.

Understand your policy.

And before bidding the next project, ask one more question:

“Does our insurance actually address the risks this job creates?”

Conclusion APGen

Frequently Asked Questions About XC&U Coverage

1. What does XC&U stand for in insurance?

XC&U stands for Explosion, Collapse, and Underground.

2. What is XC&U coverage?

The term generally refers to how a liability policy addresses explosion, collapse, and underground hazards associated with certain contracting operations.

3. Is XC&U a separate insurance policy?

Not necessarily. XC&U commonly relates to provisions, exclusions, or coverage within Commercial General Liability insurance.

4. Why do demolition contractors need to understand XC&U?

Demolition operations can involve structural collapse, underground property, excavation, and potentially explosive hazards, making these exposures particularly relevant.

5. What does the X in XC&U mean?

X refers to explosion hazards.

6. What does the C in XC&U mean?

C refers to collapse hazards.

7. What does the U in XC&U mean?

U refers to underground hazards.

8. Does every General Liability policy include XC&U?

No. Policies vary, and exclusions or limitations may apply.

9. What is an XC&U exclusion?

It generally refers to policy language excluding or restricting coverage for certain explosion, collapse, or underground hazards.

10. Does a certificate of insurance show whether XC&U is covered?

A certificate alone may not provide enough information to determine how the underlying policy addresses XC&U. Review the actual policy and endorsements.

11. Why would a general contractor require XC&U?

The project may involve demolition, excavation, structural work, underground utilities, or other operations creating these exposures.

12. Does XC&U matter for residential demolition?
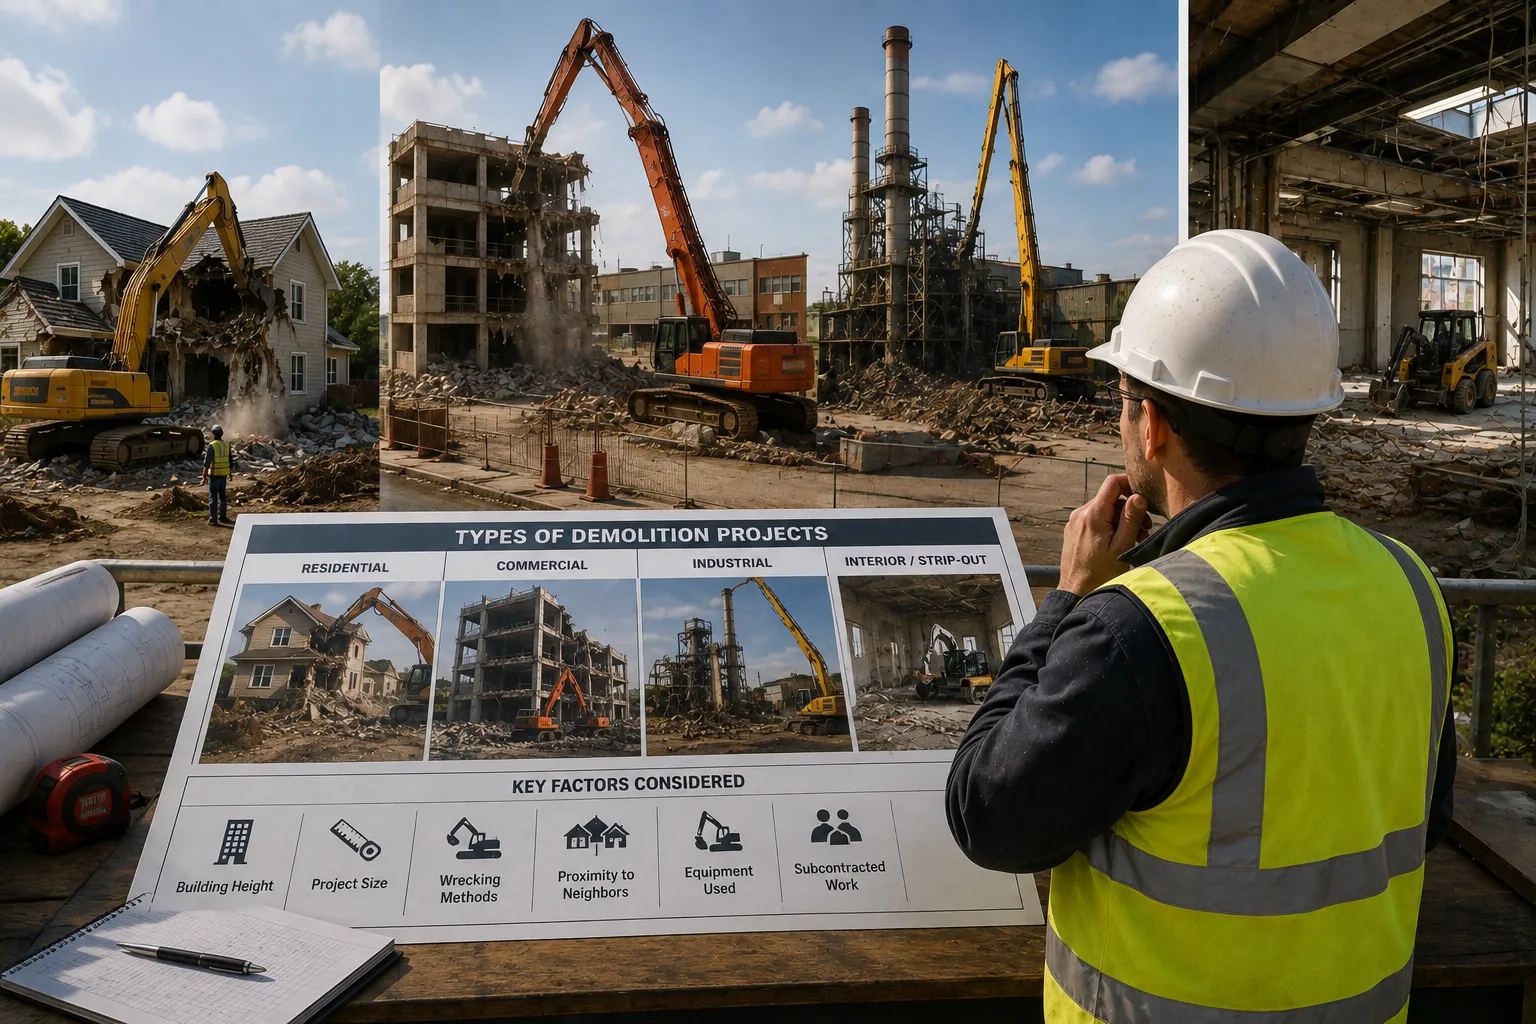
Potentially. The exposure depends on the operations, site, neighboring property, underground utilities, and applicable insurance policy.

13. Does XC&U matter for interior demolition?
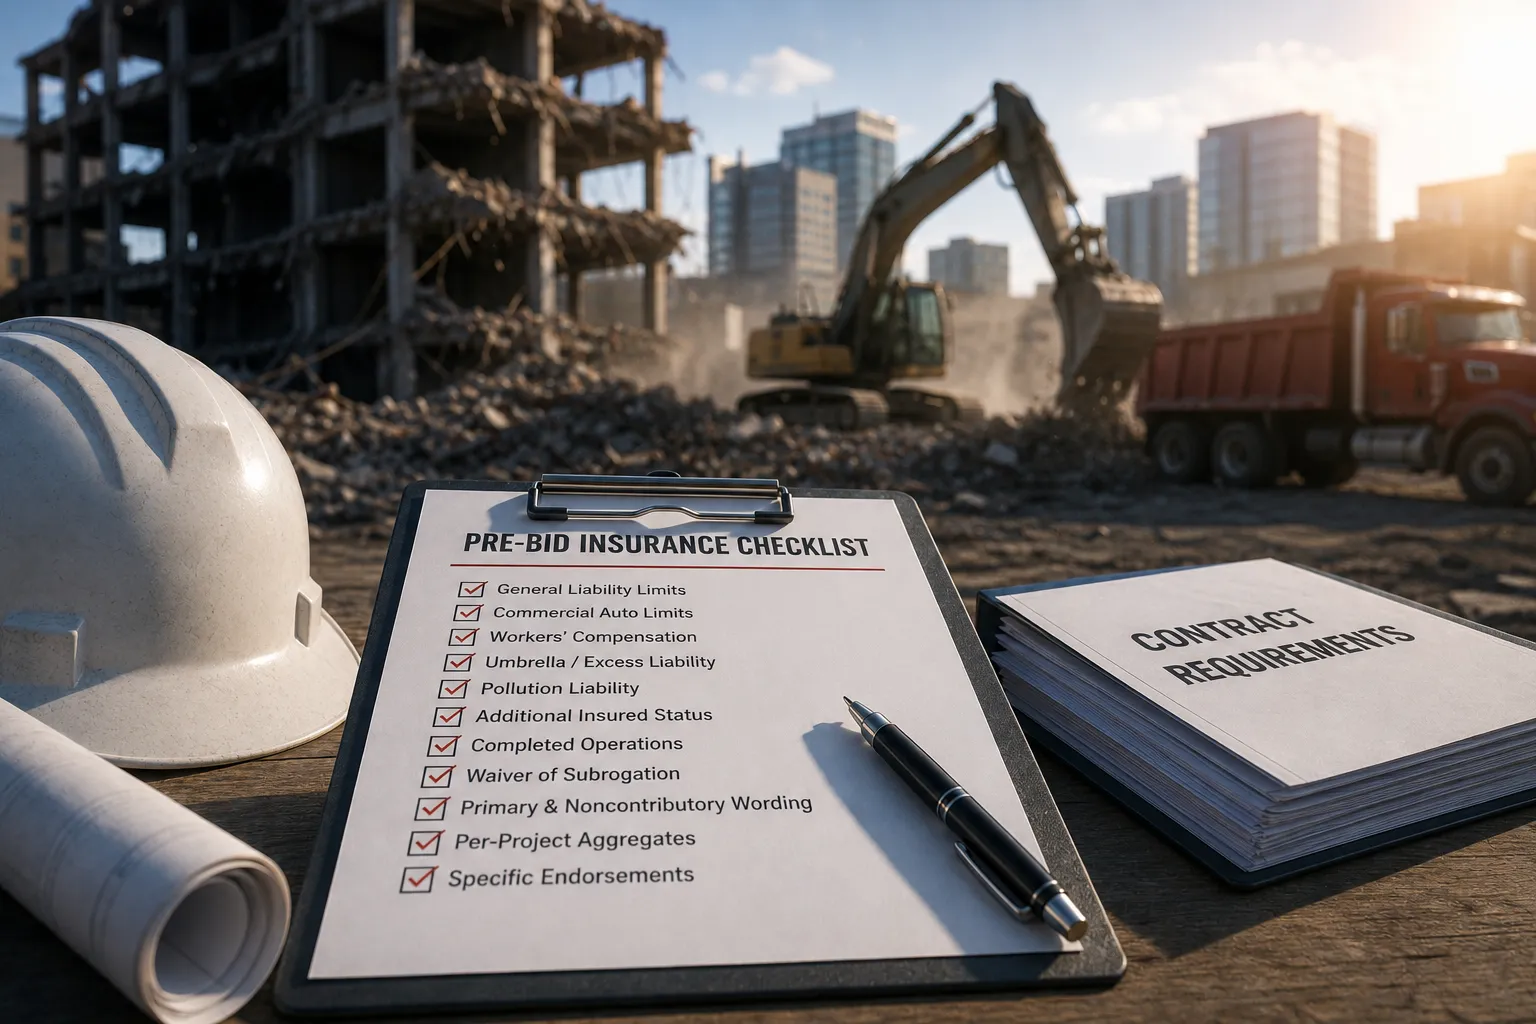
It may, depending on the work being performed and the applicable policy language.

14. Does XC&U automatically cover blasting?

No. Blasting can be a specialized exposure and should be specifically discussed with the insurance professional and carrier.

15. Can underground utility damage be an XC&U issue?

Potentially. Underground hazards can be relevant when contracting operations damage buried property or utilities, subject to policy definitions and terms.

16. Should I review XC&U before bidding a demolition project?

Yes. Reviewing contractual insurance requirements before bidding can help identify potential coverage or cost issues early.

17. Can an XC&U exclusion keep me from winning a project?

Potentially. If the contract requires coverage your policy cannot provide, you may not satisfy the project’s insurance requirements.

18. Do subcontractors need XC&U coverage?

That depends on their operations, contractual requirements, and insurance program. Subcontractor coverage should be evaluated based on the work they perform.

19. How do I know whether my demolition policy has an XC&U exclusion?

Review the policy and endorsements with an insurance professional familiar with demolition risks.

20. Does Apollo General Insurance Agency work with XC&U exposures?

Apollo offers specialty insurance programs for eligible demolition contractors and can evaluate applicable demolition exposures and coverage requirements as part of the underwriting process.

7 Reasons Demolition Contractors Get Declined for Insurance

7 Reasons Demolition Contractors Get Declined for Insurance

Introduction

Getting declined for insurance can be frustrating—especially when you need coverage to bid a job, satisfy a contract, or keep a project moving.

For demolition contractors, declines are not unusual.

Demolition is a specialized class of business, and underwriters look closely at how the company operates, what types of structures it works on, who performs the work, what losses have occurred, and whether the contractor appears to have strong controls in place.

A decline does not always mean your business is uninsurable.

Sometimes it means the risk does not fit a particular carrier.

Other times, the problem is the way the account was presented.

And in some cases, the underwriter sees a genuine exposure that needs to be addressed before coverage becomes available.

At Apollo General Insurance Agency, demolition contractors are a specialty. Understanding why carriers say no is often the first step toward presenting the business more effectively.

Here are seven common reasons demolition contractors can be declined for insurance.

What You’ll Learn

  • Why demolition risks receive extra underwriting scrutiny
  • How loss history can affect eligibility
  • Why project type and size matter
  • How subcontractors can create underwriting concerns
  • Why incomplete applications hurt demolition accounts
  • How safety procedures influence underwriting
  • What contractors can do after being declined

What You'll Learn APGen

Why Demolition Contractors Are Harder to Insure

Demolition exposes an insurance carrier to risks that do not exist in many other contracting businesses.

A demolition project may involve:

  • Structural collapse
  • Heavy equipment
  • Work near neighboring buildings
  • Underground utilities
  • Dust and debris
  • Environmental exposures
  • High-value property
  • Employees working around unstable structures
  • Subcontractors
  • Transportation of equipment and debris

That does not mean demolition contractors cannot obtain good insurance.

It means carriers want to understand exactly what they are being asked to insure.

The more uncertainty an underwriter sees, the more difficult the account can become.

Why Demolition Contractors Are Harder to Insure

1. Your Loss History Raises Concerns

One of the first things an underwriter may review is your loss history.

That can include both:

  • The number of claims
  • The severity of those claims

A contractor with several small losses may raise different concerns than one with a single large loss.

The important question is not simply:

“Have you had claims?”

It is:

“What do those claims tell the underwriter about the way the company operates?”

For example, repeated property-damage claims could suggest problems with jobsite controls.

Employee injury claims might cause the underwriter to look more closely at safety procedures and training.

Vehicle losses could raise concerns about driver selection or fleet management.

A Claim Does Not Automatically Mean a Decline

Demolition is risky work.

Experienced underwriters understand that losses can happen.

What matters is how the company responded.

If you had a significant claim, be prepared to explain:

  • What happened
  • Why it happened
  • What changed afterward
  • Whether new procedures were implemented
  • Whether employees were retrained
  • Whether equipment or supervision changed
  • What was done to prevent recurrence

A contractor who can demonstrate meaningful corrective action may present a much stronger risk than one who simply submits a loss run without explanation.

2. The Projects Are Outside the Carrier’s Appetite

Not every demolition carrier wants every demolition contractor.

This is one of the most important things contractors should understand after receiving a decline.

Sometimes the answer is not:

“We don’t like your company.”

It is:

“We don’t insure that type of work.”

A carrier may be comfortable with:

  • Residential tear-downs
  • Interior demolition
  • Smaller commercial buildings

but uncomfortable with:

  • Large structural demolition
  • High-rise work
  • Industrial facilities
  • Bridge demolition
  • Blasting
  • Hazardous-material work
  • Certain excavation operations

The contractor may be perfectly well-run.

The account simply does not match that insurer’s underwriting guidelines.

3. Your Largest Projects Are Too Large

Revenue alone does not tell an underwriter how much risk is concentrated in a single project.

Imagine two demolition contractors that each generate $5 million in annual revenue.

Contractor A performs dozens of smaller projects.

Contractor B earns most of its revenue from two enormous demolition jobs.

Those may be very different insurance risks.

Underwriters may ask about:

  • Largest project completed
  • Largest project anticipated
  • Maximum building height
  • Maximum contract value
  • Type of structure
  • Location of the work
  • Distance from adjacent buildings

A contractor moving into larger projects can sometimes outgrow the appetite of its current insurance program.

That is not necessarily a bad thing.

It may simply mean the insurance strategy needs to evolve along with the company.

4. Too Much Work Is Subcontracted

Subcontracting is common in construction.

But from an insurance standpoint, it creates another layer of uncertainty.

The underwriter is no longer evaluating only your employees and procedures.

Now the carrier also has to consider the work being performed by companies you hire.

That may raise questions such as:

  • What percentage of your work is subcontracted?
  • Which operations are subcontracted?
  • How are subcontractors selected?
  • Are written contracts required?
  • What insurance limits must subcontractors maintain?
  • Are certificates of insurance collected?
  • Are you named as an additional insured?
  • Is completed operations coverage required?
  • Are subcontractors allowed to subcontract again?

If a demolition contractor subcontracts a large portion of its work but has weak controls around those subcontractors, an underwriter may see significantly more exposure.

Certificates Alone May Not Be Enough

Collecting a certificate of insurance is a useful administrative step.

But strong subcontractor risk management can involve much more.

Written agreements, appropriate insurance requirements, verification procedures, and consistent documentation can all help demonstrate that subcontractors are being actively managed.

5. Your Safety Program Is Weak—or Cannot Be Demonstrated

Demolition is an industry where safety procedures matter.

Underwriters may want to know how your company approaches:

  • Employee training
  • Personal protective equipment
  • Equipment operation
  • Site inspections
  • Hazard identification
  • Fall protection
  • Utility identification
  • Daily safety meetings
  • Supervisor responsibilities
  • Incident reporting
  • OSHA-related procedures

A contractor may say:

“Safety is very important to us.”

An underwriter may respond:

“Show me.”

That is where documentation becomes valuable.

A written safety program, training records, toolbox-talk procedures, incident-management processes, and experienced supervision can all help demonstrate that safety is built into the company’s operations.

6. Your Application Is Incomplete or Inconsistent

This is one of the most avoidable reasons a demolition account can run into trouble.

Specialty insurance applications can be detailed.

They may ask about:

  • Revenue
  • Payroll
  • Subcontracted costs
  • Project types
  • Equipment
  • Geographic territory
  • Loss history
  • Employee experience
  • Safety procedures
  • Maximum project size
  • Hazardous operations

If answers are missing or inconsistent, the underwriter has to make assumptions.

And underwriters generally do not like uncertainty.

For example:

One document says annual revenue is $4 million.

Another says $6 million.

The application indicates no subcontracting.

Financial information shows significant subcontractor expenses.

The contractor says it performs only residential demolition.

The website shows large commercial projects.

Those inconsistencies can slow down underwriting or cause the underwriter to question whether the full exposure is being disclosed.

Accuracy Is Better Than Trying to Look Low Risk

Contractors sometimes worry that honestly describing higher-risk work will make insurance harder to obtain.

But incomplete or inaccurate information can create a much bigger problem.

Specialty underwriters need to understand the actual operation in order to determine whether they can insure it.

7. The Contractor Has Grown Faster Than Its Risk Management

Growth is good.

But rapid growth can make underwriters nervous when the company’s systems have not grown with it.

Imagine a demolition company that goes from:

$1 million in revenue

to

$5 million in revenue

in a relatively short period.

The underwriter may want to know:

  • Did the management team expand?
  • Were additional supervisors hired?
  • Did employee training improve?
  • Are larger projects being accepted?
  • Is more work being subcontracted?
  • Has equipment increased?
  • Are safety procedures keeping pace?
  • Does the company’s financial position support the growth?

A company that has grown rapidly but is still operating with the same controls it used when it was much smaller may create concerns.

The issue is not growth itself.

The issue is whether the organization has matured along with the revenue.

Other Reasons a Demolition Account May Be Difficult to Place

The seven issues above are common, but they are not the only reasons coverage may be difficult.

An underwriter may also be concerned about:

  • New ventures
  • Limited demolition experience
  • Poor financial condition
  • Prior insurance cancellations
  • Significant gaps in coverage
  • Unusual contract requirements
  • Blasting exposures
  • Environmental risks
  • High employee turnover
  • Poor vehicle loss history
  • Work in certain geographic areas
  • Lack of experienced supervision

This is why demolition insurance should not be approached as a simple commodity purchase.

Other Reasons a Demolition Account May Be Difficult to Place

What Should You Do After Being Declined?

The first thing is to understand the reason.

Ask:

Was the account declined because of the company—or because it did not fit the carrier?

Those are very different situations.

Then review the submission.

Look for:

  • Missing information
  • Inconsistent numbers
  • Unexplained claims
  • Poorly described operations
  • Missing safety documentation
  • Weak subcontractor controls

Sometimes improving the presentation of the account can make a meaningful difference.

Other times, the answer is finding a carrier whose appetite better matches the contractor’s operations.

What Should You Do After Being Declined?

A Better Submission Can Make a Better Impression

Insurance underwriting is partly about risk.

It is also about information.

A well-prepared demolition submission can help the underwriter understand the business quickly.

Consider providing:

  • Complete applications
  • Current loss runs
  • Detailed claim explanations
  • Project history
  • Description of operations
  • Management résumés
  • Safety programs
  • Equipment schedules
  • Financial statements
  • Subcontractor agreements
  • Sample contracts
  • Photos of completed projects

The objective is not to overwhelm the underwriter.

It is to answer the questions they are likely to ask before they have to ask them.

A Better Submission Can Make a Better Impression

Be Ready to Explain What Makes Your Company Different

Demolition businesses can look similar on paper.

The details matter.

Maybe your supervisors average 20 years of experience.

Maybe you have an unusually strong safety record.

Maybe your company specializes in controlled interior strip-outs rather than complete structural demolition.

Maybe you rarely subcontract.

Maybe you have a formal equipment-maintenance program.

Maybe management reviews every large project before bidding.

Those are details worth communicating.

A strong insurance submission should help the underwriter understand not only what the company does—but how it does it.

Be Ready to Explain What Makes Your Company Different

Insurance Is Part of Your Ability to Win Work

For demolition contractors, insurance is not just a cost of doing business.

It can affect which projects you can pursue.

If your insurance program cannot meet a contract’s requirements, you may not be able to bid the project—or you could win the job only to discover afterward that your coverage cannot satisfy the contract.

That is why insurance planning should happen before major opportunities arise.

As the company grows into larger jobs, new territories, or different types of demolition work, the insurance program should be reviewed as well.

Insurance Is Part of Your Ability to Win Work

Why Specialty Demolition Underwriting Matters

A general commercial insurance market may not understand all the differences between:

  • Residential tear-downs
  • Interior strip-outs
  • Commercial demolition
  • Structural demolition
  • Industrial work

A specialty demolition underwriter is more likely to understand the questions that actually matter.

Apollo General Insurance Agency offers dedicated insurance programs for eligible demolition contractors and has decades of experience with specialty commercial risks.

That experience can be particularly useful when an account does not fit neatly into a standard contractor insurance program.

Why Specialty Demolition Underwriting Matters

Was Your Demolition Company Declined for Insurance?

A decline does not necessarily mean the conversation is over.

It may mean:

  • The carrier was not the right fit
  • More information is needed
  • The account needs to be presented differently
  • Certain risk-management issues need to be addressed
  • A specialty market is more appropriate

The key is understanding the reason behind the decline.

Apollo General Insurance Agency works with specialty demolition contractor risks and insurance professionals seeking solutions for difficult-to-place accounts.

Learn more about Apollo’s demolition contractor insurance program at https://www.apgen.com/our-insurance/demolition-contractors-insurance/.

Was Your Demolition Company Declined for Insurance?

Conclusion

Demolition contractors can be declined for insurance for many reasons.

Some are outside the contractor’s control.

Others are very much within it.

Loss history, project size, subcontracting, safety practices, rapid growth, and incomplete applications can all influence an underwriter’s decision.

But one of the biggest mistakes is assuming a decline means:

“Nobody will insure us.”

Often, the more useful question is:

“Why did this carrier decline us?”

Once you understand the answer, you can determine what happens next.

Maybe the business needs stronger documentation.

Maybe risk-management practices need improvement.

Maybe the submission needs more detail.

Or maybe you simply need an insurance market that actually understands demolition.

Conclusion APGen

Frequently Asked Questions About Demolition Insurance Declines

1. Why would an insurance company decline a demolition contractor?

Common reasons include loss history, high-risk operations, large project sizes, excessive subcontracting, weak safety procedures, incomplete applications, or the contractor simply falling outside that carrier’s underwriting appetite.

2. Does a demolition insurance decline mean no one will insure me?

No. Different carriers have different underwriting guidelines and appetites.

3. Can previous insurance claims cause a decline?

Yes, particularly if losses are frequent, severe, or indicate recurring operational problems.

4. Can I still get demolition insurance after a large claim?

Possibly. The circumstances of the claim, corrective actions taken, overall loss history, and carrier appetite can all affect eligibility.

5. Should I explain old claims to the underwriter?

Yes. A clear explanation of what happened and what changed afterward can provide valuable context.

6. Why does project size matter to insurance companies?

Larger projects can increase the potential severity of a claim and may involve more complex exposures.

7. Can moving into commercial demolition affect my insurance?

Yes. Commercial or structural demolition may fall into a different underwriting category than smaller residential work.

8. Why do underwriters care about subcontractors?

Subcontractors introduce additional parties and potential liability into the project, so underwriters want to understand how they are selected and managed.

9. Can subcontracting too much work cause an insurance decline?

It can. High subcontracting percentages combined with weak controls may be a concern for some carriers.

10. What subcontractor records should demolition contractors maintain?

Depending on the business, records may include written contracts, certificates of insurance, additional insured documentation, and other required coverage information.

11. Do demolition contractors need a written safety program?

Requirements vary, but documented safety programs can be an important underwriting consideration and a valuable risk-management tool.

12. Does OSHA history affect demolition insurance?

Safety history and regulatory issues may be considered depending on the underwriter and account.

13. Why does an insurance application ask so many questions?

Demolition operations can vary dramatically, so underwriters need detailed information to understand the actual risk.

14. Can an incomplete application cause a decline?

Yes. Missing or inconsistent information can make it difficult for an underwriter to evaluate the risk.

15. Should I disclose all of my demolition operations?

Yes. Accurate descriptions are important because the insurer needs to understand the work being performed.

16. Can rapid business growth affect my insurance?

Yes. Underwriters may evaluate whether management, safety procedures, financial strength, supervision, and risk controls have kept pace with the company’s growth.

17. Can a new demolition company get insurance?

Possibly, but underwriters may closely evaluate the owners’ and managers’ prior industry experience.

18. Can insurance affect which demolition projects I can bid?

Yes. Owners and general contractors may impose specific insurance requirements that must be satisfied before work begins.

19. What should I do if my demolition company is declined?

Find out why the account was declined, review the submission for weaknesses, address any legitimate risk-management concerns, and work with insurance professionals experienced in demolition risks.

20. Does Apollo General Insurance Agency work with difficult demolition risks?

Apollo specializes in commercial insurance programs for eligible demolition contractors and may be able to help brokers and contractors evaluate accounts that require a more specialized insurance market.


What Insurance Does a Demolition Contractor Need?

What Insurance Does a Demolition Contractor Need?

Introduction

Demolition contractors face risks that most businesses never encounter.

You may be working around unstable structures, heavy equipment, neighboring buildings, underground utilities, hazardous materials, subcontractors, falling debris, and active jobsites—all while working under contracts that can impose very specific insurance requirements.

That means buying insurance for a demolition company isn’t as simple as purchasing a standard contractor policy.

The right insurance program needs to consider what you demolish, how you perform the work, where you work, who works for you, what equipment you operate, whether you subcontract, and what your contracts require.

At Apollo General Insurance Agency, demolition isn’t an unfamiliar class of business. Apollo has developed specialty insurance programs specifically for demolition contractors, including residential tear-downs, commercial demolition, and interior strip-outs.

So, what insurance should a demolition contractor consider?

Let’s break it down.

What You’ll Learn

  • What types of insurance demolition contractors commonly need
  • Why general liability coverage is particularly important for demolition
  • What XC&U means and why demolition contractors should understand it
  • How pollution risks can affect demolition projects
  • Why subcontractors can affect your insurance program
  • What coverage may be required before bidding a project
  • What underwriters may want to know about your demolition company
  • How to prepare before requesting a demolition insurance quote

What You'll Learn APGen

Why Is Demolition Contractor Insurance Different?

A painter, electrician, and demolition contractor can all be considered contractors.

Their risks aren’t remotely identical.

Consider what could happen during a demolition project.

A wall could fall in an unexpected direction.

Heavy equipment could damage neighboring property.

An underground utility could be struck.

Dust or contaminants could create environmental concerns.

An employee could be injured.

A subcontractor could cause damage.

A company truck could be involved in an accident.

Equipment could be damaged or stolen.

Then there is the structure itself.

Demolition contractors are intentionally dismantling, cutting, breaking, crushing, or removing buildings and building components. Activities that would be unusual losses for many businesses are simply part of the everyday work environment in demolition.

Insurance therefore needs to be evaluated around the contractor’s actual operations.

Why Is Demolition Contractor Insurance Different?

1. Commercial General Liability Insurance

Commercial general liability is one of the foundational coverages for demolition contractors.

General liability insurance can respond to certain claims involving third-party bodily injury or property damage arising from covered operations, subject to the terms, conditions, limitations, and exclusions of the policy.

For example, imagine a demolition contractor is removing part of a commercial structure and debris damages neighboring property.

Or a third party is injured around the jobsite.

Those are the types of liability exposures that make general liability coverage so important.

But demolition contractors need to look beyond simply asking:

“Do I have general liability insurance?”

The better question is:

“Does my general liability policy properly contemplate the demolition work I’m actually performing?”

Not every contractor policy is designed for demolition operations.

Commercial General Liability Insurance

2. XC&U Coverage

If you’re in demolition, this is an insurance term worth knowing.

XC&U refers to:

Explosion

Collapse

Underground

These exposures can be particularly relevant to demolition and excavation-related operations.

For example, demolition work may involve structural collapse as part of the intended operation or create exposure to underground utilities and surrounding property.

A contractor should therefore understand whether exclusions or limitations related to these exposures exist within a proposed policy.

Apollo’s demolition contractor program includes options addressing XC&U exposures, making this an important area to discuss when evaluating coverage.

Never assume that because you have a general liability policy, every demolition-related exposure is automatically covered.

XC&U Coverage

3. Workers’ Compensation Insurance

Demolition is physical work performed in environments where employees may encounter heavy machinery, debris, heights, unstable surfaces, tools, dust, noise, and numerous other hazards.

Workers’ compensation is designed to provide benefits for qualifying work-related employee injuries and illnesses in accordance with applicable law and policy terms.

Requirements vary depending on the state and circumstances of the business.

For demolition companies with employees, workers’ compensation should be an important part of the overall insurance discussion.

Underwriters may also be interested in how your company manages employee safety.

That can include:

  • Written safety programs
  • Employee training
  • Personal protective equipment
  • Jobsite procedures
  • Supervisor experience
  • Loss history
  • OSHA compliance practices
  • Claims-management procedures

Insurance doesn’t replace a strong safety culture.

The two should work together.

Workers' Compensation Insurance

4. Commercial Auto Insurance

Demolition companies frequently operate vehicles for much more than getting employees to work.

You may have:

  • Pickup trucks
  • Dump trucks
  • Service vehicles
  • Trailers
  • Equipment transport vehicles
  • Roll-off trucks
  • Other commercial vehicles

Personal auto insurance generally isn’t designed to cover vehicles being used for many commercial operations.

Commercial auto insurance can provide liability and other selected coverage for qualifying business vehicles and operations, depending on the policy.

This becomes especially important when employees regularly drive company vehicles or equipment and debris are transported between jobsites.

Commercial Auto Insurance

5. Contractors Pollution Liability

Pollution exposure deserves special attention in demolition.

Older structures can contain materials or substances that require careful handling.

Demolition activities can also disturb existing contaminants or create environmental exposures involving dust, debris, liquids, fuel, chemicals, or other materials.

A standard general liability policy may not provide the pollution protection a demolition contractor assumes it does.

Contractors Pollution Liability coverage can be designed to address certain pollution-related exposures arising from contracting operations.

The appropriate coverage depends heavily on the type of demolition being performed.

For contractors working on older buildings, industrial properties, contaminated sites, or projects involving environmental remediation, this discussion becomes particularly important.

Contractors Pollution Liability

6. Inland Marine and Contractors Equipment Coverage

Demolition equipment isn’t cheap.

Excavators, skid steers, loaders, breakers, crushers, attachments, generators, tools, and other equipment can represent a significant investment.

Commercial property insurance isn’t always designed to follow equipment wherever it goes.

That’s where inland marine or contractors equipment coverage may become important.

Depending on the policy, coverage may help protect qualifying equipment against covered losses while it is:

  • At your facility
  • On a jobsite
  • In storage
  • Being transported

The exact equipment, ownership structure, values, transportation methods, and exposures should be discussed when building the insurance program.

Inland Marine and Contractors Equipment Coverage

7. Umbrella or Excess Liability Insurance

Some demolition projects require higher liability limits than a standard underlying policy provides.

A contract, general contractor, property owner, municipality, or other party may require significant limits before allowing a demolition contractor onto the project.

Commercial umbrella or excess liability coverage can provide additional limits over certain underlying policies, subject to the policy’s terms and structure.

For larger demolition contractors, this may be an important part of both risk management and contract compliance.

Umbrella or Excess Liability Insurance

8. Additional Insured Requirements

If you’ve worked on commercial construction projects, you’ve probably seen this phrase:

Additional Insured.

Project owners and general contractors frequently require subcontractors to add certain parties to their liability insurance.

But additional insured requirements can become complicated.

A contract may specify:

  • Who must be added
  • Which policies must provide additional insured status
  • Whether ongoing operations are required
  • Whether completed operations are required
  • How long certain coverage must remain in effect

Simply producing a certificate of insurance doesn’t necessarily mean the underlying policy satisfies every contractual requirement.

Demolition contractors should understand what they’ve agreed to before beginning work.

Additional Insured Requirements

9. Completed Operations Coverage

What happens after you leave the jobsite?

A contractor’s liability exposure doesn’t necessarily disappear when the work is finished.

Completed operations coverage addresses certain covered bodily injury or property damage claims arising from completed work, subject to policy terms and exclusions.

For demolition contractors, completed operations requirements may also appear in construction contracts.

This is another reason the insurance policy and the contract need to be evaluated together.

Completed Operations Coverage

10. Primary and Noncontributory Coverage

Another phrase demolition contractors may encounter in contracts is:

Primary and Noncontributory.

Generally, this relates to how insurance policies respond when more than one policy could potentially apply to a claim.

A general contractor or property owner may require the demolition contractor’s insurance to respond on a primary basis without seeking contribution from certain other insurance.

Whether that requirement can be satisfied depends on the policy language and applicable endorsements.

This is not something contractors should assume is automatically included.

Primary and Noncontributory Coverage

11. Waiver of Subrogation

A construction contract may also require a waiver of subrogation.

In simple terms, subrogation generally refers to an insurance company’s ability, after paying a covered claim, to pursue another responsible party to recover some or all of that payment.

A waiver of subrogation can modify those rights under certain circumstances.

Because these provisions affect the relationship between contracts and insurance coverage, demolition contractors should discuss them with their insurance professionals before agreeing to contractual requirements.

Waiver of Subrogation

What About Subcontractors?

Subcontracting can significantly affect a demolition contractor’s insurance exposure.

Imagine your company wins a demolition project but hires another contractor to perform part of the work.

Who is responsible if that subcontractor causes a loss?

The answer can depend on contracts, insurance policies, applicable law, and the circumstances of the incident.

That’s why insurance underwriters may want to know:

  • What percentage of your work is subcontracted?
  • What operations are subcontracted?
  • Who are the subcontractors?
  • What insurance limits do they carry?
  • Do you obtain certificates of insurance?
  • Are written subcontractor agreements used?
  • Are additional insured requirements in place?
  • How do you verify subcontractor coverage?

Subcontractor management isn’t just paperwork.

It can be a significant component of the demolition company’s overall risk.

What About Subcontractors?

Residential vs. Commercial Demolition Insurance

Not all demolition contractors perform the same work.

A contractor tearing down single-family homes presents a different risk profile than a contractor demolishing large commercial or industrial structures.

Likewise, an interior strip-out contractor may have very different exposures than a company performing complete structural demolition.

Underwriters may consider factors such as:

  • Residential vs. commercial work
  • Maximum building height
  • Maximum project size
  • Structural demolition
  • Interior demolition
  • Industrial demolition
  • Excavation
  • Blasting
  • Wrecking methods
  • Proximity to neighboring structures
  • Equipment used
  • Subcontracted work

This is why accurately describing your operations is so important.

Residential vs. Commercial Demolition Insurance

What Insurance Do You Need Before Bidding a Demolition Project?

Don’t wait until after winning the project to read the insurance requirements.

Before submitting a bid, review the contract specifications carefully.

Look for requirements involving:

  • General liability limits
  • Commercial auto limits
  • Workers’ compensation
  • Umbrella or excess liability
  • Pollution liability
  • Additional insured status
  • Completed operations
  • Waiver of subrogation
  • Primary and noncontributory wording
  • Per-project aggregates
  • Specific endorsements

An inexpensive insurance policy isn’t inexpensive if it prevents you from qualifying for the projects your company wants.

Your insurance program should reflect the work you’re pursuing.

What Insurance Do You Need Before Bidding a Demolition Project?

What Do Demolition Insurance Underwriters Want to Know?

One of the best ways to improve the insurance process is to arrive prepared.

Demolition insurance underwriters may want substantially more information than you’d provide for a low-risk business.

Depending on the account, information could include:

  • Completed insurance applications
  • Description of operations
  • Project history
  • Current and previous loss runs
  • Annual revenue
  • Payroll
  • Subcontracting costs
  • Maximum project size
  • Geographic territory
  • Equipment schedules
  • Safety programs
  • Employee training procedures
  • Financial statements
  • Key employee or management résumés
  • Sample subcontractor agreements
  • Certificates and insurance requirements
  • Equipment maintenance procedures

Why so much information?
Because an underwriter is trying to understand the actual business.

Two demolition companies with identical revenue can represent completely different risks.

What Do Demolition Insurance Underwriters Want to Know?

Your Loss History Matters

Previous insurance claims can influence how an underwriter evaluates a demolition contractor.

But the number on the loss run isn’t always the entire story.

If your company experienced a significant loss, be prepared to explain:

What happened?

Why did it happen?

What did you change afterward?

An experienced underwriter may want to see evidence that the business learned from the event and implemented procedures intended to prevent a similar incident.

A strong explanation and documented corrective action can provide much more useful context than simply submitting a loss run without explanation.

Your Loss History Matters

Your Safety Program Can Affect More Than Employee Injuries

A written safety program shouldn’t exist solely because an insurance application asks whether you have one.

Good safety procedures can affect:

  • Employees
  • Customers
  • General contractors
  • Neighboring properties
  • Equipment
  • Project schedules
  • Insurance claims
  • Your reputation

Demolition contractors should be able to demonstrate that safety is part of how the business operates—not just something written in a binder.

Your Safety Program Can Affect More Than Employee Injuries

Why Specialty Demolition Insurance Experience Matters

Many insurance professionals can insure a contractor.

Far fewer regularly work with demolition risks.

That difference matters because demolition contractors frequently encounter specialized underwriting questions, contract requirements, exclusions, and coverage concerns.

Apollo General Insurance Agency has more than 60 years of experience in specialty commercial insurance and offers dedicated demolition contractor insurance programs.

Apollo’s demolition programs can accommodate operations ranging from residential and commercial tear-downs to interior strip-outs, depending on underwriting eligibility.

That experience helps Apollo understand both sides of the conversation:

What does the demolition contractor actually do?

And:

What does the insurance carrier need to understand before agreeing to insure it?

Why Specialty Demolition Insurance Experience Matters

Preparing for a Demolition Contractor Insurance Quote

Before requesting a quote, gather as much information as possible.

Start with:

  • Current insurance policies
  • Current and previous loss runs
  • Revenue and payroll information
  • Description of demolition operations
  • Largest completed projects
  • Largest anticipated projects
  • Subcontracting information
  • Equipment schedules
  • Safety programs
  • Sample contracts
  • Employee and management experience

Complete information can help underwriters understand your company more accurately.

And in specialty insurance, details matter.

Preparing for a Demolition Contractor Insurance Quote

Does Every Demolition Contractor Need Every Coverage Listed Here?

No.

A two-person residential demolition operation doesn’t necessarily need the same insurance program as a contractor performing multimillion-dollar commercial projects.

Likewise, insurance requirements differ by state, contract, project, client, operations, and company structure.

That’s why a demolition insurance program should be built around the contractor rather than copied from another business.

The important thing is understanding your exposures before a loss—or a contract requirement—reveals a gap.

Does Every Demolition Contractor Need Every Coverage Listed Here?

Demolition Contractor Insurance From Apollo General Insurance Agency

Demolition isn’t a sideline class of business for Apollo General Insurance Agency.

It’s one of Apollo’s specialty programs.

Apollo works with demolition risks involving residential tear-downs, commercial tear-downs, interior strip-outs, and other eligible demolition operations.

If you’re a demolition contractor—or an insurance broker trying to place a demolition account—the first step is understanding the operation in detail.

Learn more about Apollo’s demolition contractor insurance program at Apollo General Insurance Agency.

three-confident-construction-professionals-standin-2026-04-30-20-34-00-utc

Conclusion

So, what insurance does a demolition contractor need?

There isn’t one universal answer.

General liability may be the foundation, but a complete insurance program could also involve workers’ compensation, commercial auto, pollution liability, contractors equipment coverage, umbrella or excess liability, and specialized endorsements addressing contractual and operational exposures.

More importantly, demolition contractors need insurance that actually understands demolition.

The cheapest contractor policy won’t provide much value if exclusions, limitations, or missing endorsements prevent it from responding as expected—or keep you from qualifying for the projects you want.

Before your next bid, don’t just ask:

“Do we have insurance?”

Ask:

“Does our insurance match the work we’re actually doing?”

Conclusion APGen

Frequently Asked Questions About Demolition Contractor Insurance

1. What insurance does a demolition contractor need?

Depending on operations and applicable requirements, demolition contractors may need general liability, workers’ compensation, commercial auto, contractors equipment, pollution liability, and umbrella or excess liability coverage.

2. Is demolition covered by normal contractor general liability insurance?

Not necessarily. Demolition presents specialized exposures, and some contractor insurance programs may exclude or restrict certain demolition operations.

3. What is XC&U insurance?

XC&U refers to explosion, collapse, and underground exposures. Contractors should understand how their liability policy addresses these risks.

4. Why is collapse coverage important for demolition contractors?

Structural collapse is an inherent concern in demolition operations, making it important to understand any relevant exclusions or limitations within a liability policy.

5. Do demolition contractors need pollution liability insurance?

Some demolition operations may create pollution exposures that aren’t adequately addressed by standard general liability insurance. The need depends on the work being performed.

6. Do demolition contractors need workers’ compensation?
Requirements vary by state and business circumstances, but demolition contractors with employees commonly need workers’ compensation coverage.

7. Does demolition contractor insurance cover subcontractors?

Coverage depends on the policy, contracts, operations, and circumstances. Contractors should have appropriate subcontractor risk-management procedures rather than assuming subcontractors are automatically covered.

8. What insurance should my demolition subcontractors carry?

Requirements depend on the project and operations. General liability, workers’ compensation, commercial auto, and other coverage may be appropriate.

9. What is an additional insured?

An additional insured is a person or organization provided certain coverage rights under another party’s insurance policy through applicable policy language or endorsements.

10. What does primary and noncontributory mean?

It generally relates to the order in which applicable insurance policies respond to a covered claim and whether contribution is sought from certain other insurance.

11. What is a waiver of subrogation?
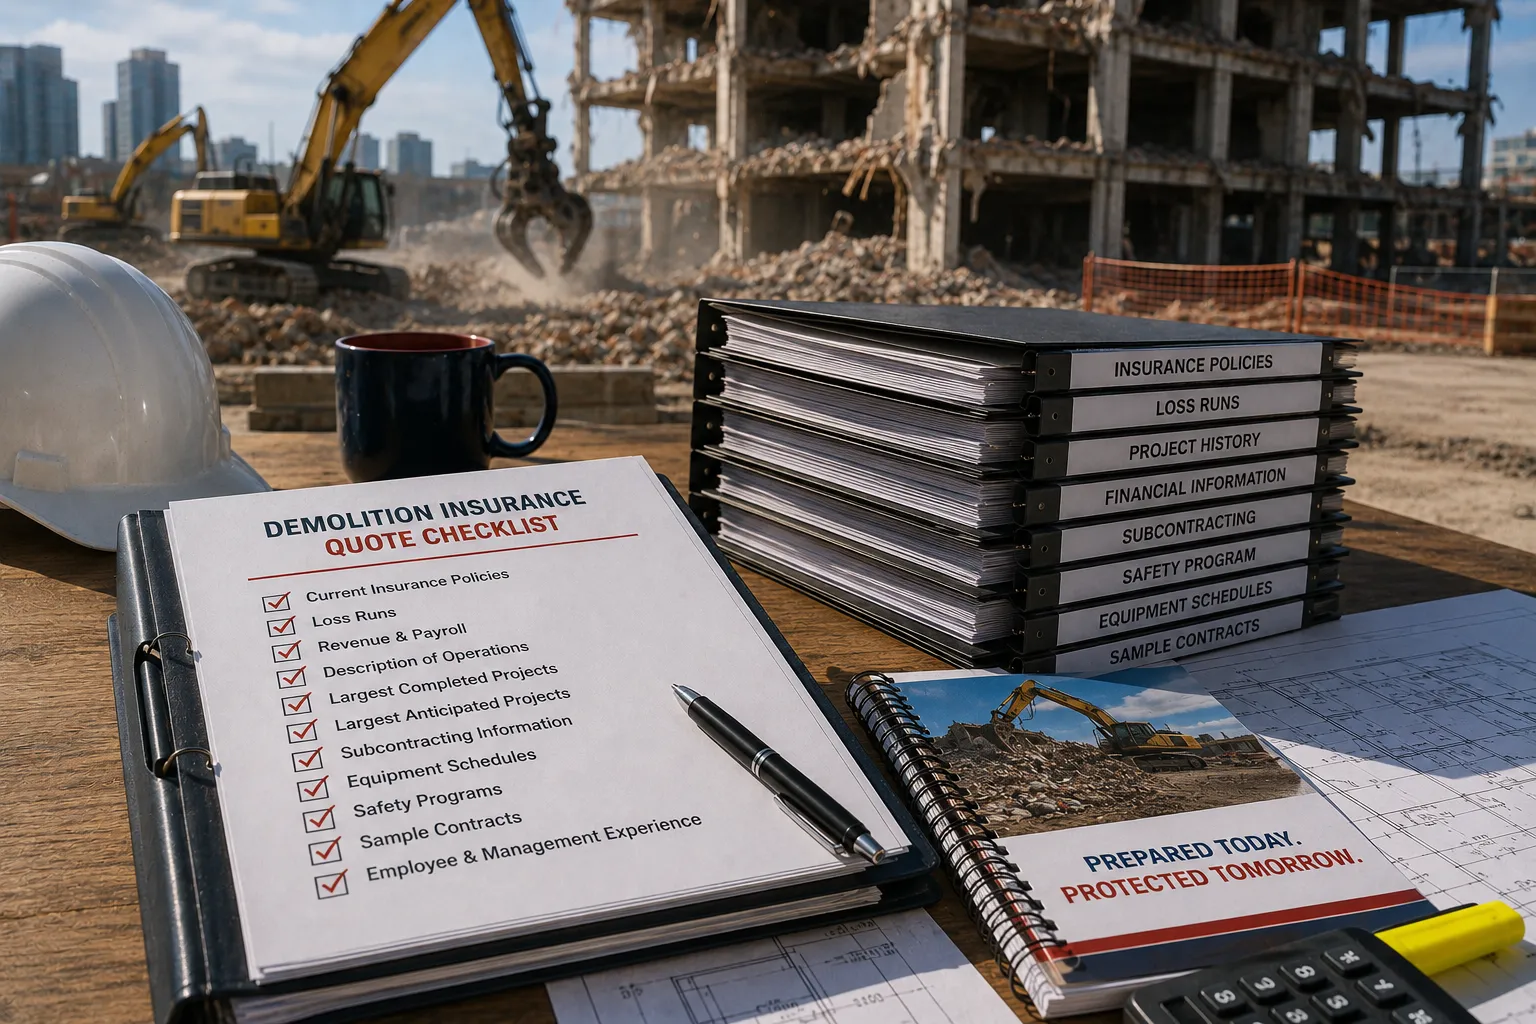
A waiver of subrogation can modify an insurer’s ability to pursue recovery from certain parties after paying a covered claim, subject to policy terms and applicable requirements.

12. What is completed operations coverage?
Completed operations generally addresses certain liability claims arising from work after the contractor has completed the operation.

13. Does a demolition contractor need commercial auto insurance?

If vehicles are owned or operated for business purposes, commercial auto insurance may be necessary depending on the circumstances.

14. How is demolition equipment insured?

Contractors equipment or inland marine coverage may be used to insure qualifying mobile equipment and tools against specified covered losses.

15. Does demolition insurance cover excavators?

Contractors equipment coverage may cover scheduled excavators and other qualifying equipment depending on the policy.

16. Does demolition contractor insurance cover damage to neighboring buildings?

Potential coverage depends on the cause of loss, applicable policy, exclusions, endorsements, and circumstances. This is an important exposure to discuss when evaluating demolition liability insurance.

17. How much does demolition contractor insurance cost?

There is no single price. Premiums can depend on revenue, payroll, operations, project sizes, subcontracting, geographic territory, loss history, limits, equipment, and other underwriting factors.

18. What documents do I need for a demolition insurance quote?

Underwriters may request applications, loss runs, financial information, project history, safety information, subcontractor agreements, equipment schedules, management experience, and other documents.

19. Can previous claims make a demolition contractor uninsurable?

Not necessarily. Underwriters may consider the type and severity of previous claims as well as corrective actions taken afterward.

20. Does Apollo General Insurance Agency specialize in demolition contractors?

Yes. Apollo General Insurance Agency offers specialty demolition contractor insurance programs for eligible operations, including residential and commercial tear-downs and interior strip-outs.