
Insurance for House Lifting Contractors

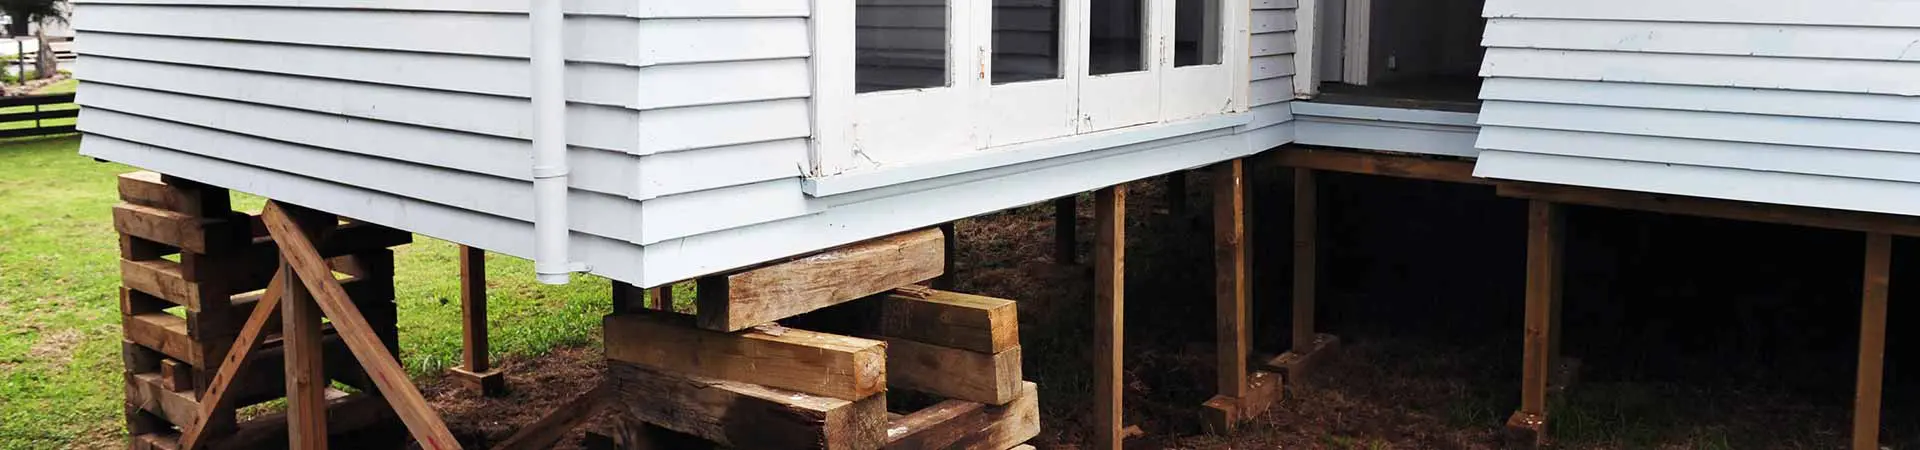
House lifting can be extremely complicated to insure. An average home weighs between 80,000-160,000 pounds — close to 80 tons on the high side — and that figure is often calculated without foundation or concrete floor slabs taken into account. When lifting a structure of that size, there needs to be a comprehensive and specific insurance for house lifting that covers both the house being lifted (and possessions therein) as well as coverage for nearby dwellings.

Contractors that specialize in lifting are often a client’s sole resource to protect or improve a property, i.e. preventing flooding, adding a story, or increasing space in a commercial building. Clients and subcontractors will require proof of acceptable insurance for house lifting before trusting this activity to you. You can trust in our decades-long expertise in this industry to provide the right level of House Lifting Contractors Insurance for your business.
Who This Serves – Operations and Exclusions

Apollo General’s Insurance for House Lifting Contractors offers operations for small- to medium-sized risks engaging in these activities

Risks that are currently ineligible for this include those who operate outside designated, state-approved territory, subcontract more than 20% of their operations, and who act as a general contractor, construction manager, builder or developer. Additionally, new operations and contractors who work on piers, basements, foundational, or structural concrete work are also ineligible.

House Lifting Contractor

House Lifting Contractors

Our AM Best Rated A+15 offers superior insurance for House Lifting Contractors and includes these primary benefits:

  • Blanket Additional Insured – where contract required
  • Waiver of Transfer of Rights of Recovery Against Us to Others – where contract required
  • Primary and Noncontributory – where contract required
  • Per Project/Location General Aggregate ($5 million Cap)
  • Employee Benefits Liability
  • Stop Gap option available

The minimum premium is $25,000.

Additional Coverage Options to Fit Your Custom Needs

Our experienced insurance Account Managers will assess business risks and activity to customize policies to your needs. You can purchase Excess Liability, Contractors Pollution Liability, Business Automobile Liability, Property and Equipment Liability, Surety Bonds, and Worker’s Compensation as a separate policy in addition to your General Liability Insurance to ensure all your activities are fully covered.

How to Purchase Your House Lifting Contractors Insurance

You can request a quote below or have your broker contact us. The following documents are needed for the application submission process:

  • 5 years currently valued loss runs
  • Narrative on any losses in excess of $10,000
  • Completed Supplemental Application, signed and dated
  • Completed Acord Applications
  • Signed copy of contracts used with subcontractors
  • Complete description of operations

Download, complete and return our application to our Account Manager or to our submission inbox at: submissions@apgen.com

Account Manager Contact